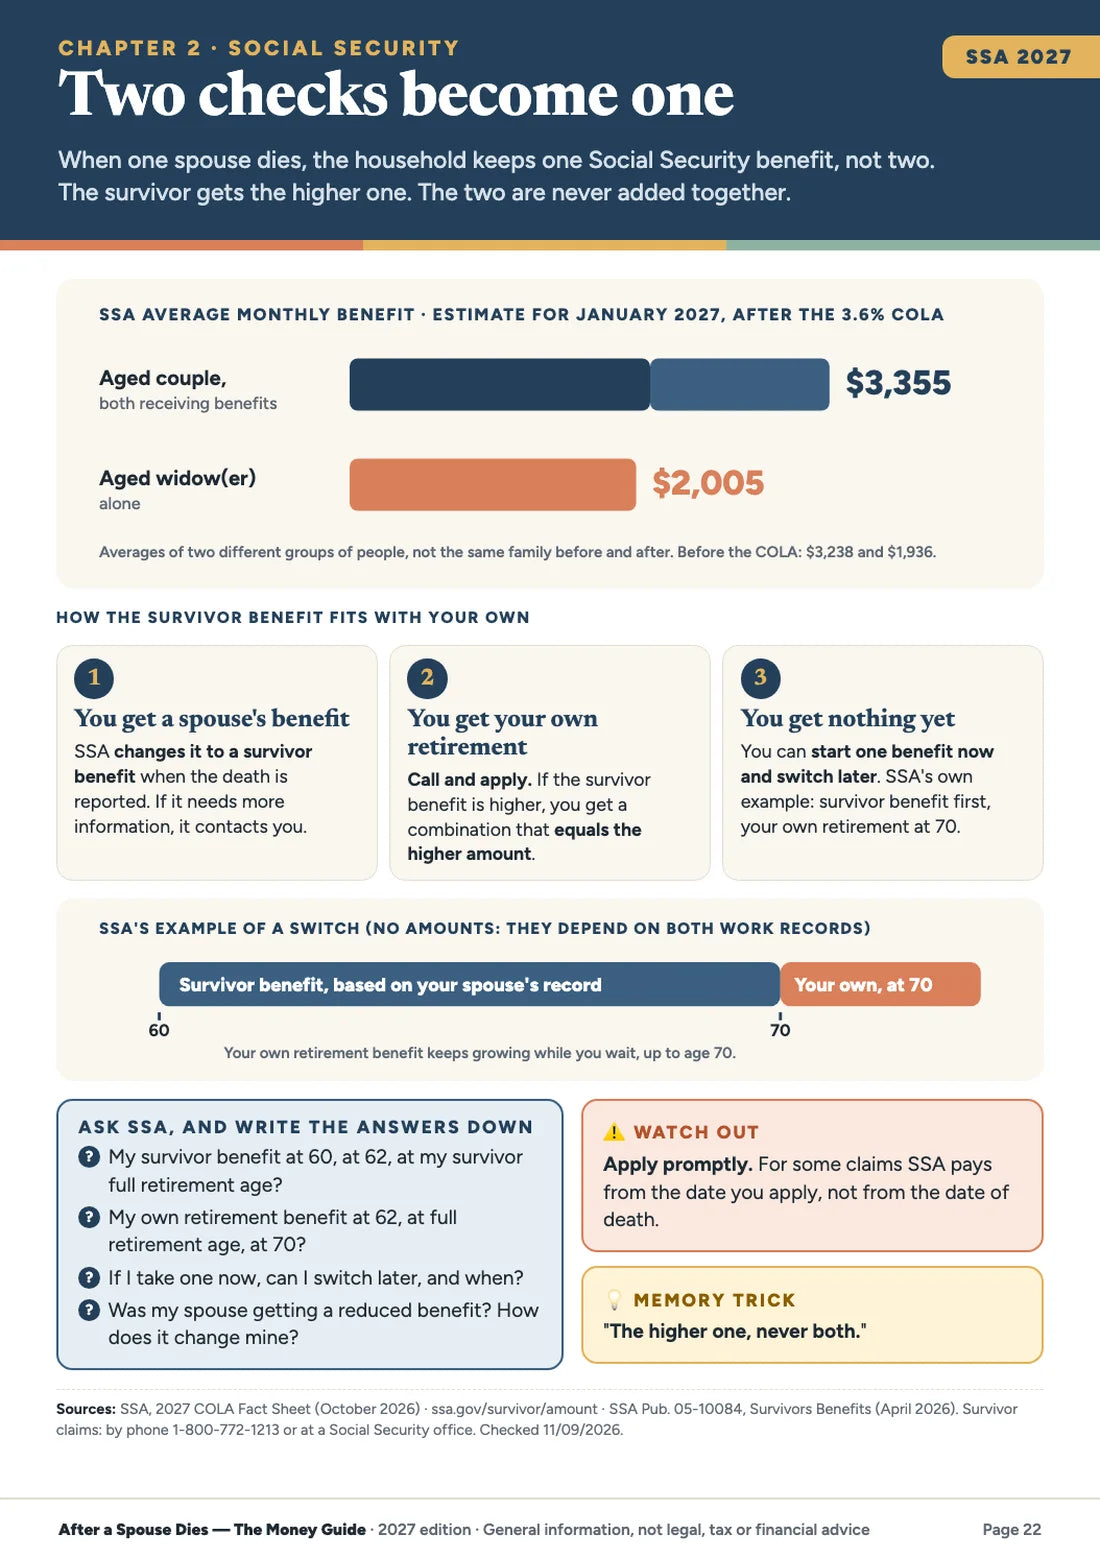
Two Social Security checks become one.
Here's the money side, page by page.
An illustrated guide to the first year after a spouse's death in the U.S.: survivor benefits and when to claim them, pensions and the IRA, the house and the mortgage, taxes, health coverage, and the calls that come after. 200 pages with 2026–2027 numbers and the official source behind each one. eBook or printed book.
The book on the kitchen table, the PDF for the son or daughter who lives far away · $79.99
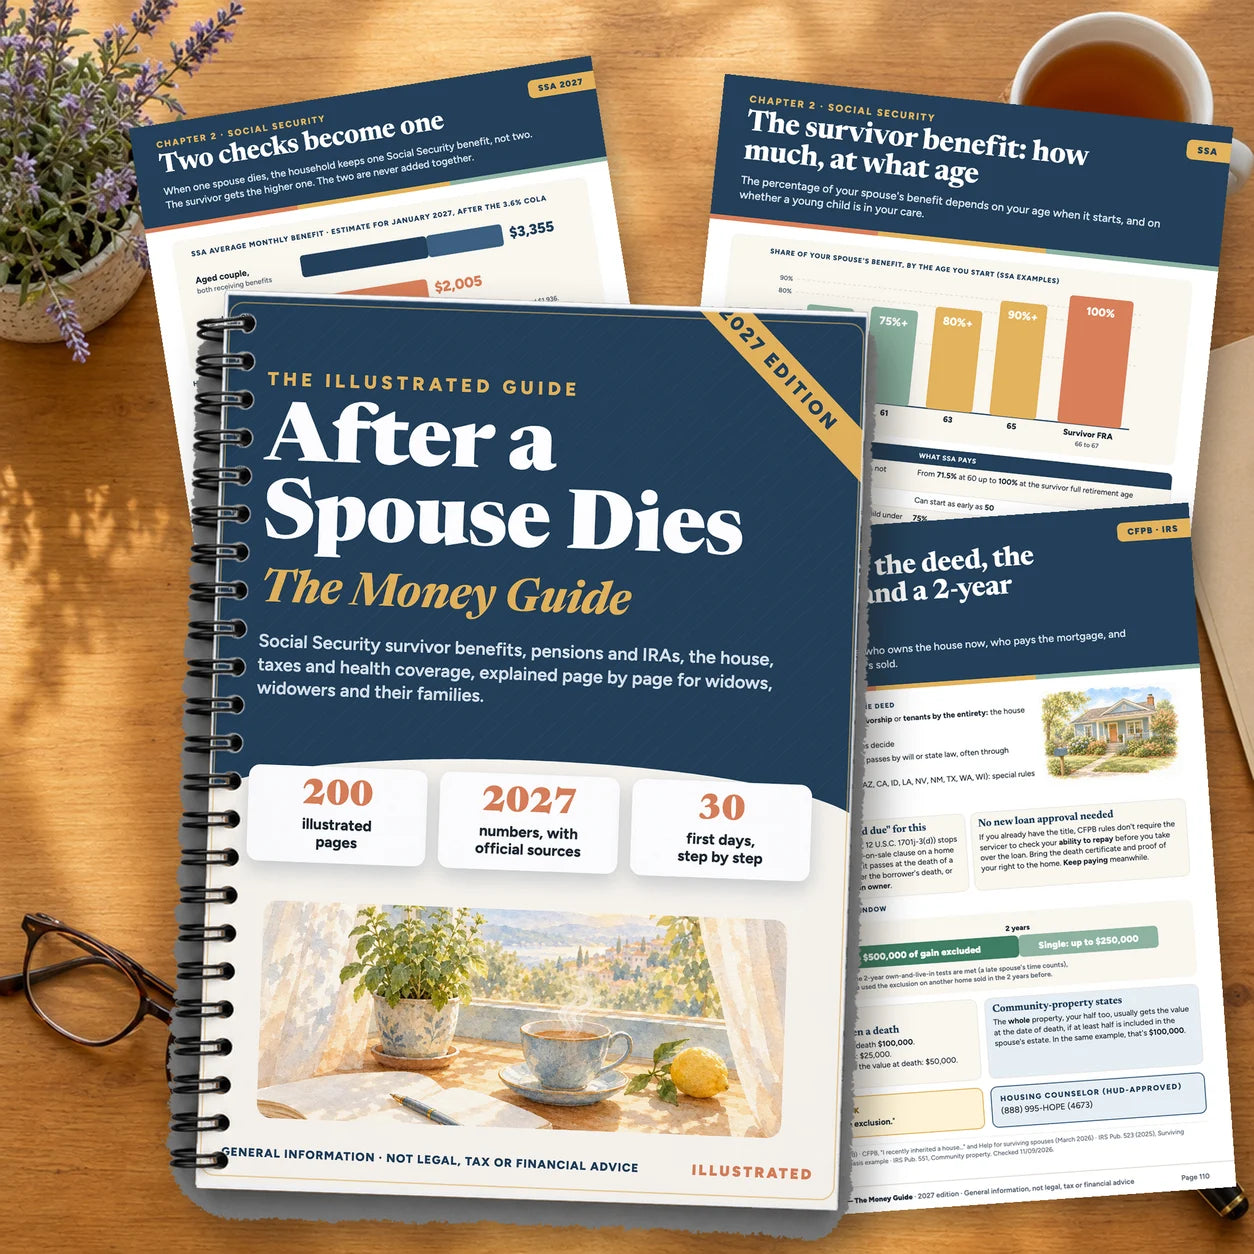
Not a wall of text. One question per page.
Every page works the same way, so the answer, the number and the next step are easy to find, even on a tired day.
This is what the pages look like.
For the spouse left with the paperwork, and the family helping.
Too many calls, no list
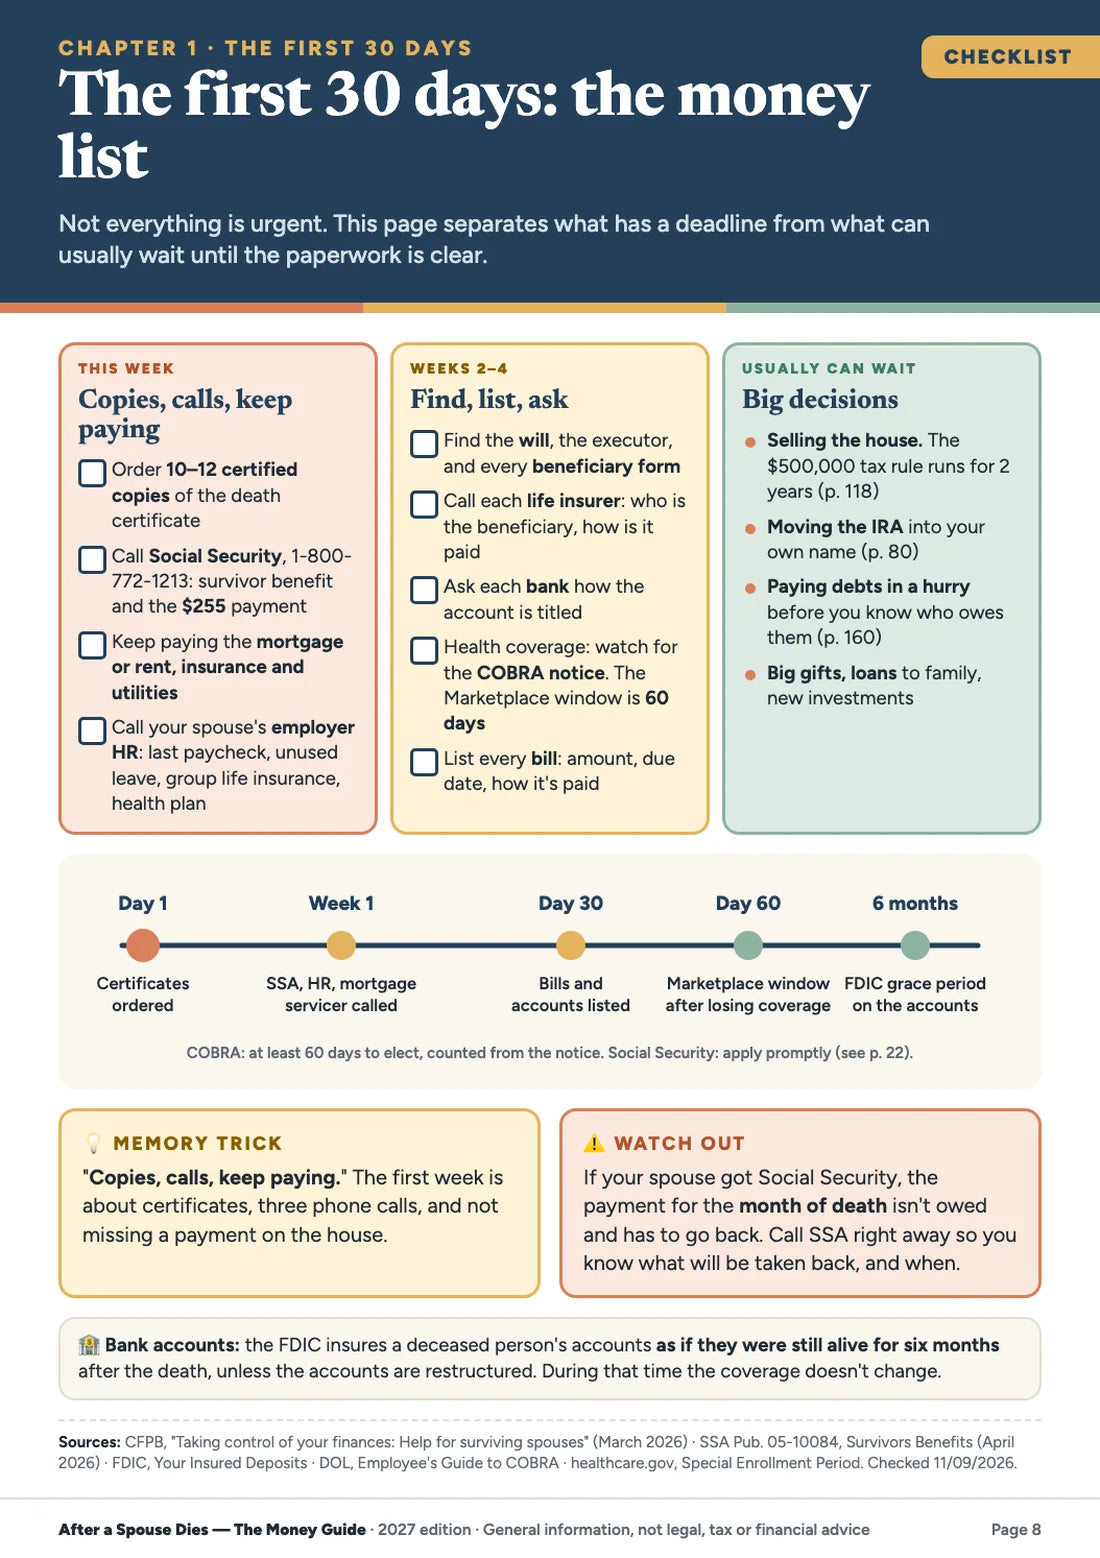
Which calls have a deadline, which papers to find, which big decisions can usually wait.
Benefits, accounts, the house
Social Security, the pension and the IRA, the mortgage, health coverage and the tax return of the year of death.
Helping from near or far
Adult children can read the same pages and bring the same questions to SSA, the CPA or the plan administrator.
What's worth knowing before the first big decision.
These rules are written down by Social Security, the IRS and Medicare. The book explains each one with a chart and the source.
Two benefits are never added together
A survivor gets the higher one. SSA's own example: start the survivor benefit, then switch to your own retirement at 70.
"Treat it as your own" has a catch
Before 59½, withdrawals from an IRA treated as your own may owe the 10% additional tax. As a beneficiary, they don't.
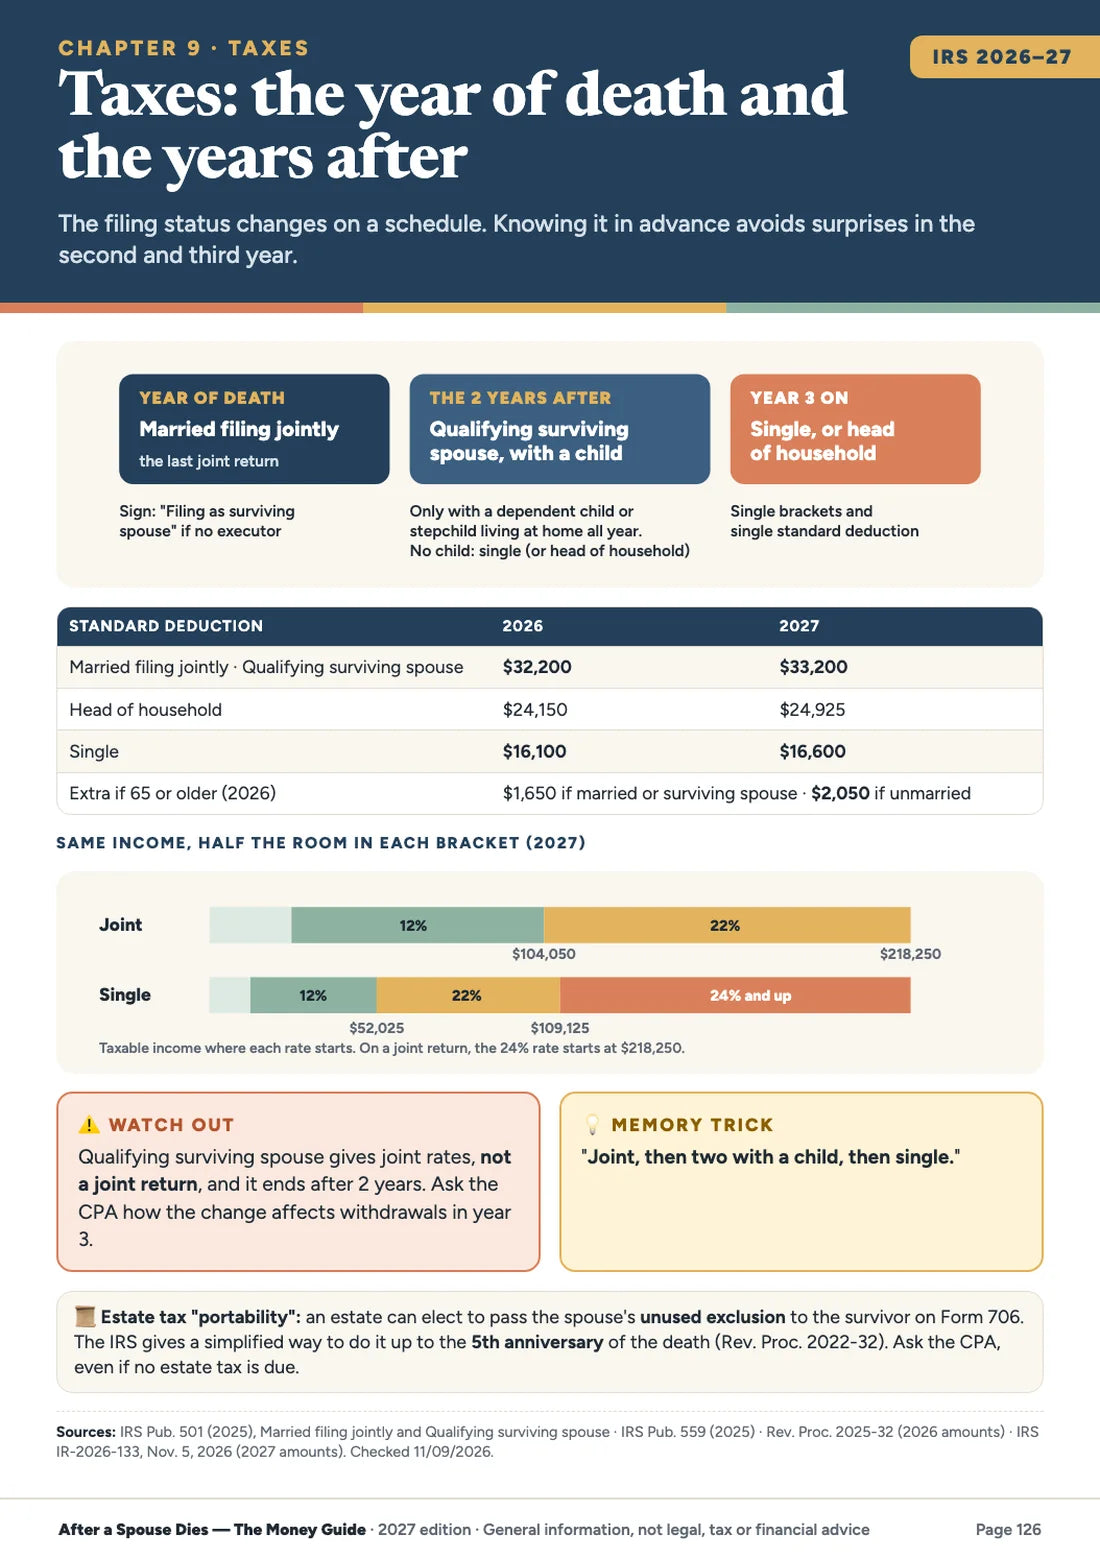
The filing status changes on a schedule
A joint return for the year of death, "qualifying surviving spouse" for 2 years only with a dependent child, then single.
Which benefit, when, and how much.
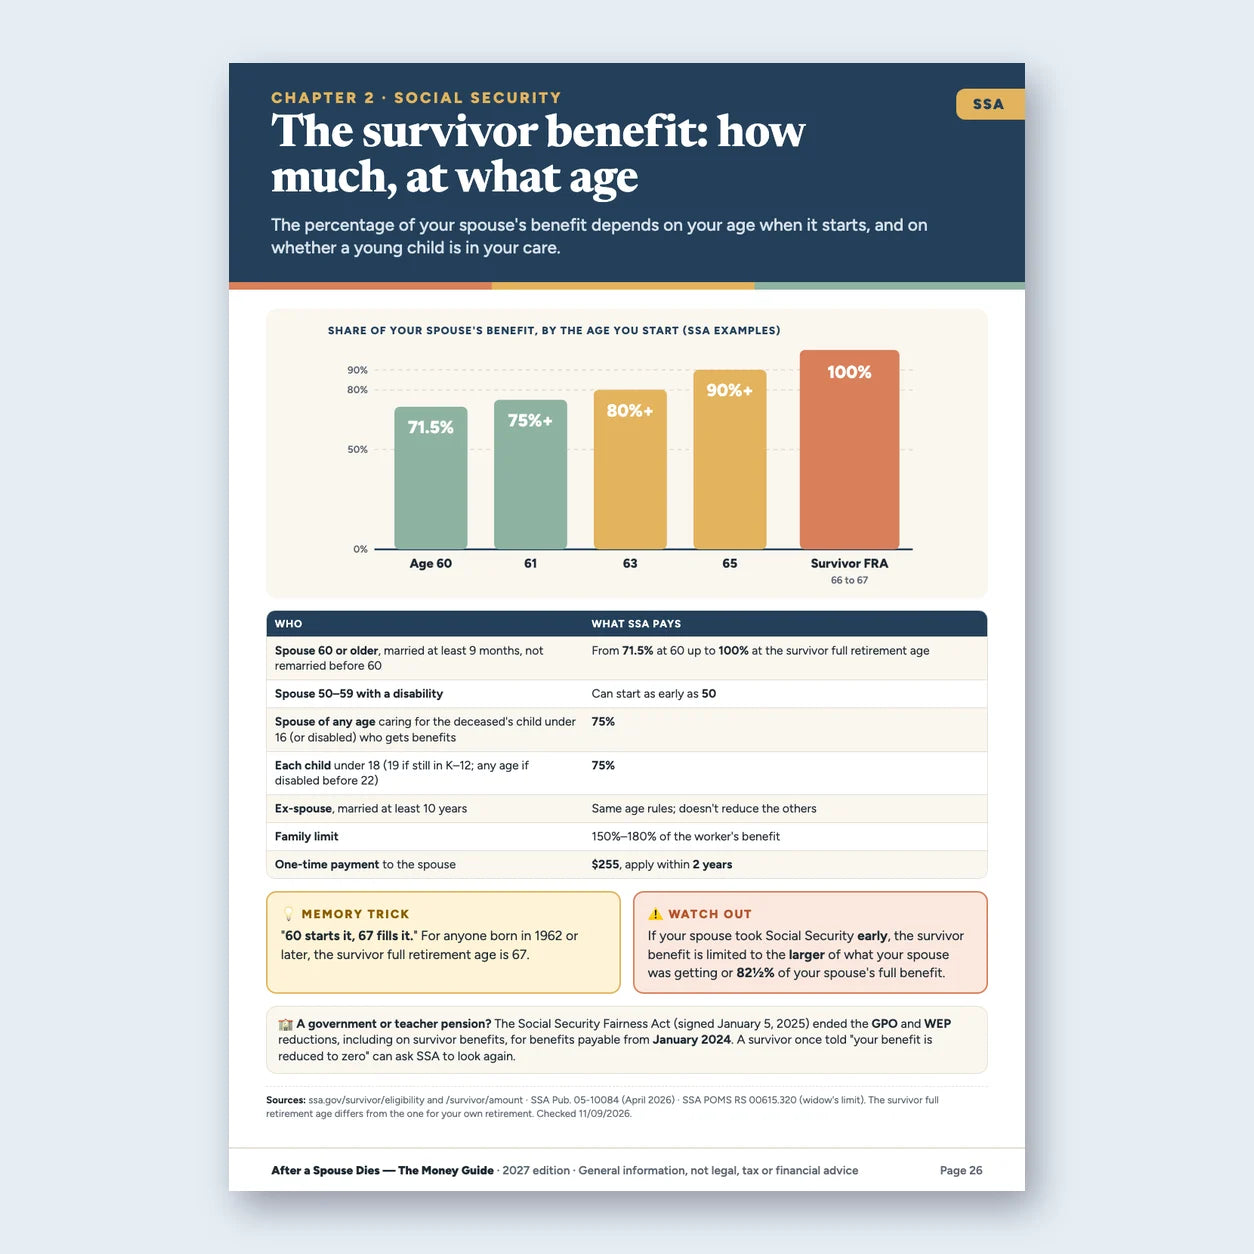
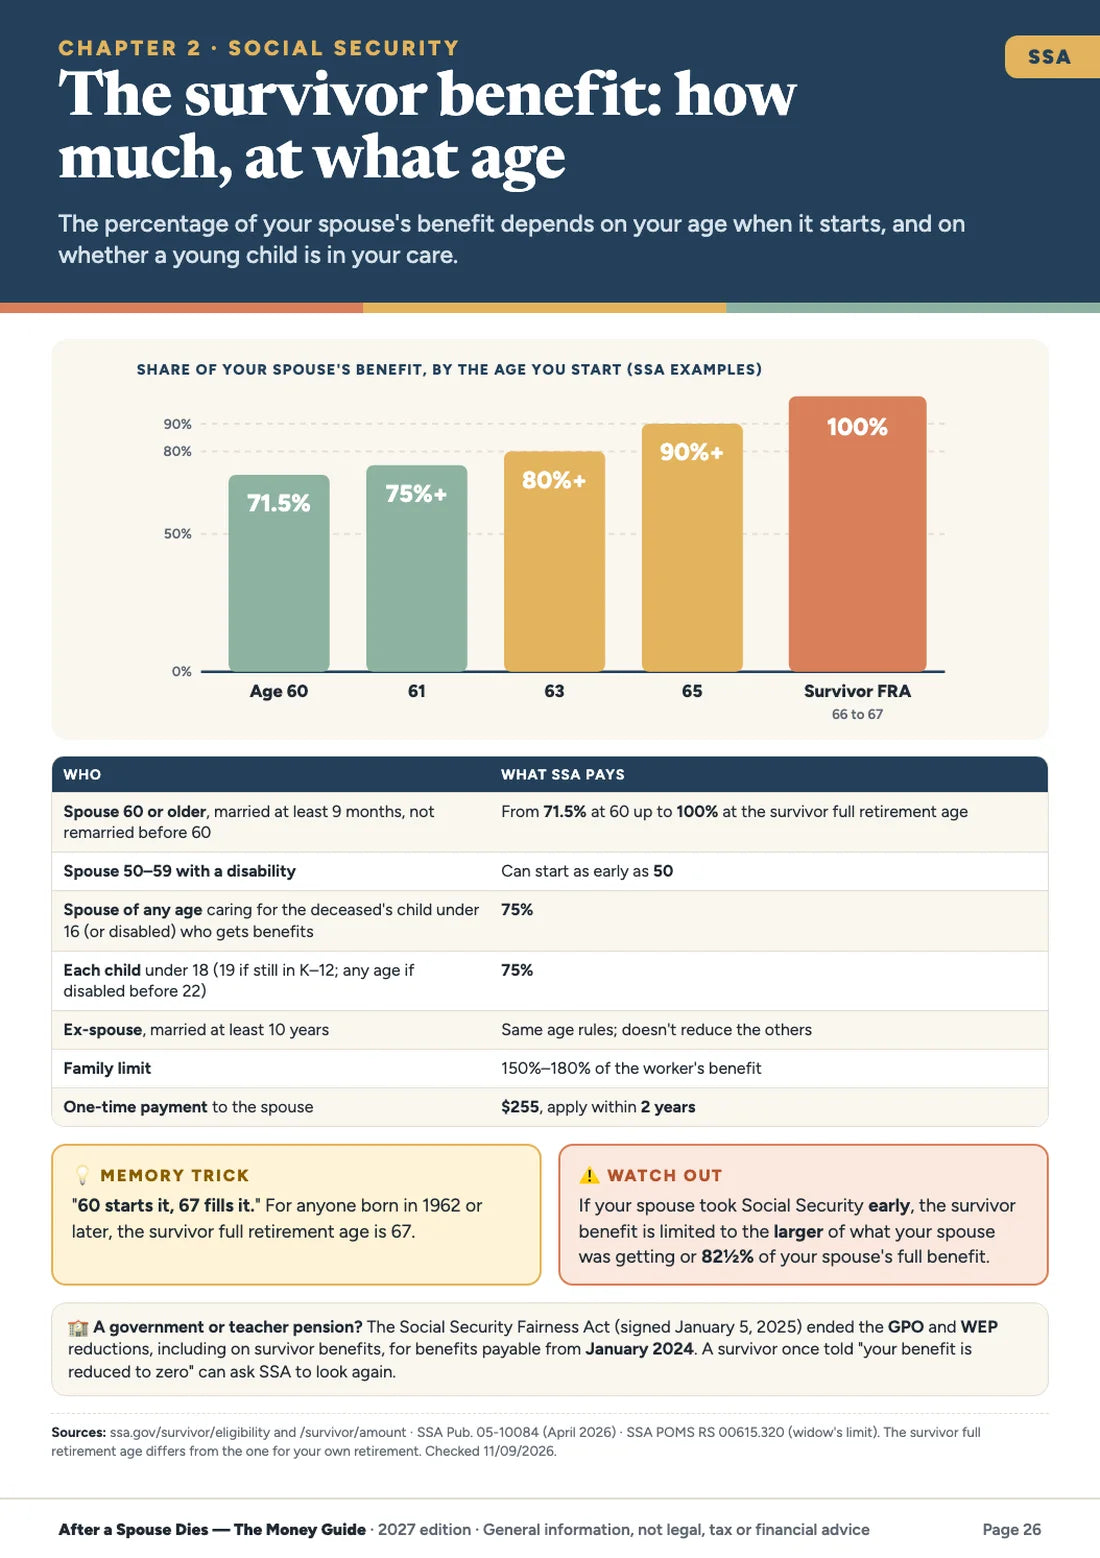
The survivor benefit is a percentage of the spouse's benefit that depends on the age you start. The book shows each step.
- From 71.5% at 60 to 100% at the survivor full retirement age
- 75% at any age with the deceased's child under 16 in your care
- The widow's limit when the spouse claimed early
- The $255 payment and the 2-year deadline to apply
- The end of the GPO and WEP reductions for benefits from January 2024
Working, or marrying again, without surprises.
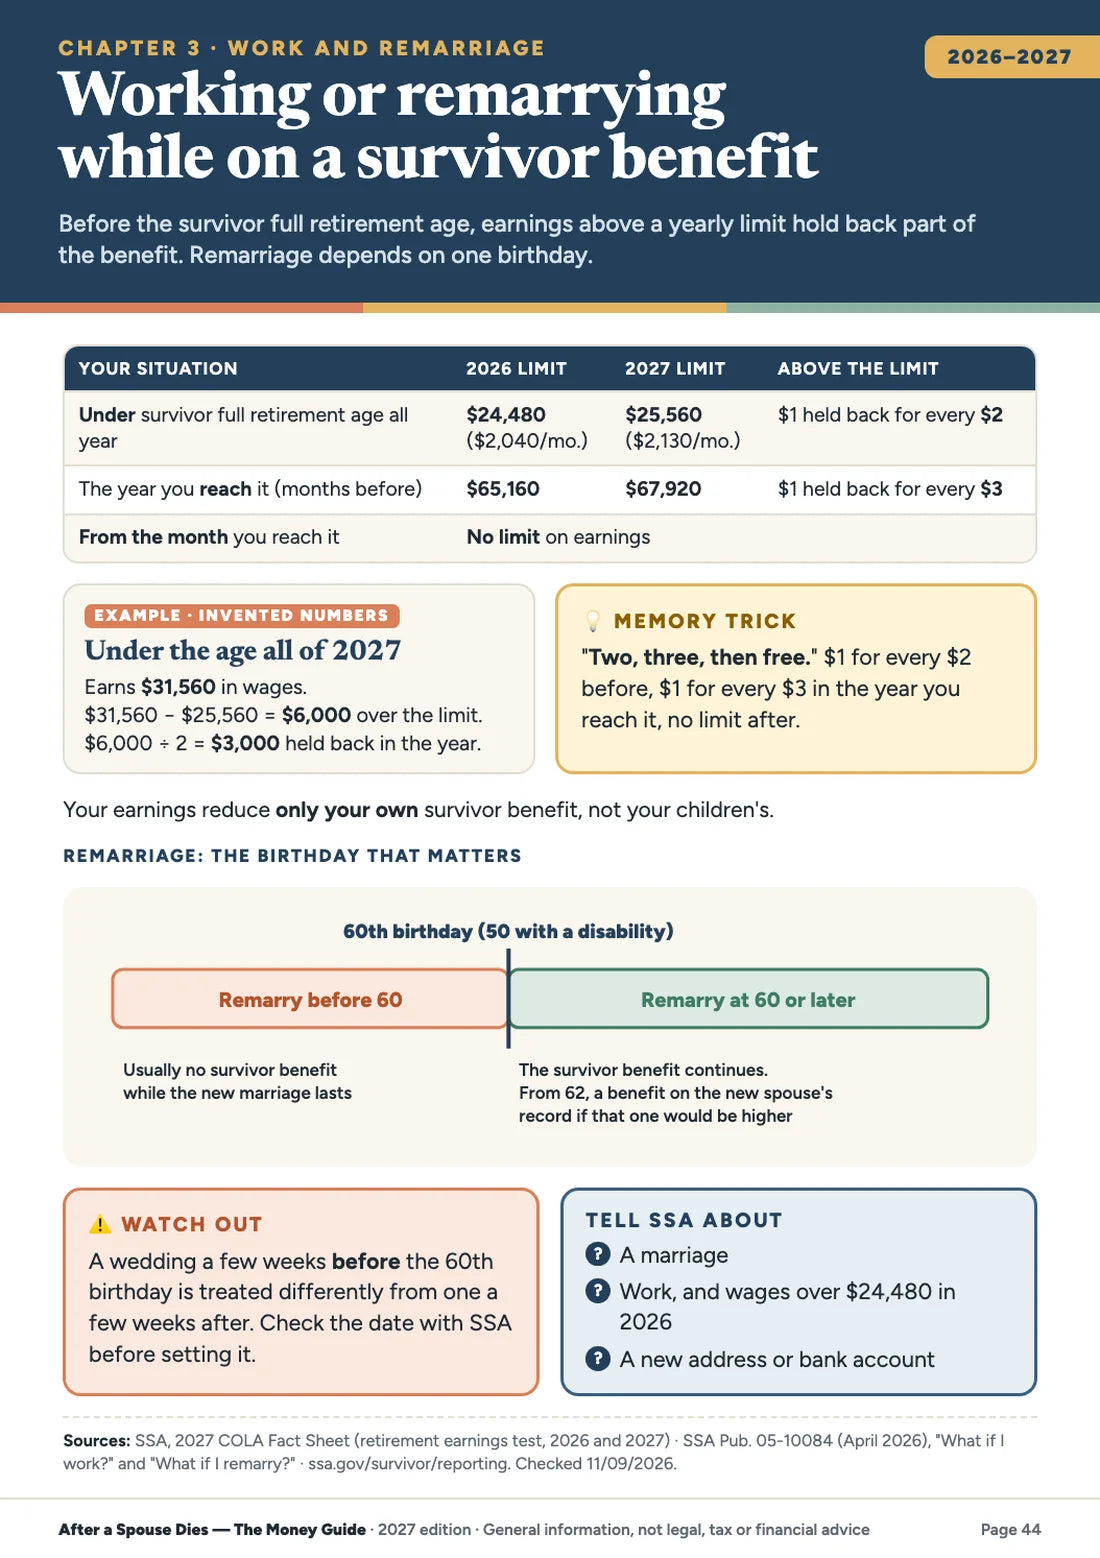
Before the survivor full retirement age, earnings above a yearly limit hold back part of the benefit. And one birthday decides what remarriage changes.
- 2026 limit $24,480, 2027 limit $25,560: $1 held back for every $2 above
- The year you reach full retirement age: $65,160 in 2026, $67,920 in 2027
- Remarriage before 60 vs at 60 or later
- What to report to SSA, and when
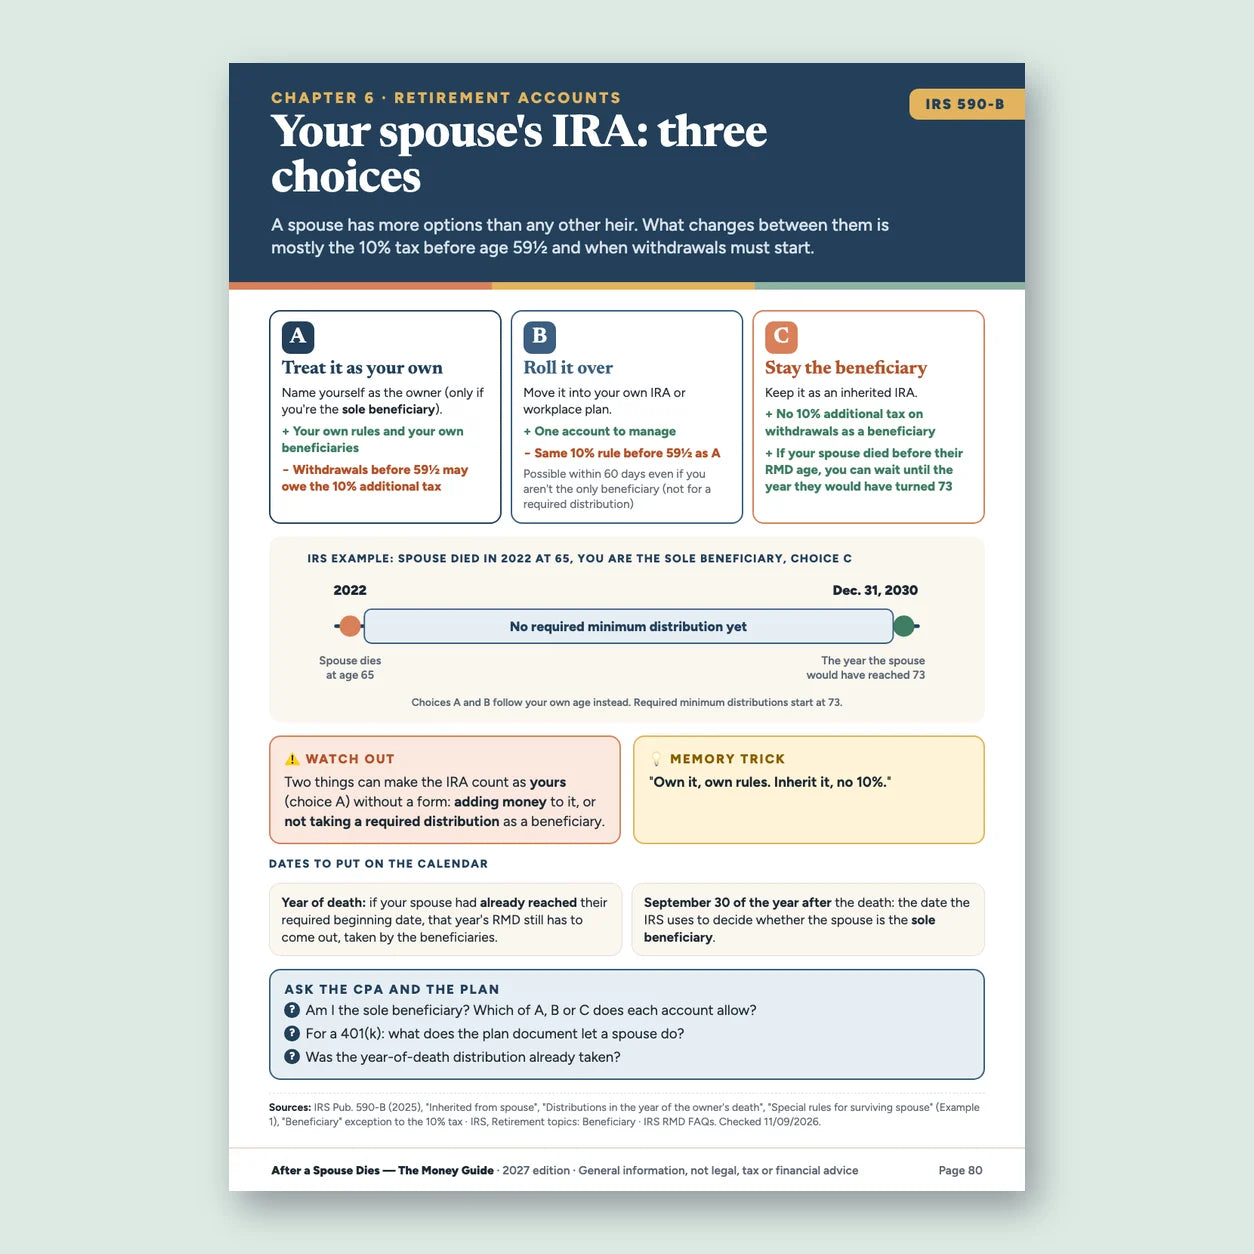
The spouse's IRA and 401(k), side by side.
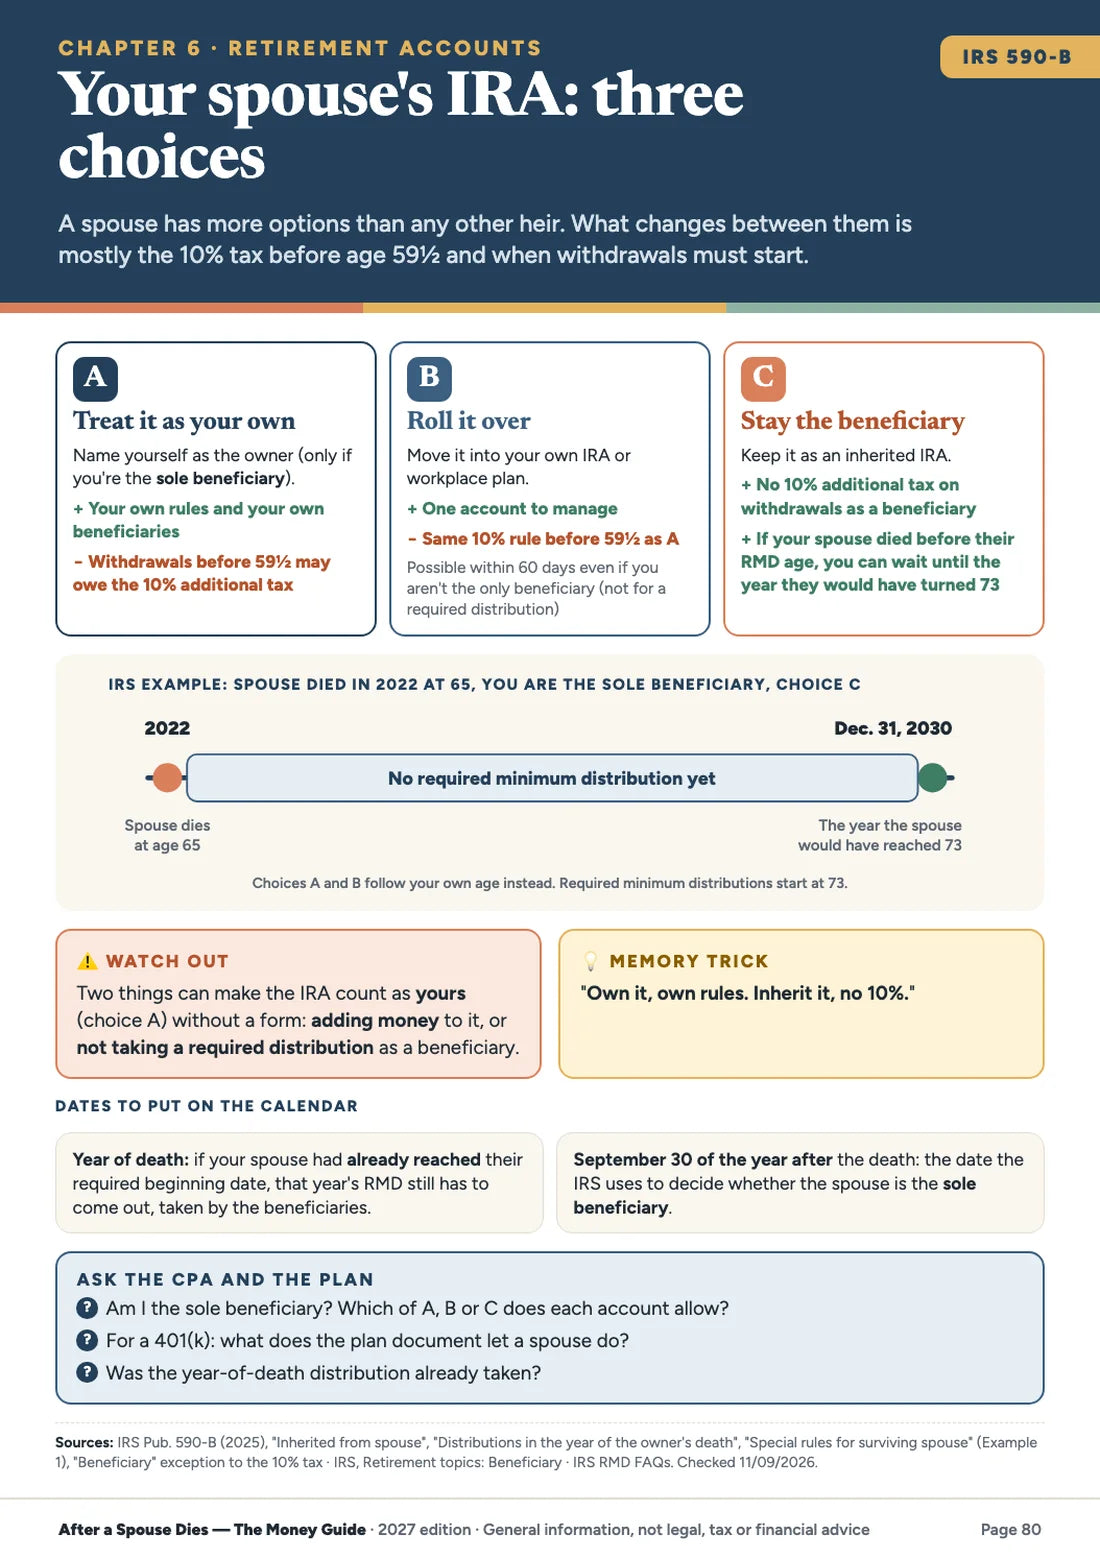
A spouse has three choices for an inherited IRA. The book shows what changes between them, with the IRS's own example.
- Treat it as your own, roll it over, or stay the beneficiary
- The 10% additional tax before 59½, and when it doesn't apply
- The year-of-death distribution and the September 30 date
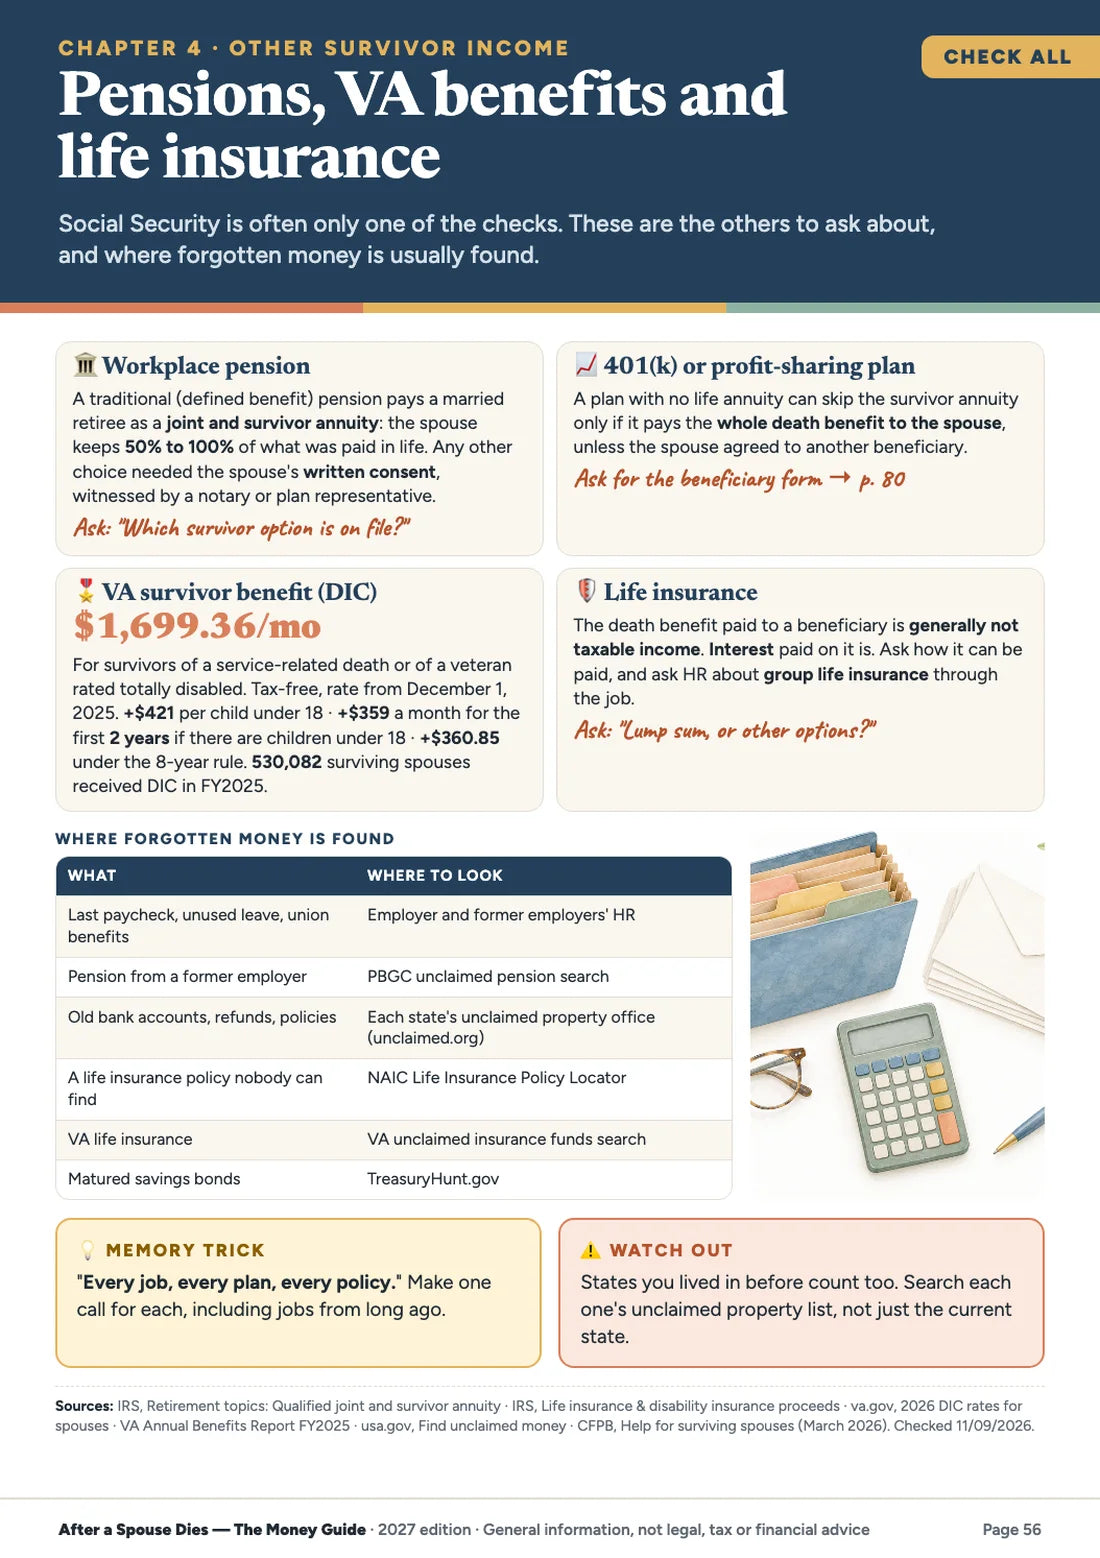
- Pensions: the 50% to 100% survivor annuity
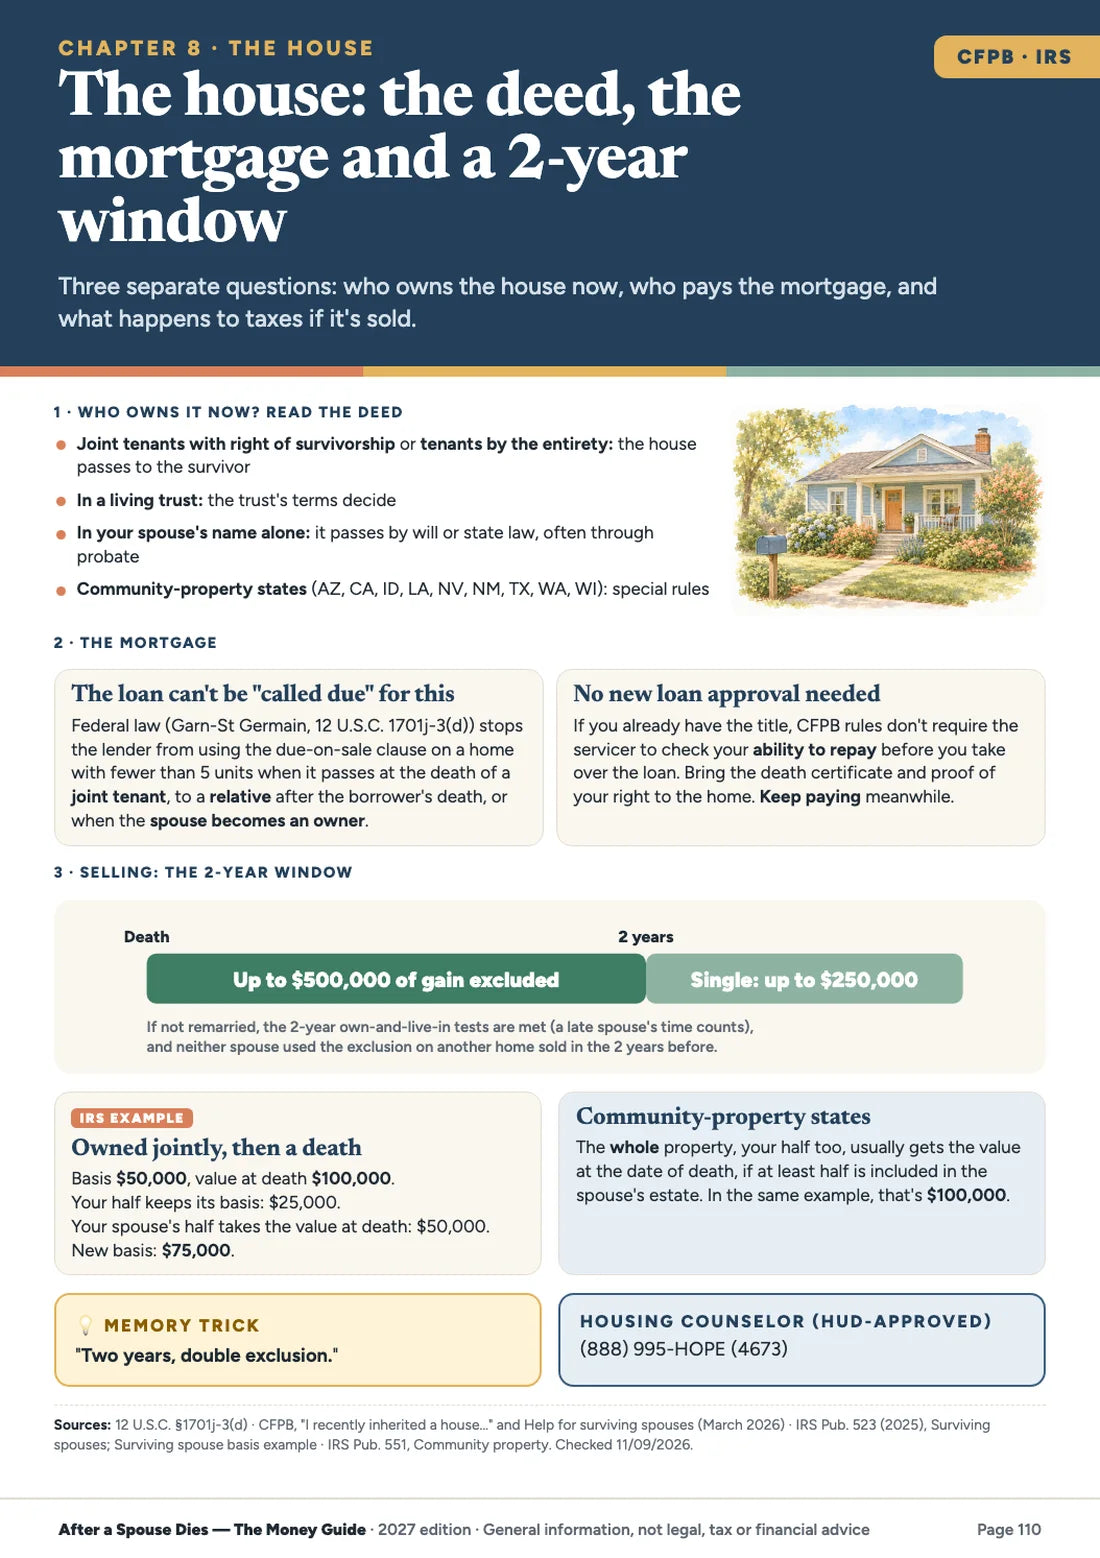
The deed, the mortgage and the 2-year window.
Who owns the house now, why the lender can't call the loan due because of the death, and what happens to taxes if it's sold.
- Federal law on due-on-sale clauses after a death (12 U.S.C. 1701j-3)
- CFPB: no new ability-to-repay review when you already have the title
- Up to $500,000 of gain excluded if sold within 2 years
- The IRS basis example, and the community-property rule
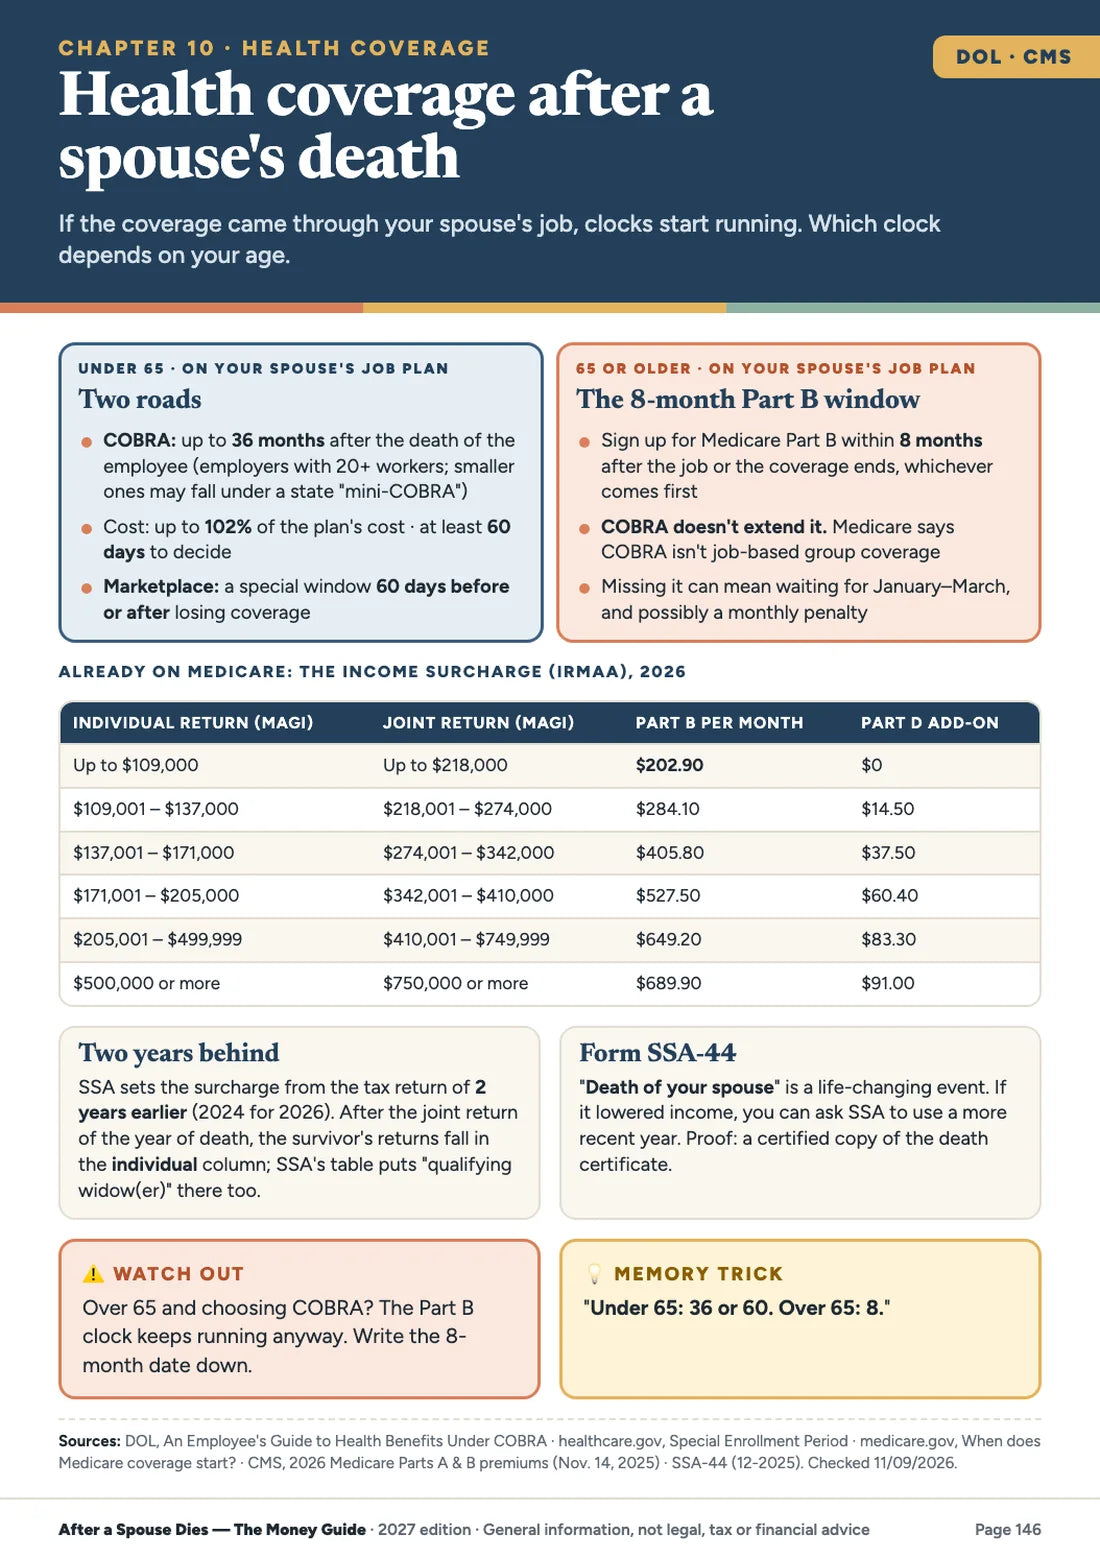
Health coverage: the clocks that start running.
If coverage came through the spouse's job, the age of the survivor decides which deadline matters.
- COBRA: up to 36 months after the death of the employee
- The Marketplace window: 60 days
- 65 or older: the 8-month Medicare Part B window, which COBRA doesn't extend
- The 2026 IRMAA table and Form SSA-44
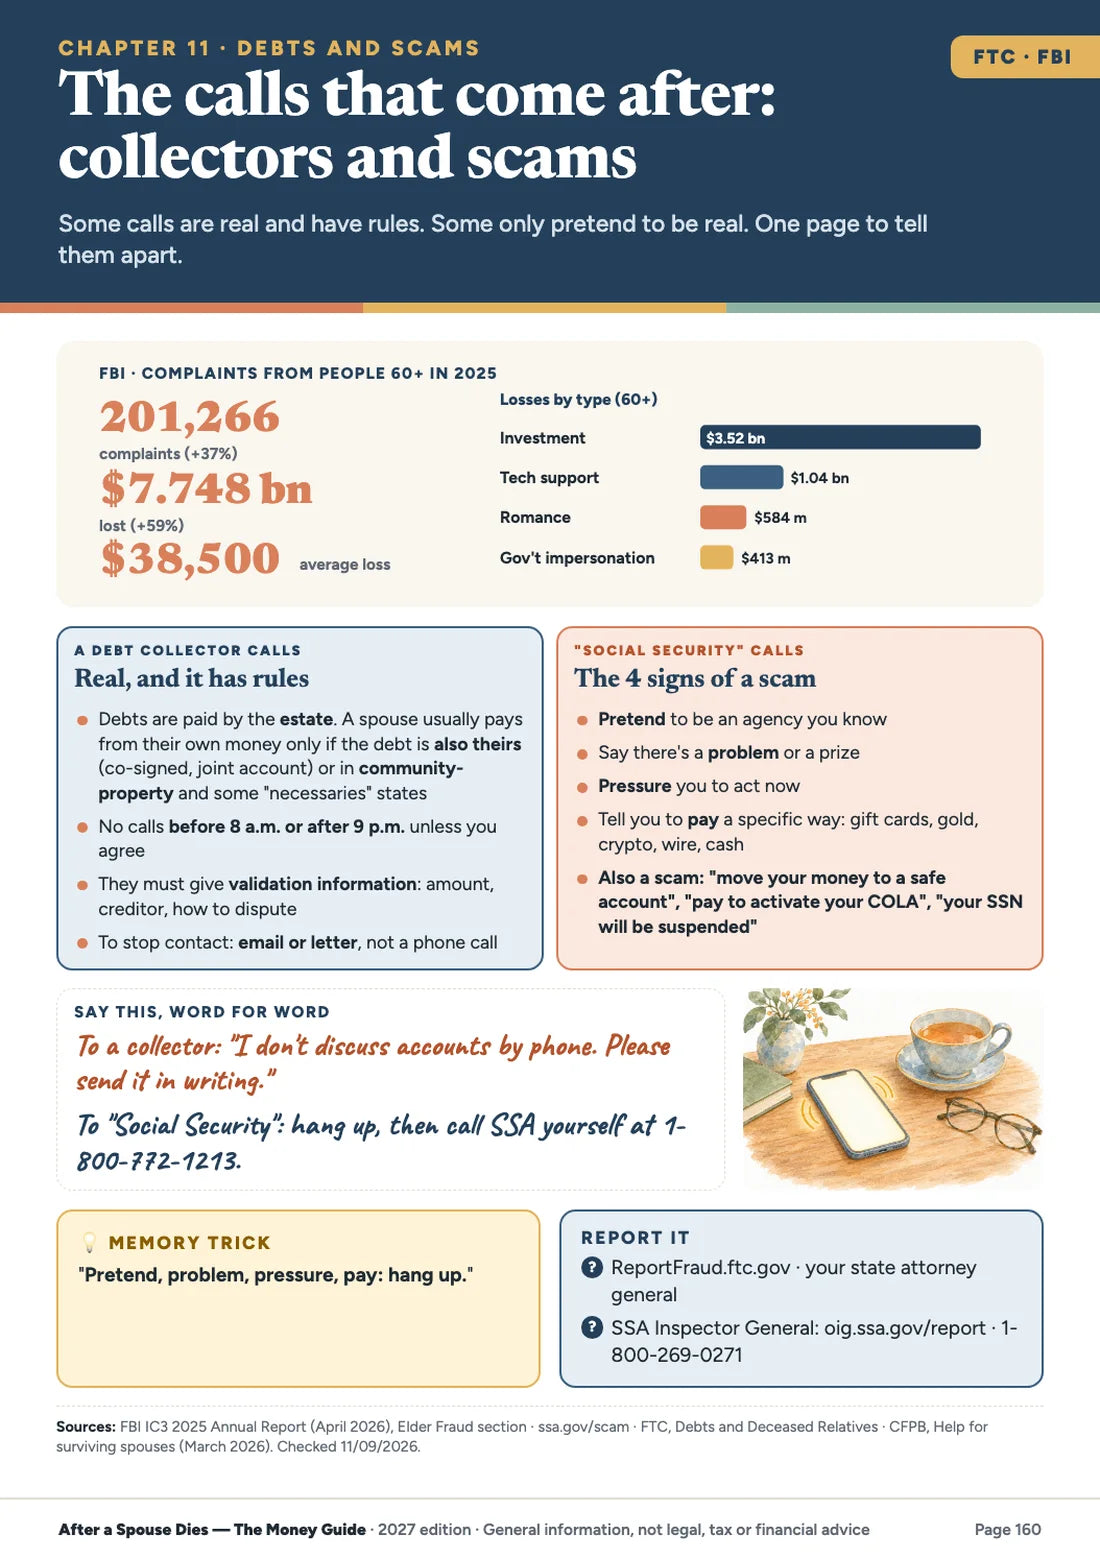
Tell a real call from a fake one.
Debt collectors have rules. Scammers pretend to be Social Security. One page shows the difference, with what to say.
- When a spouse can be responsible for a debt, and when not
- The 4 signs of a scam, from Social Security
- FBI 2025: people 60+ reported $7.748 billion in losses
- Where to report it
The whole family looks at the same page.
A son or daughter can help from the same pages, write down SSA's answers in the same place, and bring the same questions to the CPA.
- Built on official sources, cited on every page
- Reviewed every year, because the numbers change
- Questions to ask SSA, the CPA, the plan and the lender at the end of each topic
The money side of the first year, in one guide.
Full table of contents
On screen, on paper, or both.
Color PDF, right after payment
Open it on a phone, tablet or computer and share it with the family. Print the checklists and worksheets as many times as you need.
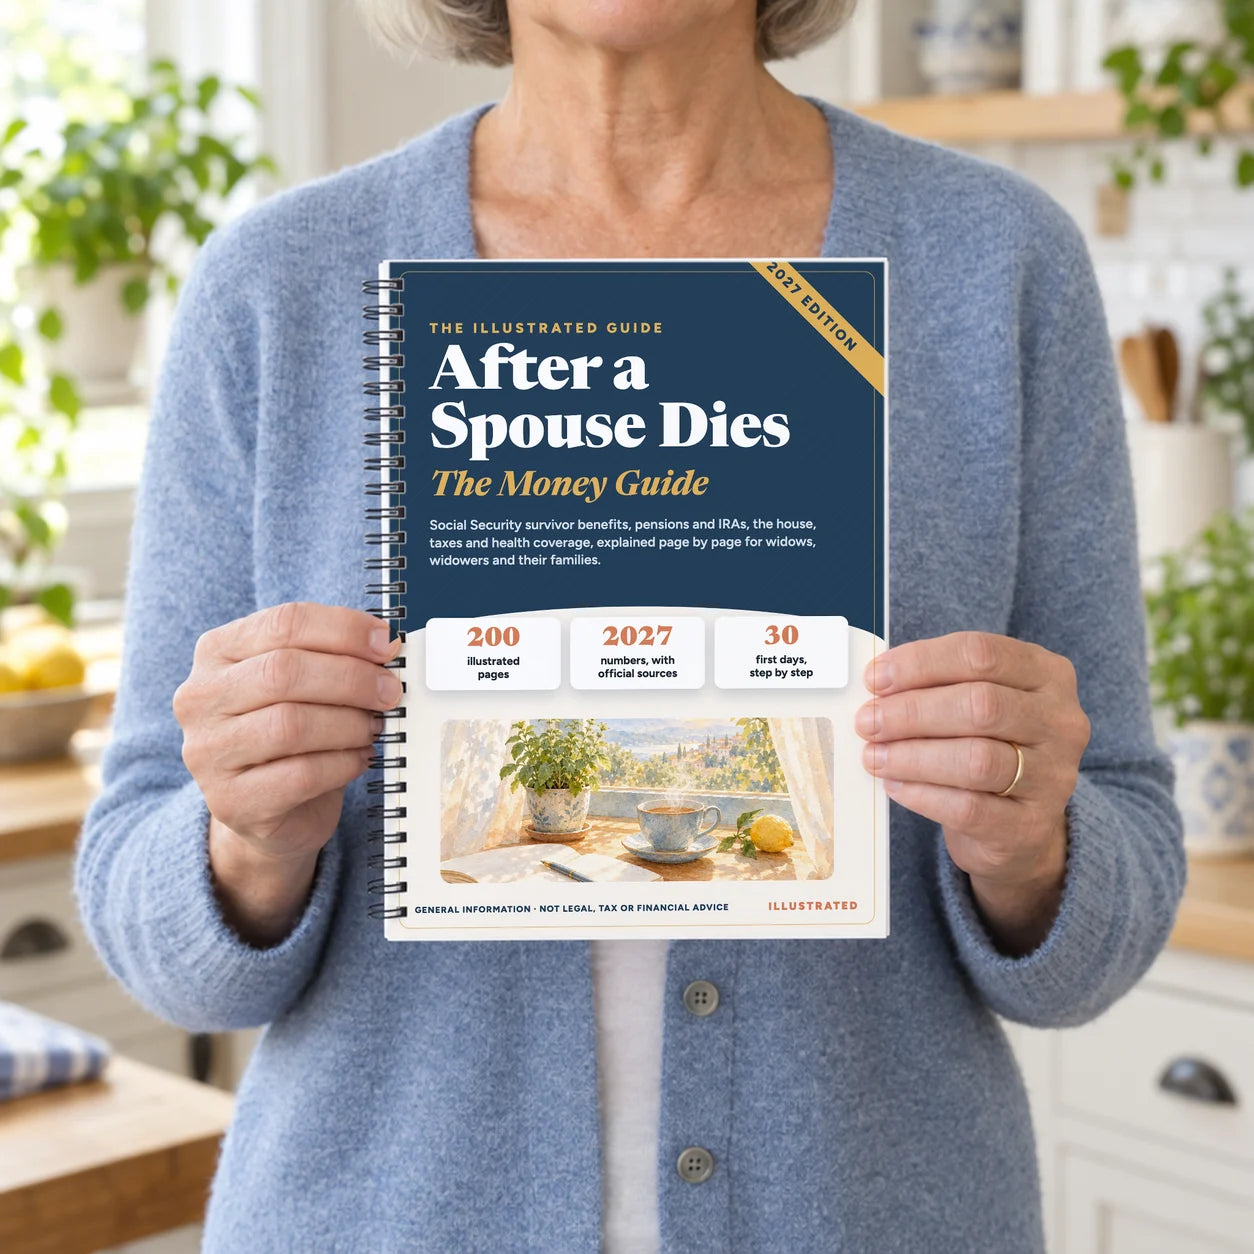
200 color pages, spiral-bound
Lies flat next to the letters and the phone. Free U.S. shipping, about 5–8 business days. Want both? Printed + eBook for $79.99.
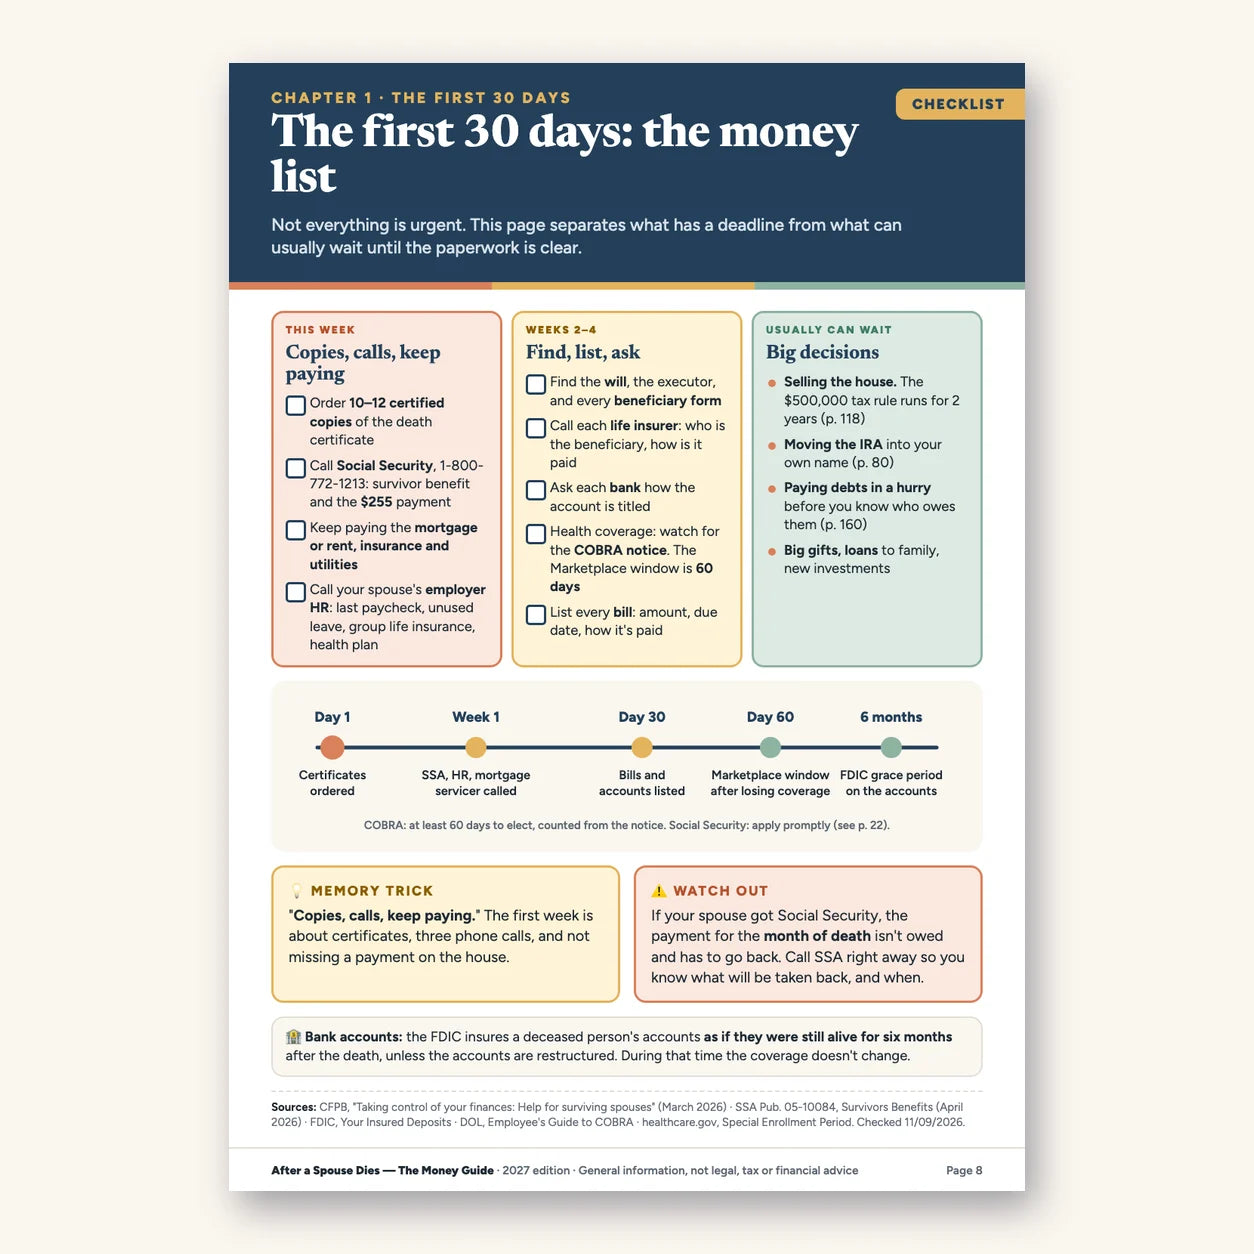
The checklist and the worksheets.
The first 30 days in three columns, then the worksheets to keep everything in one place: bills, accounts and beneficiaries, calls made and answers received.
- The first 30 days, as a checklist
- Bills list, accounts and beneficiaries, call log, first-year budget
- With the eBook: print them again whenever you need
See 10 real pages, free.
The first 30 days, two checks become one, the benefit by age, work and remarriage, pensions and life insurance, the spouse's IRA, the house, taxes, health coverage, and the calls that come after. Read them and decide with the pages in front of you.
See the 10 pages ↓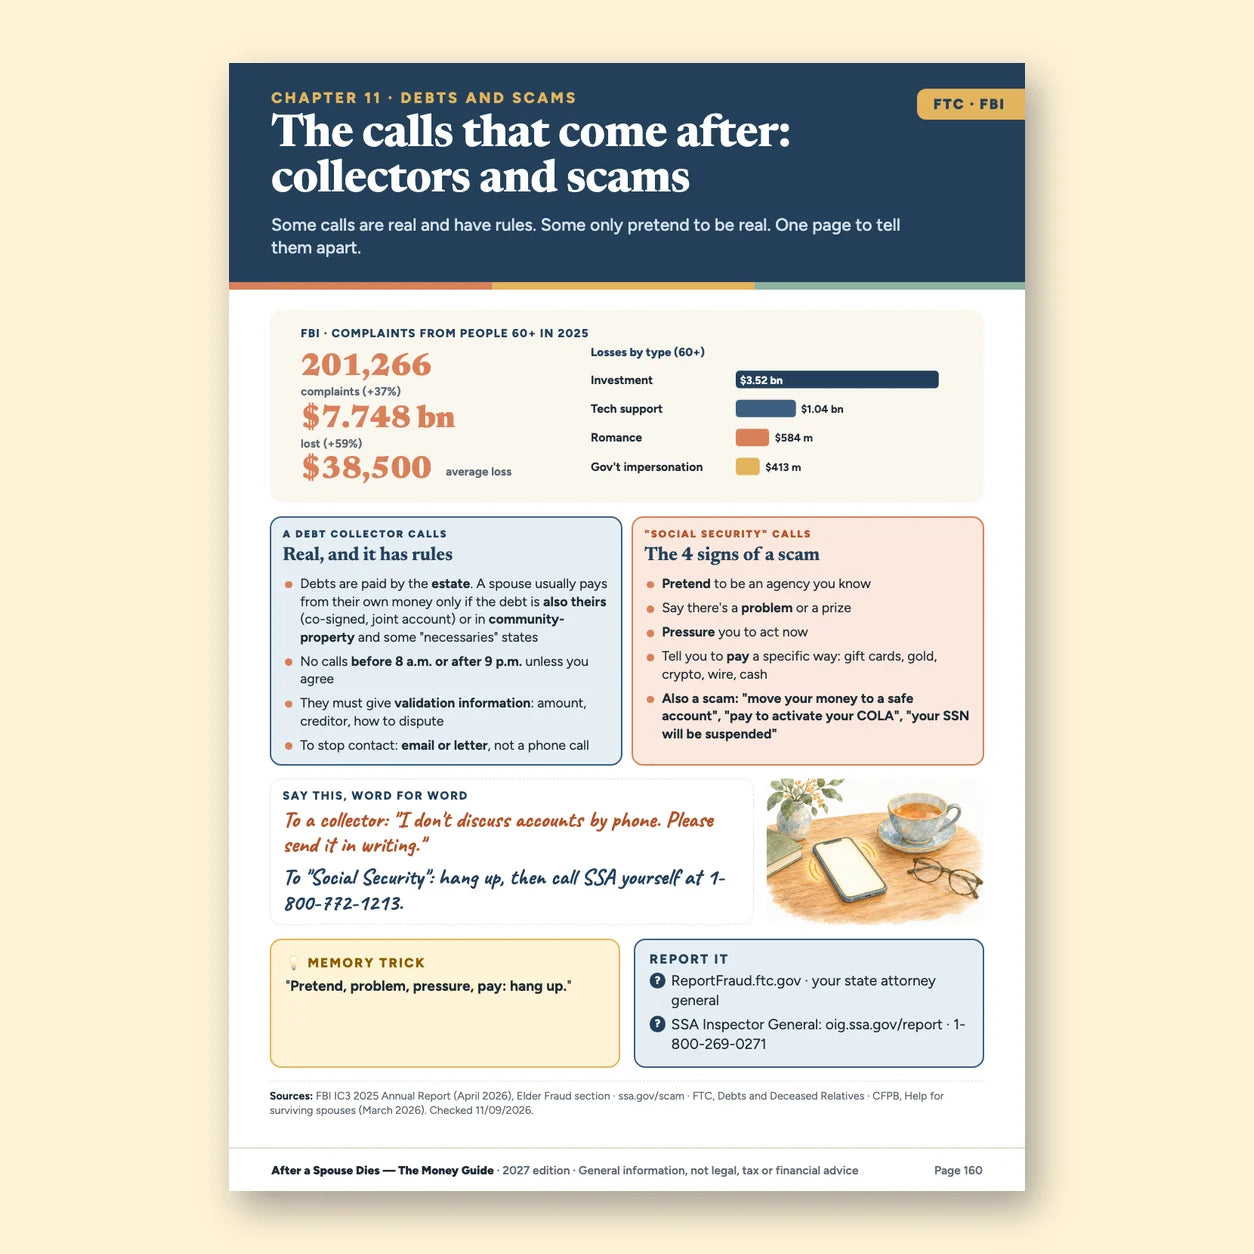
How is it different?
| What it has | This guide | Official websites | Books on Amazon | CPA or planner |
|---|---|---|---|---|
| Social Security, IRA, house, taxes and health in one place | ✓ | Spread across many agencies | Varies | Depends on the advisor |
| Charts, timelines and side-by-side choices | ✓ | Varies | Mostly text | — |
| 2026–2027 numbers with the source on each page | ✓ | ✓ | Varies by edition | ✓ |
| Questions to bring to SSA, the CPA and the plan | ✓ | — | Varies | — |
| Advice on your own situation | ✗ General information | ✗ | ✗ | ✓ |
| Price | From $39.99 | Free | About $10 to $25 | Fees vary |
You can start reading tonight.
You pay
Secure checkout, no account, no subscription. One payment.
You open the eBook
If you chose the eBook, the download link arrives by email. Open it on a phone, tablet or computer.
The book arrives
If you chose the printed book, it ships free to your U.S. address.
The money side of the first year, explained page by page.
- 200 illustrated color pages, 14 chapters
- The first 30 days, as a checklist
- Social Security survivor benefits, work and remarriage
- Pensions, VA, life insurance, the spouse's IRA and 401(k)
- The house, the mortgage and the 2-year window
- Taxes, health coverage, collectors and scams
- First-year budget and worksheets
- Printed book: spiral-bound, lies flat
What families ask before buying
Is this legal, tax or financial advice?
No. This guide provides general information, not legal, tax or financial advice, and it is not a substitute for an attorney, a CPA or a financial professional. Rules change and every situation is different. Each topic ends with the questions to bring to Social Security, a CPA, the plan administrator or an attorney.
Does it tell me exactly how much Social Security I'll get?
No. Only Social Security can calculate the amount, from both work records. The book explains how the percentages work by age, the widow's limit when a spouse claimed early, and the questions to ask SSA so you can compare the options.
Is it about the funeral and the first phone calls?
Only the money side. The first 30 days are covered as a money checklist (certificates, Social Security, the employer, the mortgage, insurance). Funeral arrangements are not the focus of this book.
Is it only for widows?
No. The rules are the same for widows and widowers, and the book is written so an adult son or daughter can follow it too.
Does it cover remarrying?
Yes. Remarriage before 60 (50 with a disability) usually stops the survivor benefit while the marriage lasts; at 60 or later it doesn't. From 62, a benefit on the new spouse's record may be higher. Taxes and the home-sale rule change with remarriage too, and the book flags where.
My spouse was a veteran. Is the VA covered?
Yes, at an introductory level: Dependency and Indemnity Compensation (DIC) rates from December 1, 2025, the extra amounts for children and the 8-year rule, plus where to search for VA life insurance. For a claim, accredited Veterans Service Organizations help for free.
Are you affiliated with Social Security, the IRS or Medicare?
No. We are not affiliated with or endorsed by the Social Security Administration, the IRS, CMS, the VA or any government agency. Applying for survivor benefits is free: Social Security takes claims by phone at 1-800-772-1213 or at a local office.
Can you look at our situation and tell us what to do?
No. We can't advise on individual cases. The book is built so you can bring the right pages and questions to Social Security, a CPA, a financial professional or an attorney.
Are the numbers up to date?
They were checked on November 9, 2026, against Social Security, the IRS, CMS, the Department of Labor, the VA and the CFPB, and each page shows its source. Some 2027 amounts (Medicare premiums, VA rates) are published later in the year, so the guide is reviewed every year.
Can I read it on my phone?
Yes. The eBook is a color PDF that opens on a phone, tablet or computer. You can print the checklists, the worksheets and any page you want.
When does the printed book arrive?
Shipping is free to U.S. addresses and takes about 5–8 business days. The eBook arrives by email right after payment.
What if it's not right for me?
You have a 30-day guarantee. Write to us within 30 days and we'll refund you. No questions, no forms.
Ready to see the money side, one page at a time?
200 illustrated pages, 2026–2027 numbers with sources, the first 30 days as a checklist. 30-day guarantee.
From $39.99 · eBook or printed