A divorce after 50 splits more than the house.
401(k)s, Social Security, taxes: page by page.
An illustrated guide to the rules that decide what each side really keeps: 401(k)s and pensions (the QDRO), IRAs, the house, Social Security on an ex-spouse's record, alimony taxes and health insurance until Medicare. 192 pages with 2026 numbers and official sources. eBook or printed book.
The book on the table, the PDF on the phone for meetings · $79.99
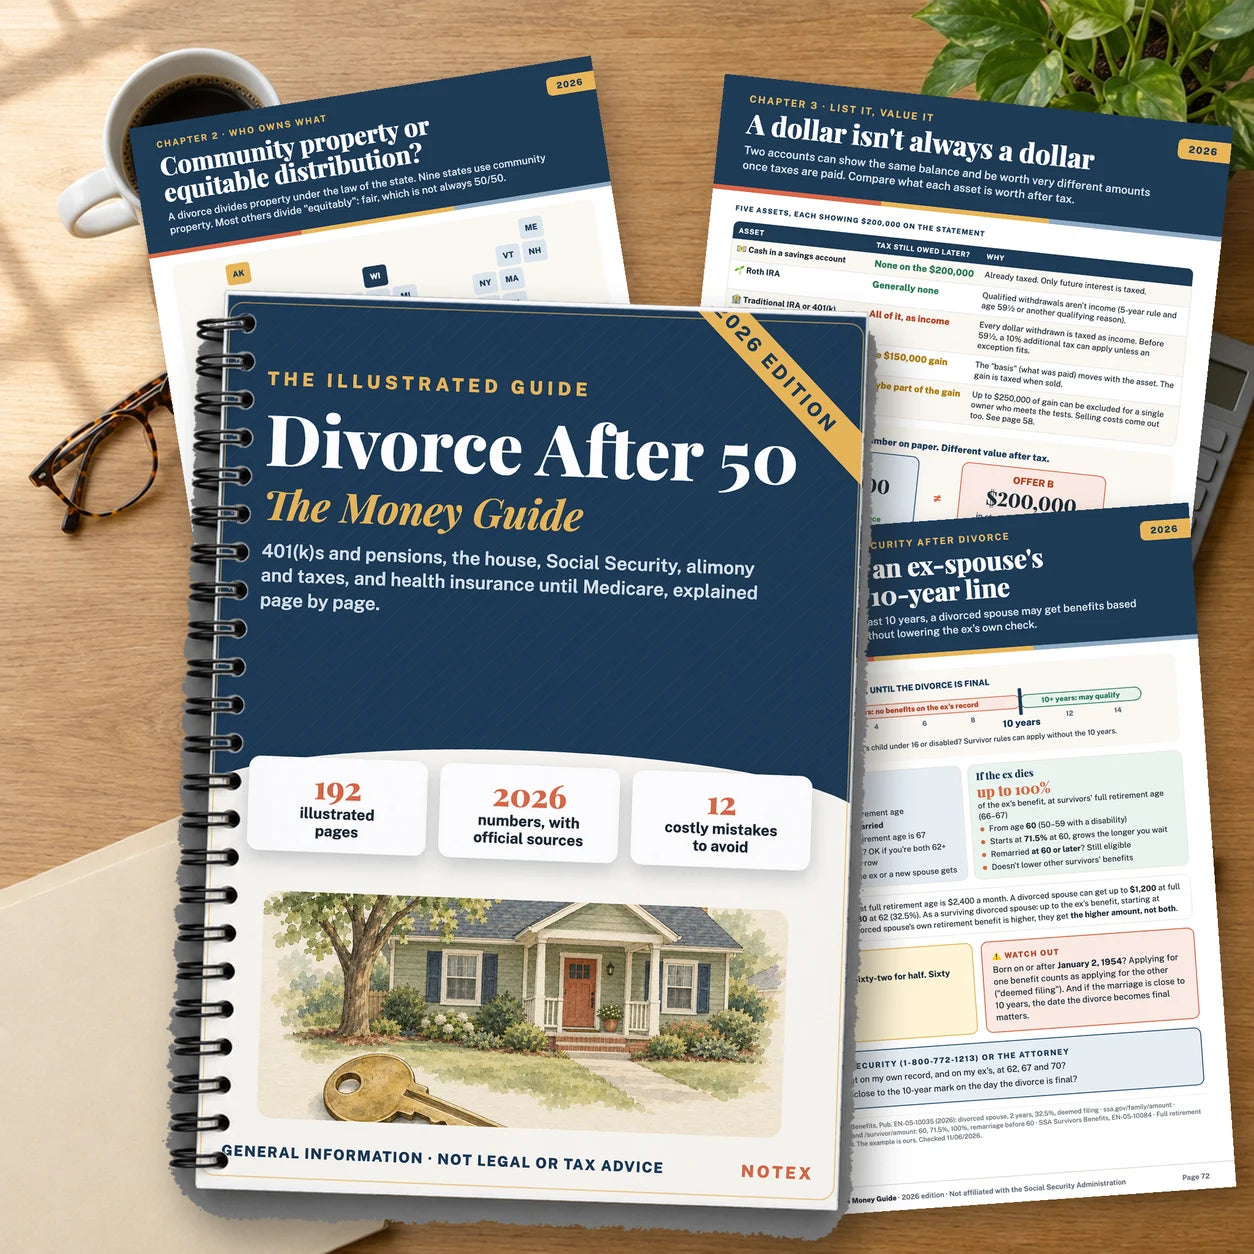
Not a wall of legal text. One topic per page.
Every page works the same way, so the answer is there in two minutes, before a call with the attorney or the plan.
This is what the pages look like.
For people navigating divorce after 50, and the family who helps.
Know the vocabulary
QDRO, basis, equitable distribution, deemed filing. Knowing the words before the first meeting makes every billed hour go further.
Compare offers after tax
Retirement accounts, investments and the house carry different taxes. The guide shows how to put them on the same line before anything is signed.
Finish the paperwork
The QDRO, IRA transfers, beneficiary forms, the COBRA notice, the new filing status, a budget for one household. The details that are easy to leave half done.
What's worth knowing before signing.
These rules are federal and written down. The book explains each one with a diagram, the 2026 numbers and the source.
Alimony changed in 2019
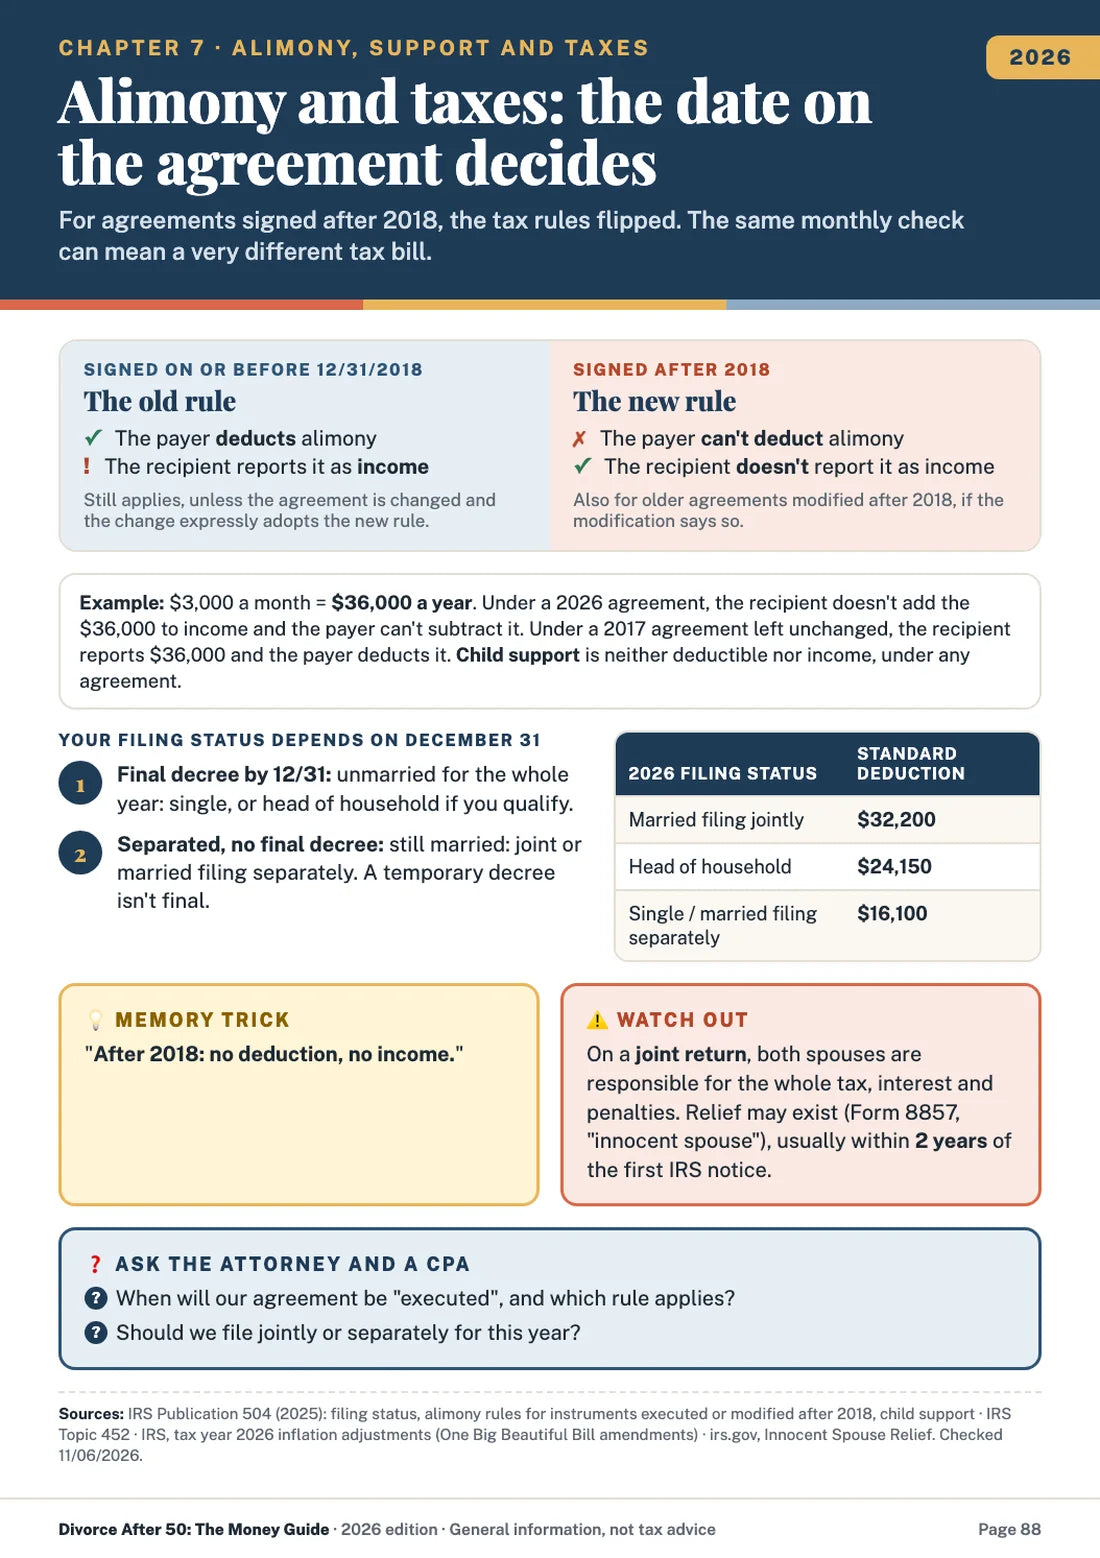
For agreements signed after 2018, the payer can't deduct alimony and the recipient doesn't report it as income. Older agreements keep the old rule unless they're changed to say otherwise.
The 10% exception has a limit
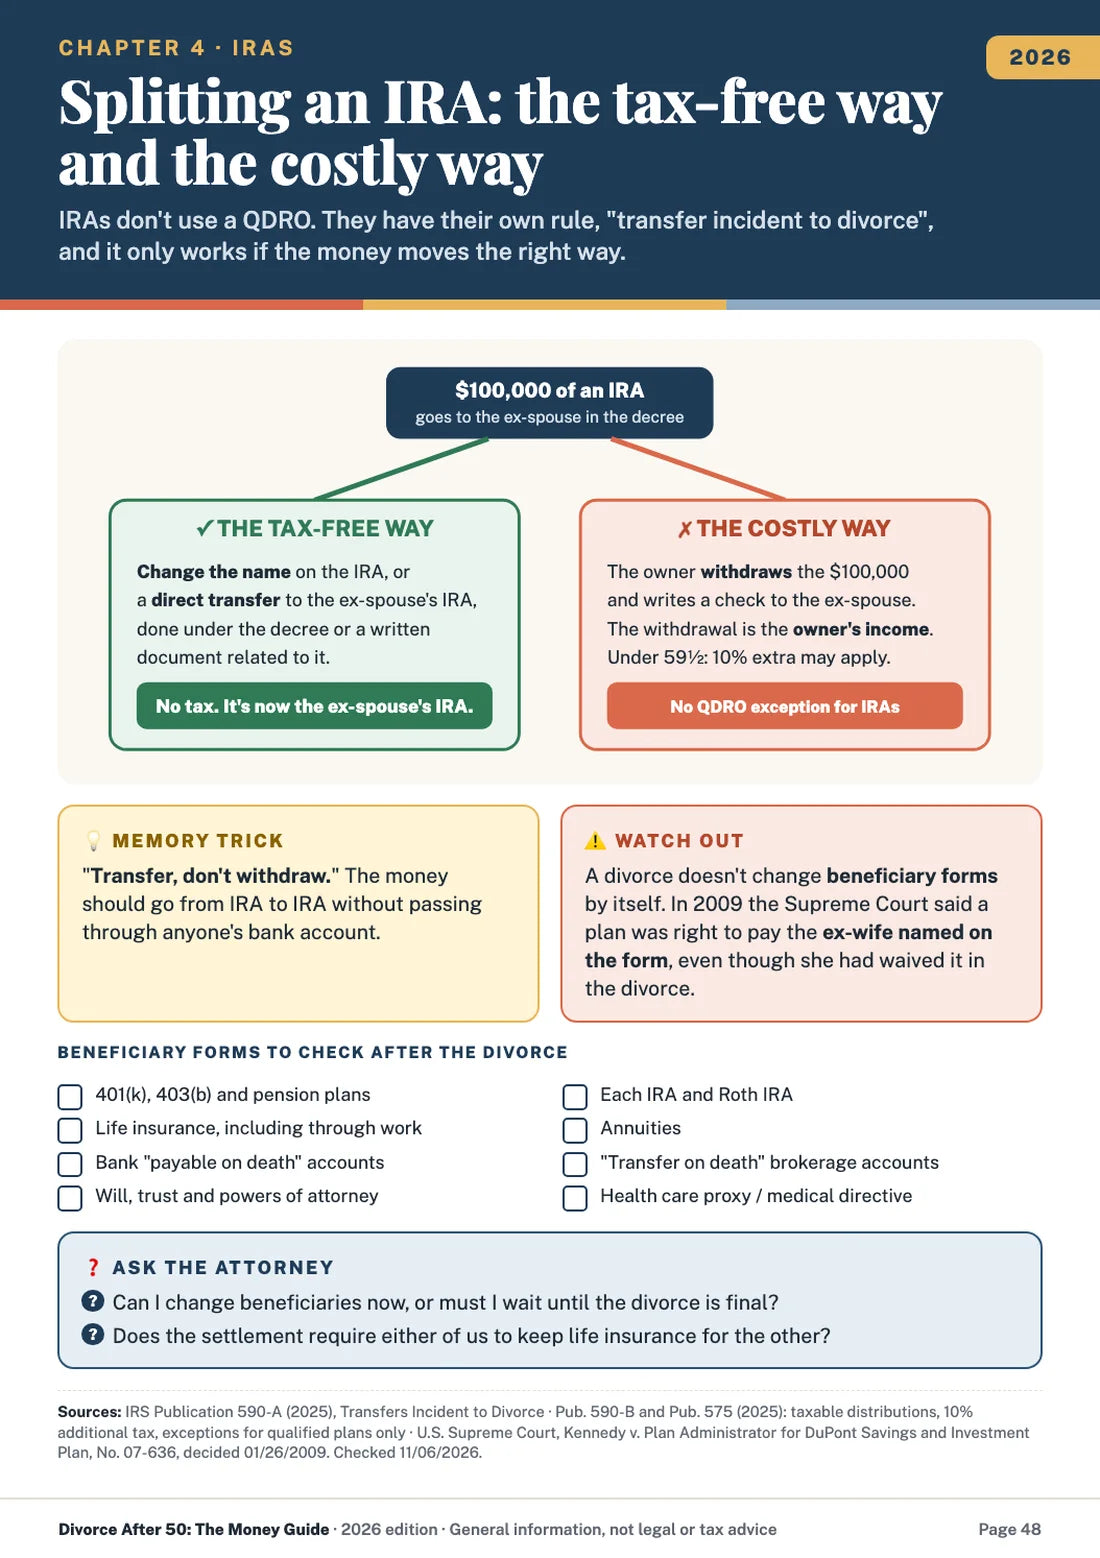
Money paid to a former spouse from a 401(k) under a QDRO avoids the 10% early-withdrawal tax. The same exception doesn't exist for IRAs.
The form on file can win
In 2009 the U.S. Supreme Court said a plan was right to pay the ex-wife named on the beneficiary form, even though she had waived the benefit in the divorce.
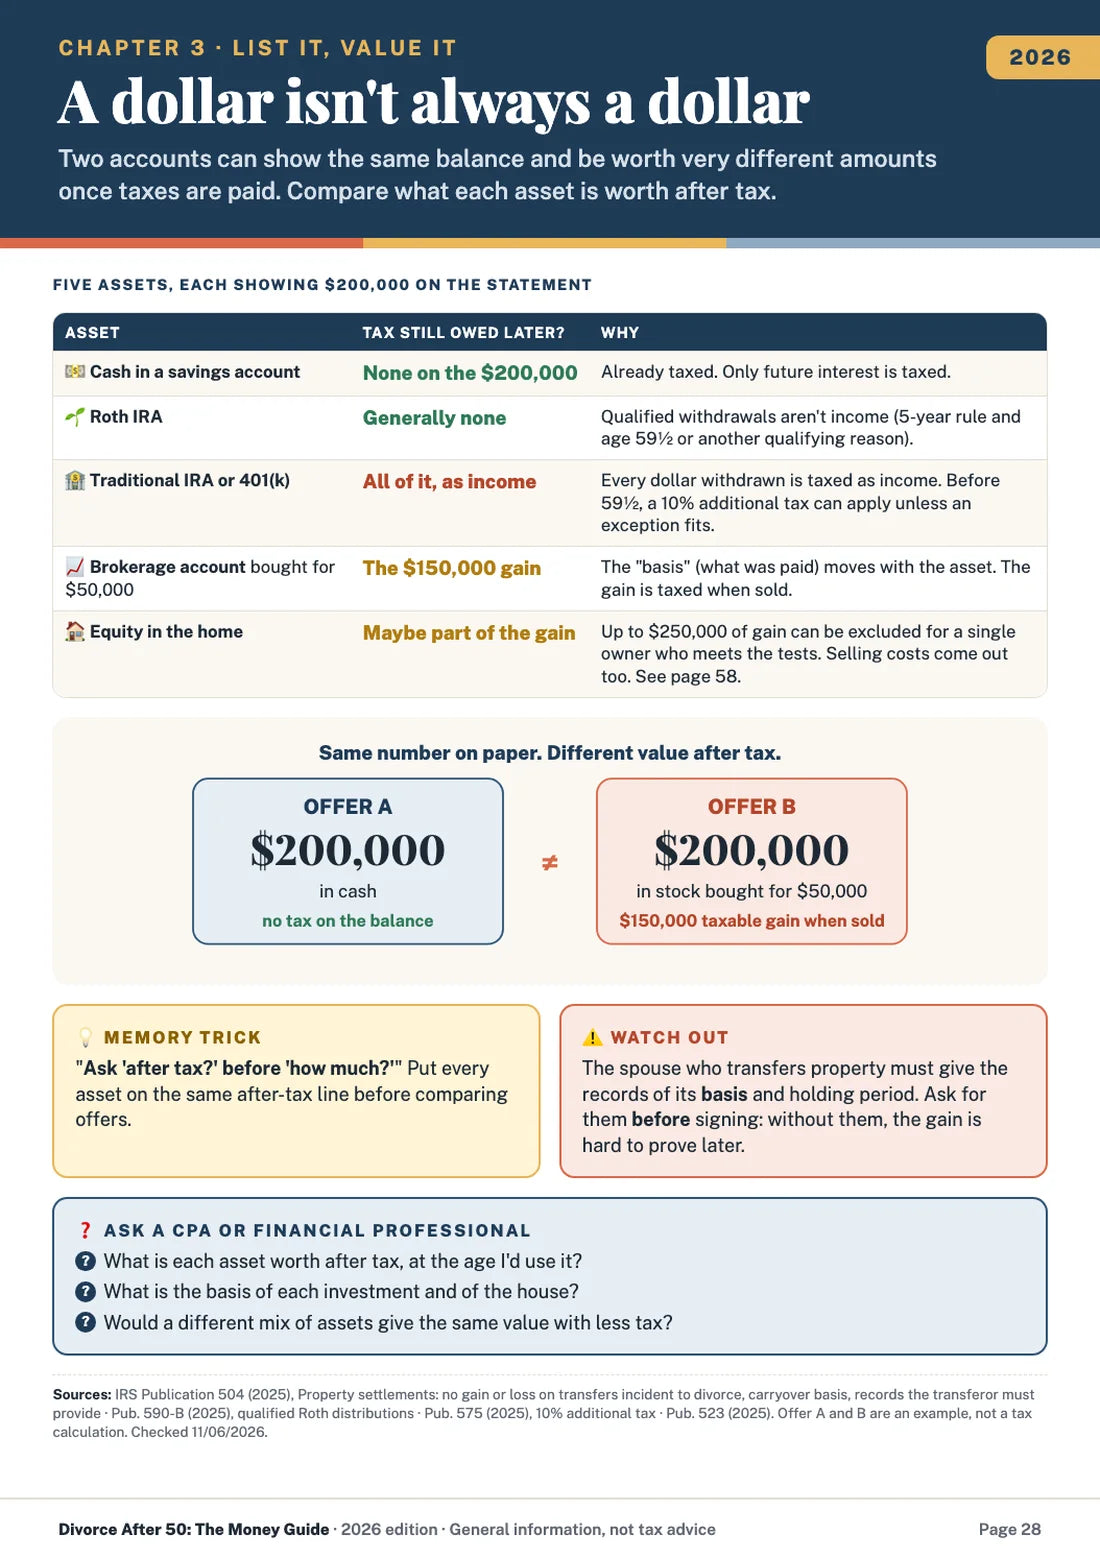
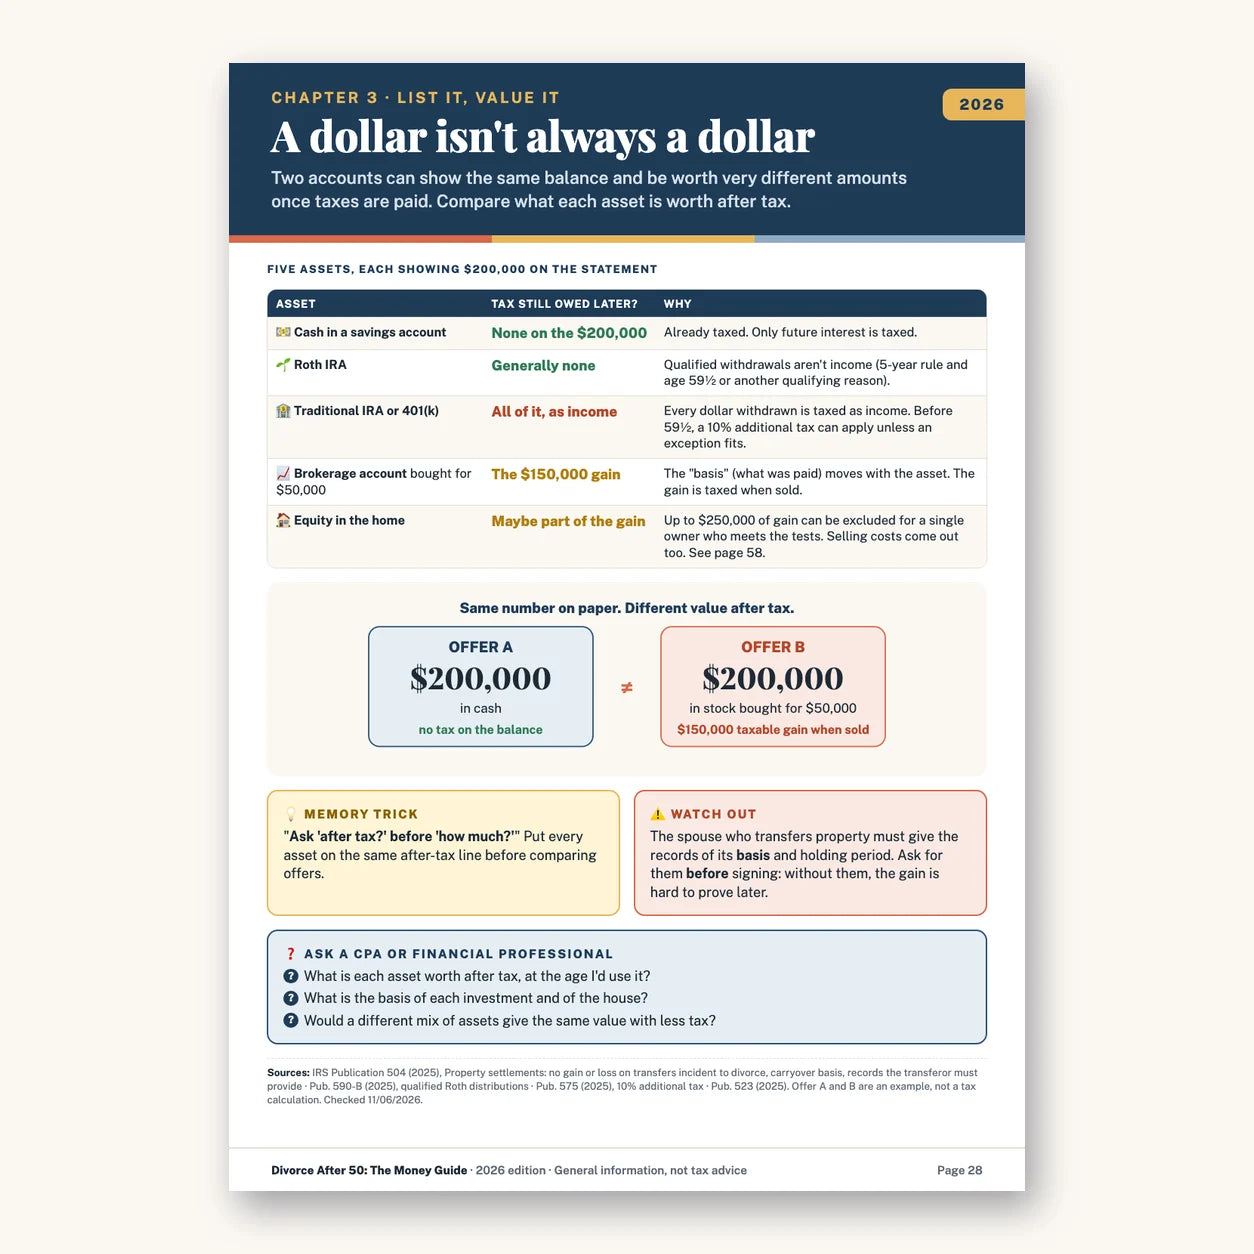
Same balance on paper, different value after tax.
Five kinds of assets, each showing $200,000, and what tax may still be owed on each one.
- Cash, Roth IRA, traditional IRA or 401(k), brokerage account, home equity
- Why the "basis" moves with the asset, and why the records matter
- Two offers that look equal and aren't
- The questions to ask a CPA before comparing offers
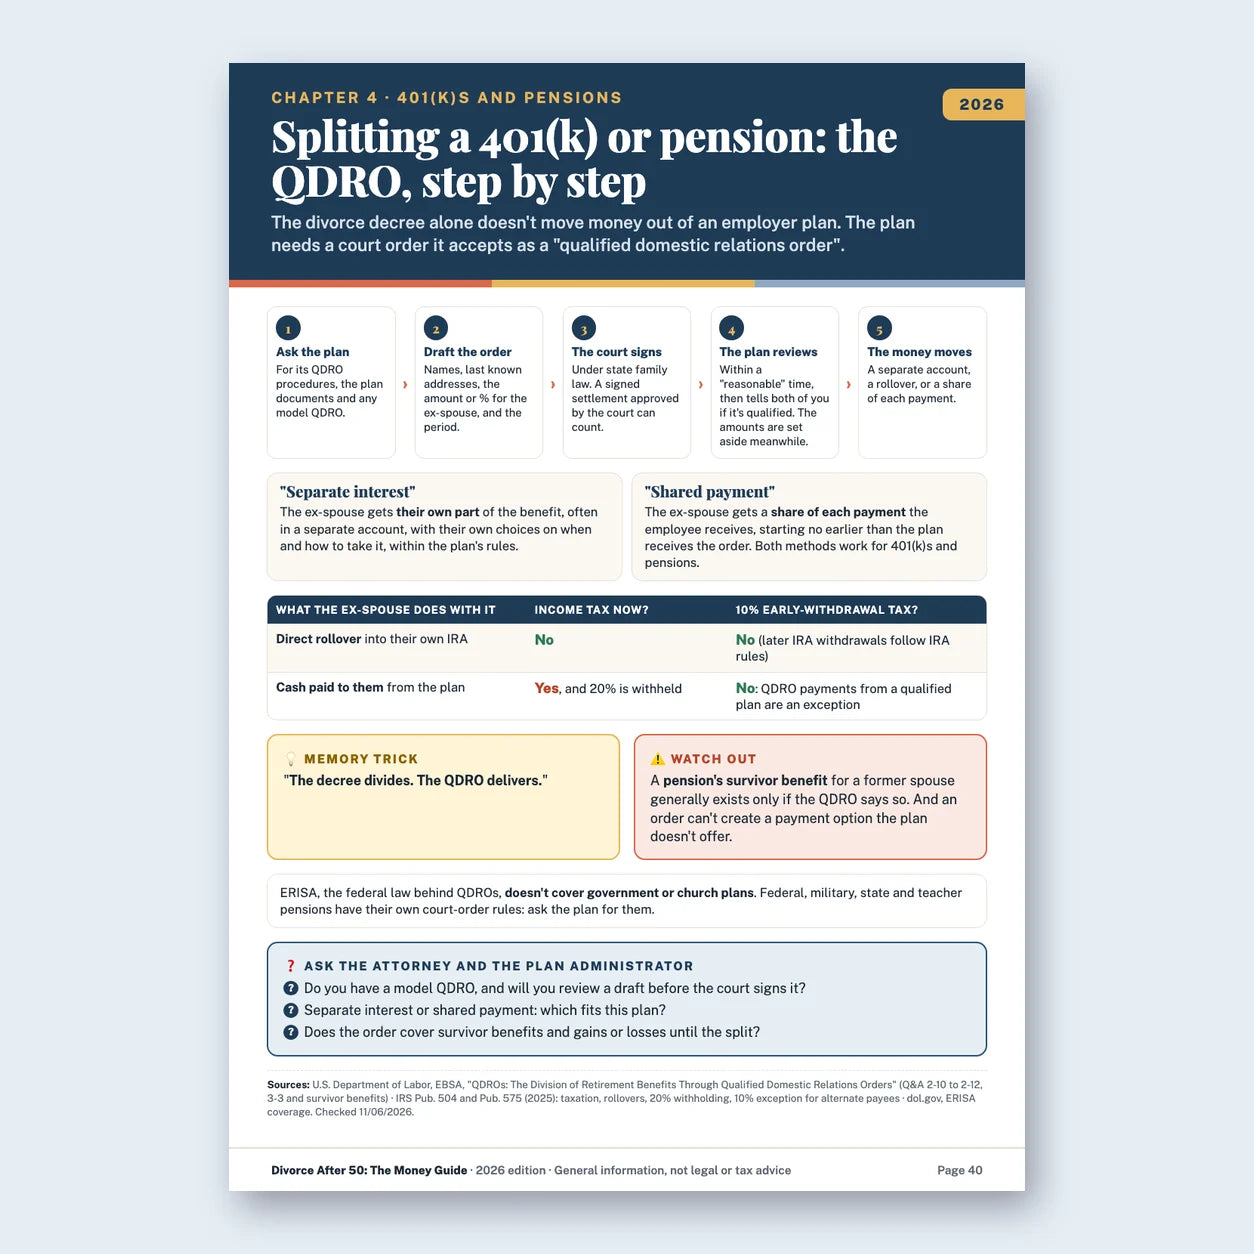
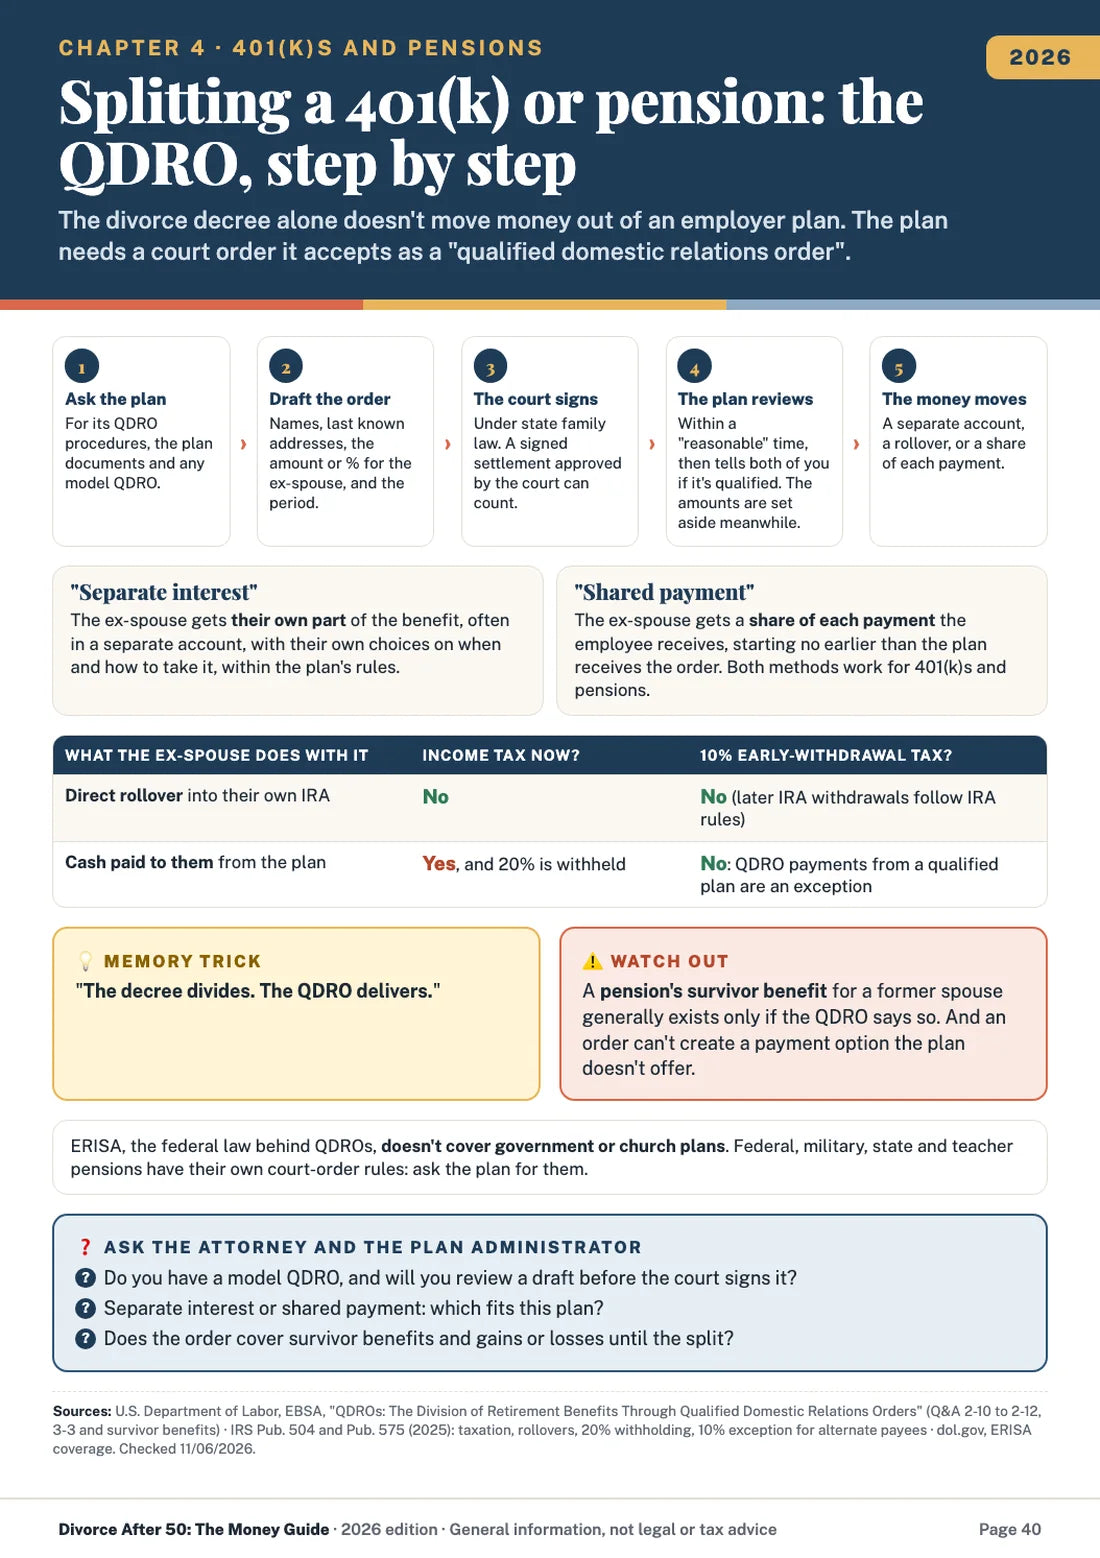
The QDRO in five steps, and the IRA rule next to it.
How an employer plan divides an account or a pension, and how an IRA moves tax-free.
- From the plan's procedures to the money moving: who does what
- "Separate interest" or "shared payment"
- Rollover, cash, 20% withholding and the 10% exception
- Survivor benefits for a former spouse, and government pensions
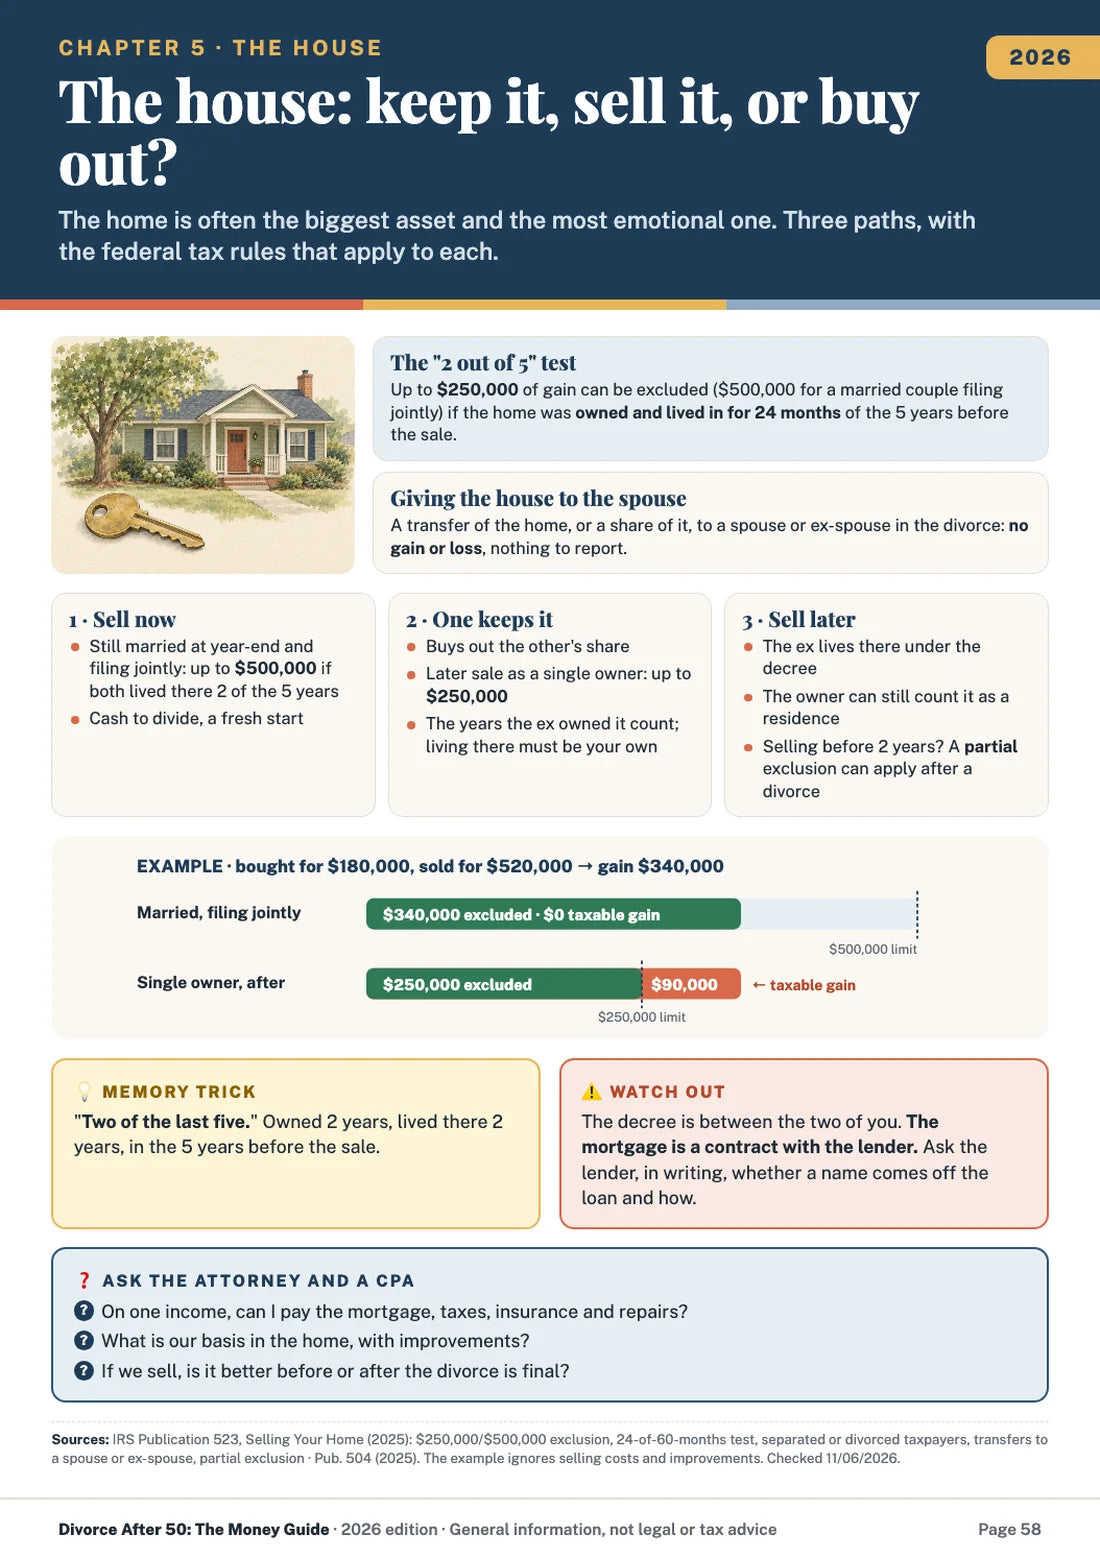
Keep it, sell it, or buy out.
The three paths, with the home-sale tax rules that apply to each, and a worked example.
- Up to $250,000 of gain excluded for a single owner, $500,000 for a couple filing jointly
- The "2 out of 5 years" test, and the years an ex-spouse's ownership counts
- Transfers between spouses in a divorce: no gain or loss
- The one-income budget for the house: mortgage, taxes, insurance, repairs
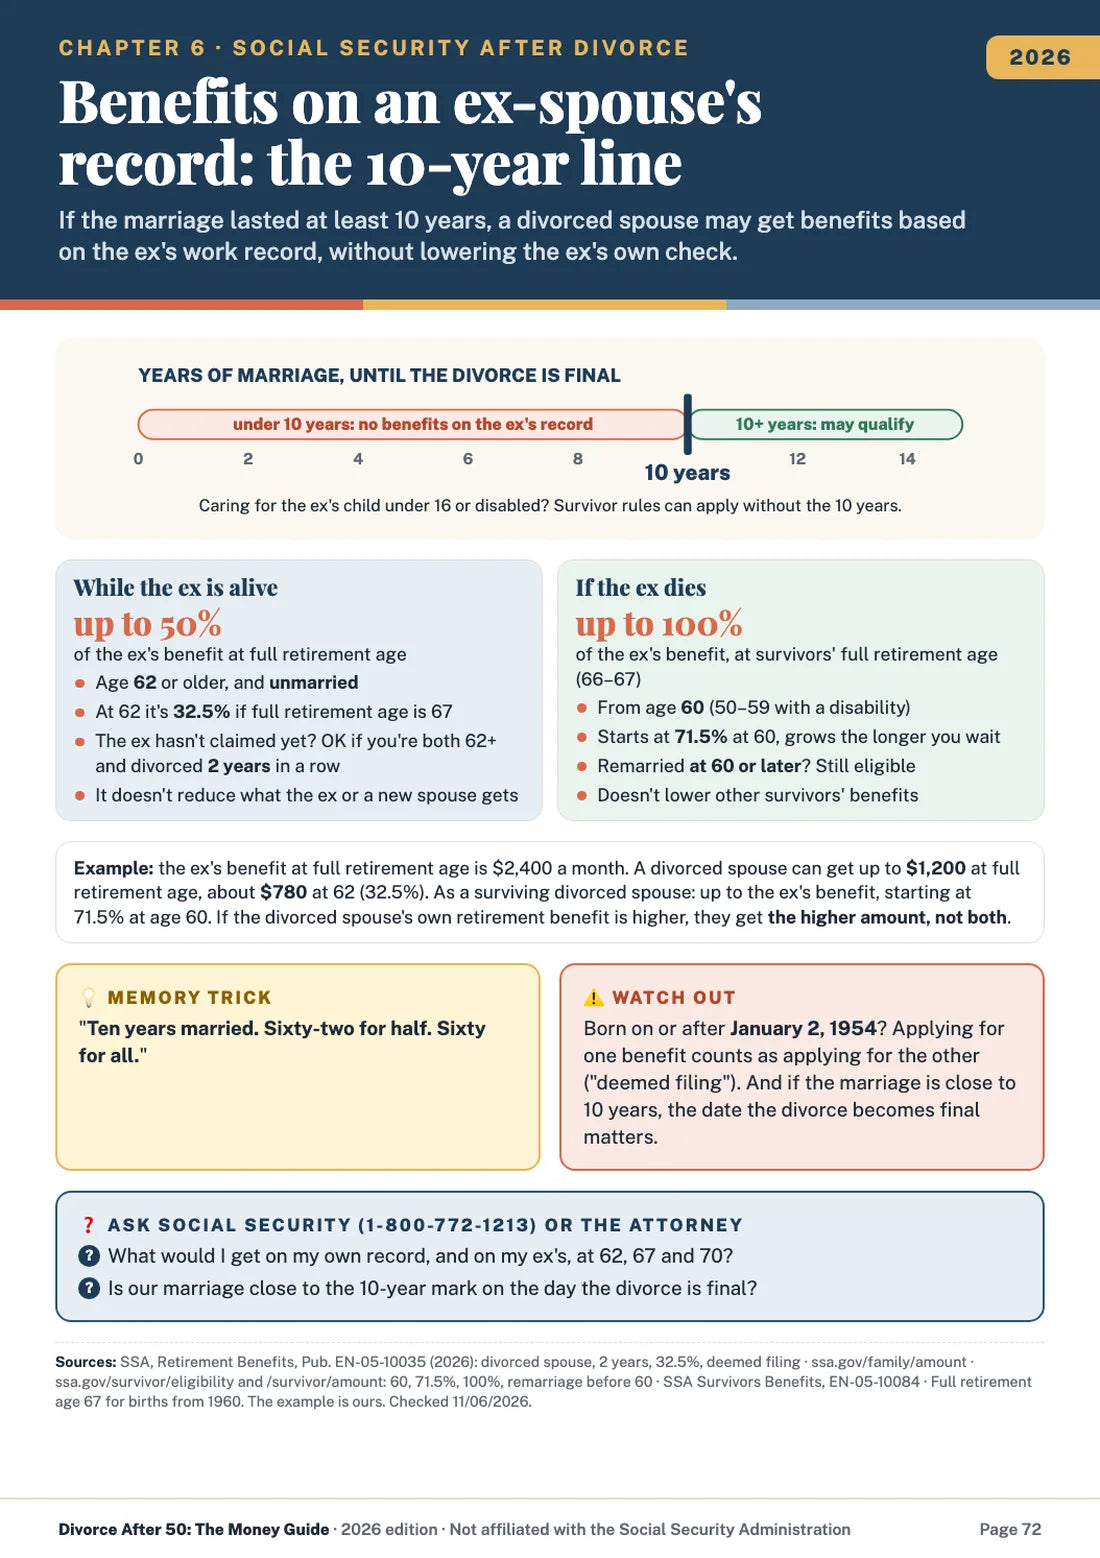
The 10-year line, on one page.
Benefits on an ex-spouse's record while the ex is alive, and survivor benefits after.
- Up to 50% of the ex's benefit at full retirement age, 32.5% at 62
- Divorced 2 years: no need to wait for the ex to claim
- Survivor benefits from 60, up to 100%; remarriage at 60 or later
- "Deemed filing" for people born on or after January 2, 1954
The date on the agreement decides the tax.
The old rule and the new rule side by side, the December 31 filing-status rule, and the 2026 standard deductions.
- Agreements signed after 2018: no deduction, no income
- Single, head of household or still married on December 31
- 2026 standard deduction: $16,100 single, $24,150 head of household
- Joint returns, and "innocent spouse" relief
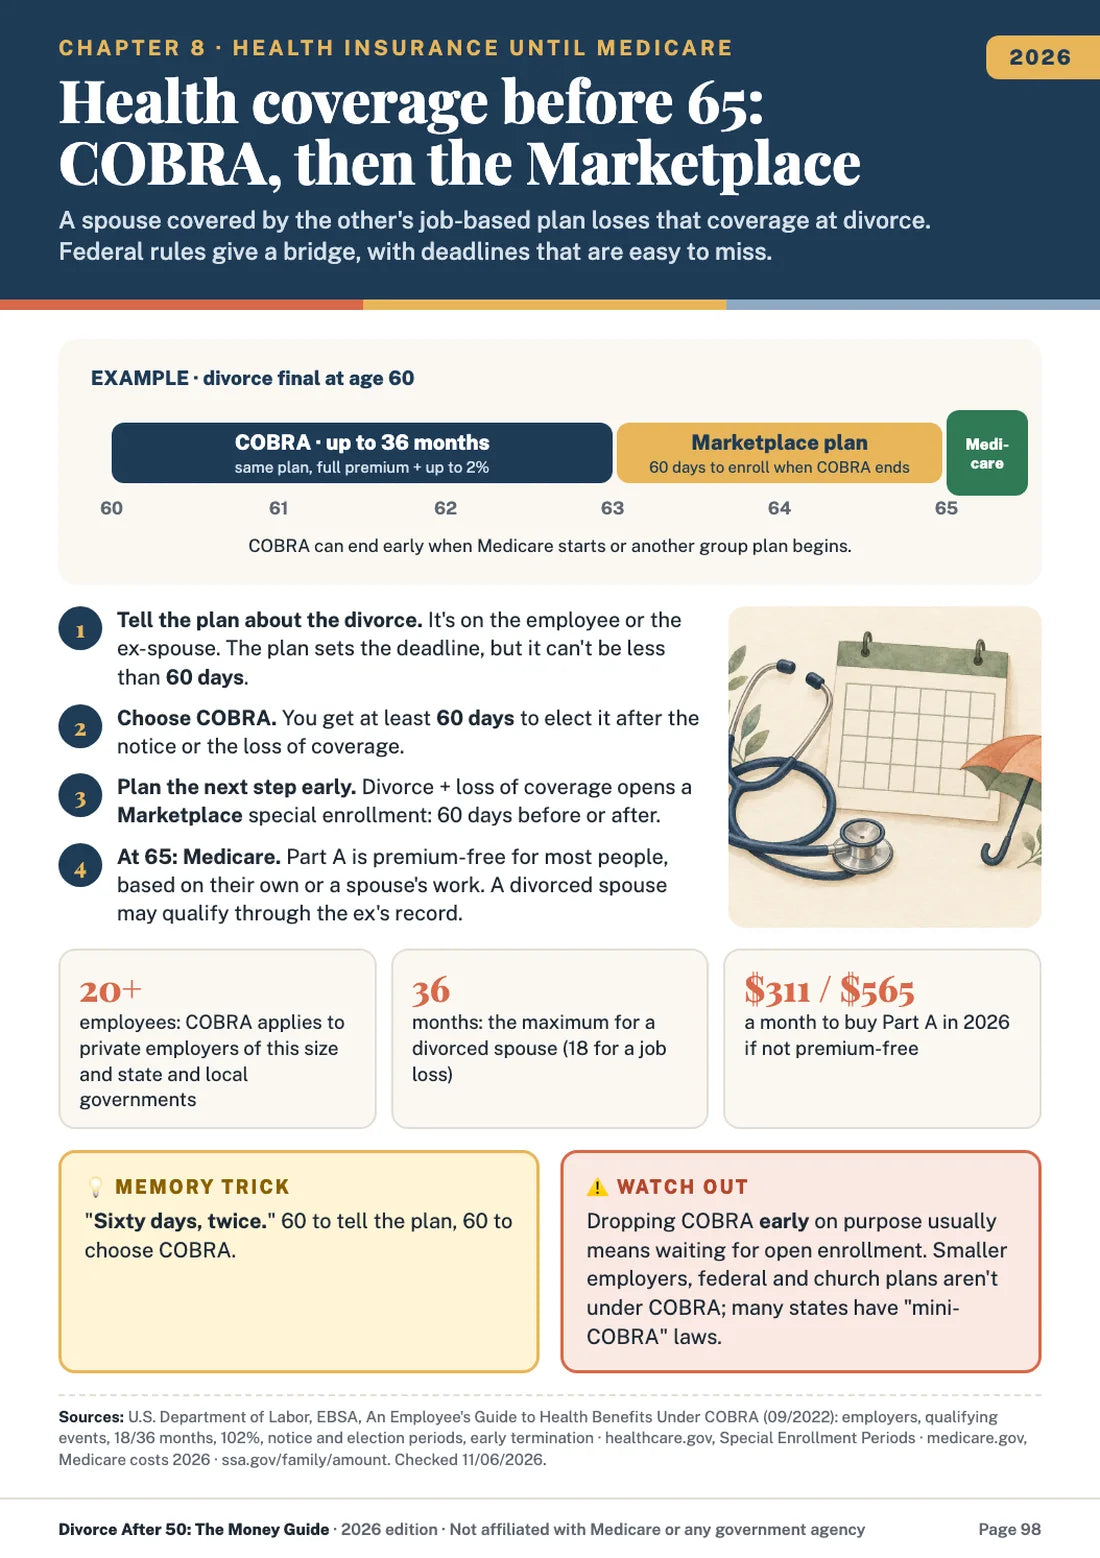
From the divorce to 65: the coverage timeline.
COBRA for a divorced spouse, the deadlines, then a Marketplace plan and Medicare.
- Up to 36 months of COBRA for a divorced spouse
- The notice to the plan: at least 60 days, and who has to send it
- Marketplace special enrollment: what qualifies and what doesn't
- Medicare Part A based on a spouse's or ex-spouse's work
Calm, clear, and ready for the next meeting.
No blame and no war stories. Just the rules, the numbers and the questions, so decisions are made with the facts on the table.
- Built on IRS publications, Department of Labor guides and SSA pages, cited on every page
- Reviewed every year: the numbers change every year
- We don't sell investments, insurance or legal services
The whole money side, in one guide.
Full table of contents
On screen, on paper, or both.
Color PDF, right after payment
Open it on a phone, tablet or computer. Print the checklists and worksheets as many times as needed.
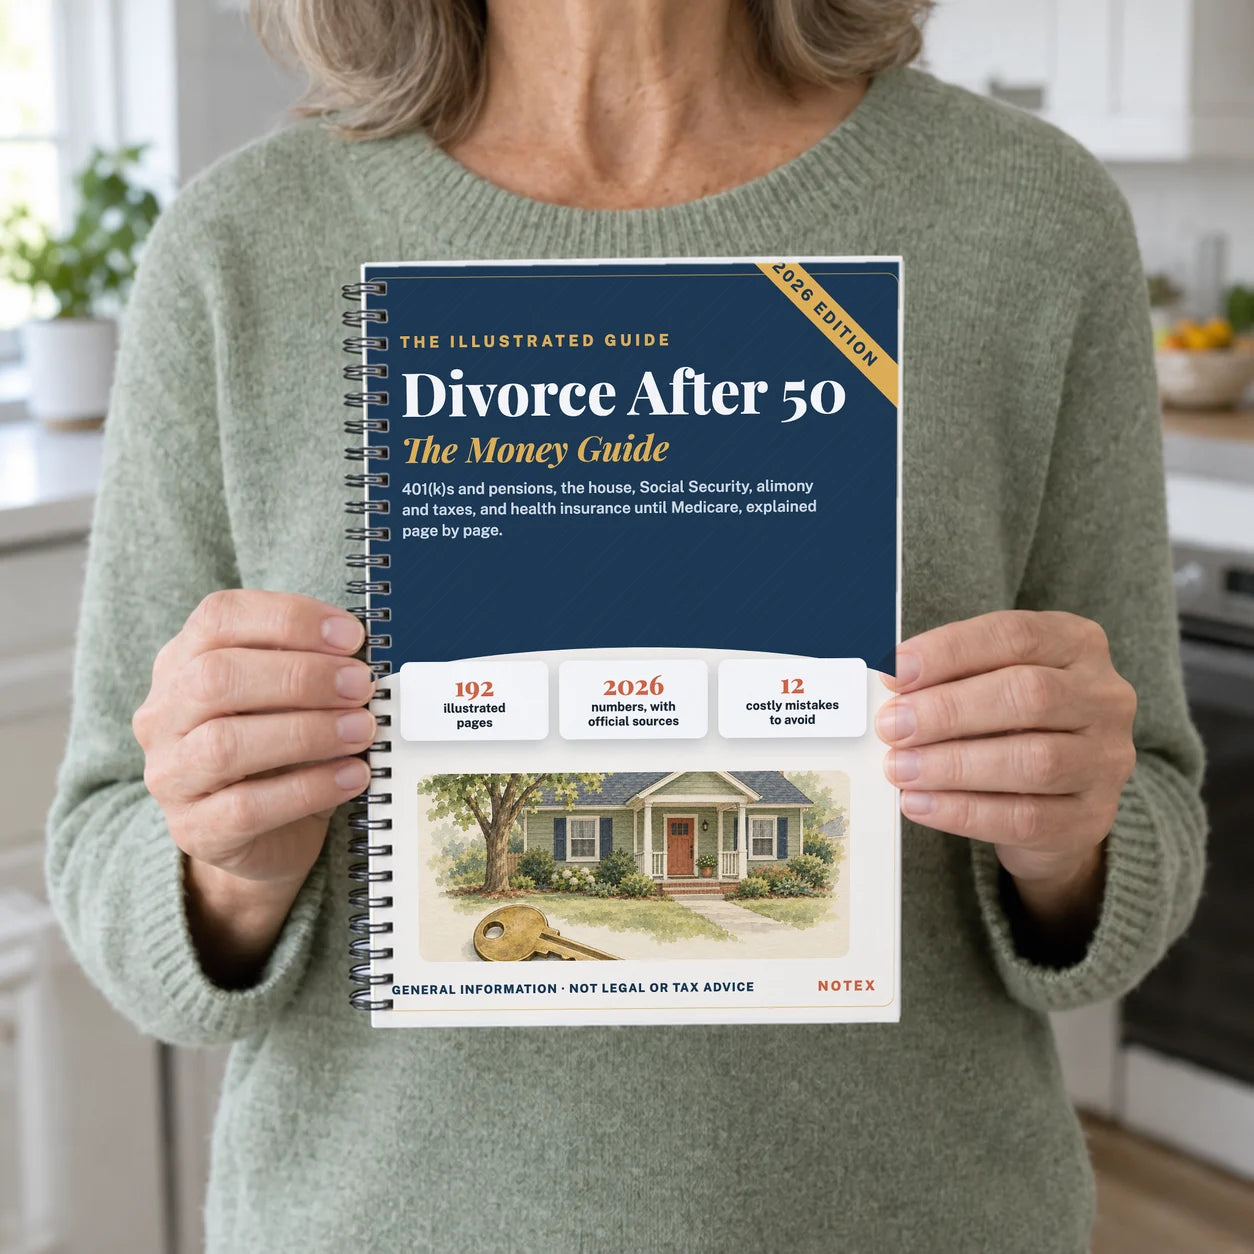
192 color pages, spiral-bound
Lies flat next to the statements. Free US shipping, about 5–8 business days. Want both? Printed + eBook for $79.99.
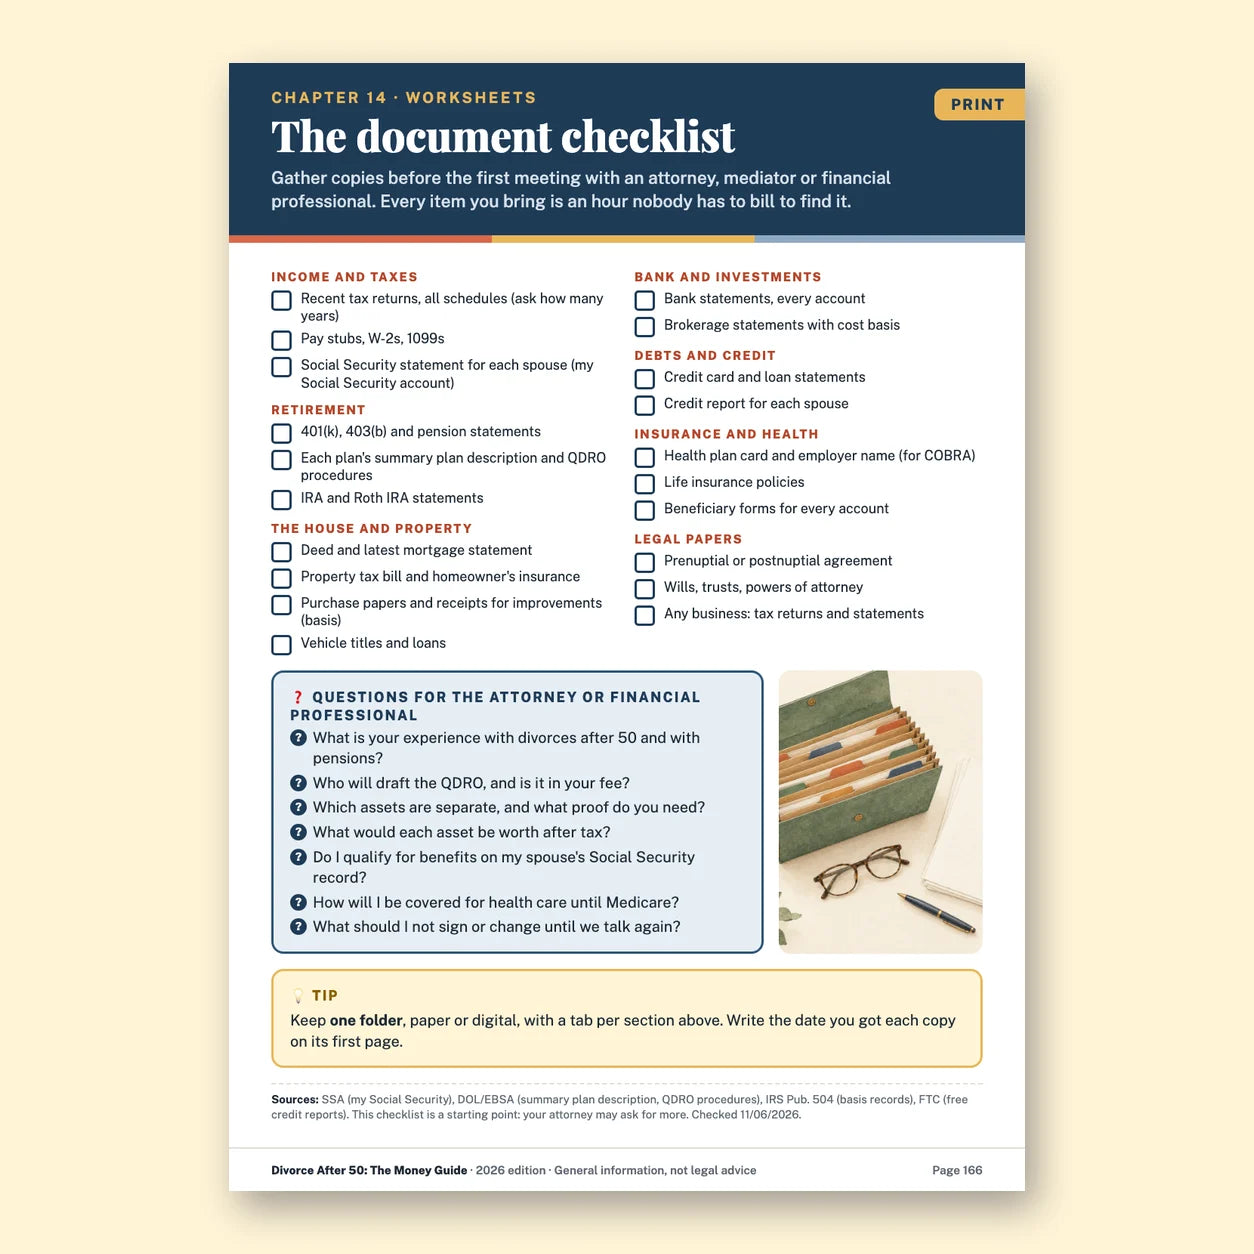
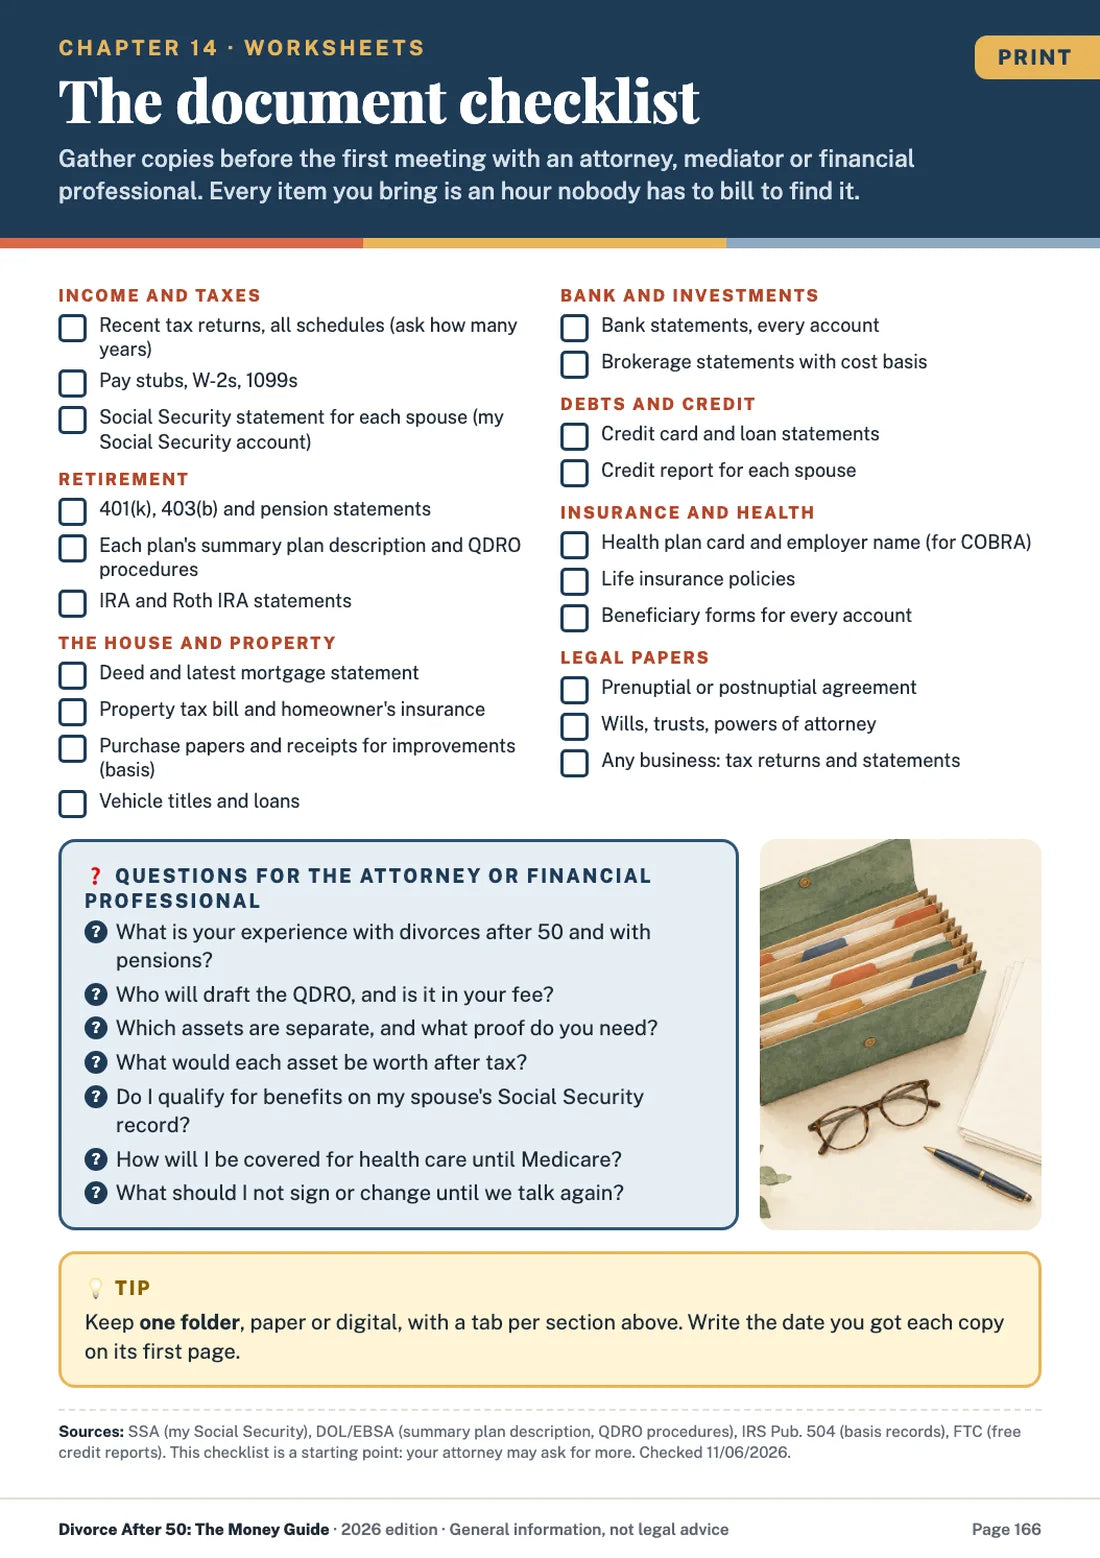
The checklists and worksheets.
The documents to gather before the first meeting, the questions to ask, and the worksheets to see the numbers clearly.
- Document checklist in 7 sections, from tax returns to beneficiary forms
- Asset list with an after-tax column, and a one-household budget
- With the eBook: print them again whenever needed
See 10 real pages, free.
Community property, the after-tax comparison, the QDRO, the IRA transfer, the house, Social Security, alimony taxes, health coverage before 65, the 12 costly mistakes and the document checklist. Read them and decide with the pages in front of you.
See the 10 pages ↓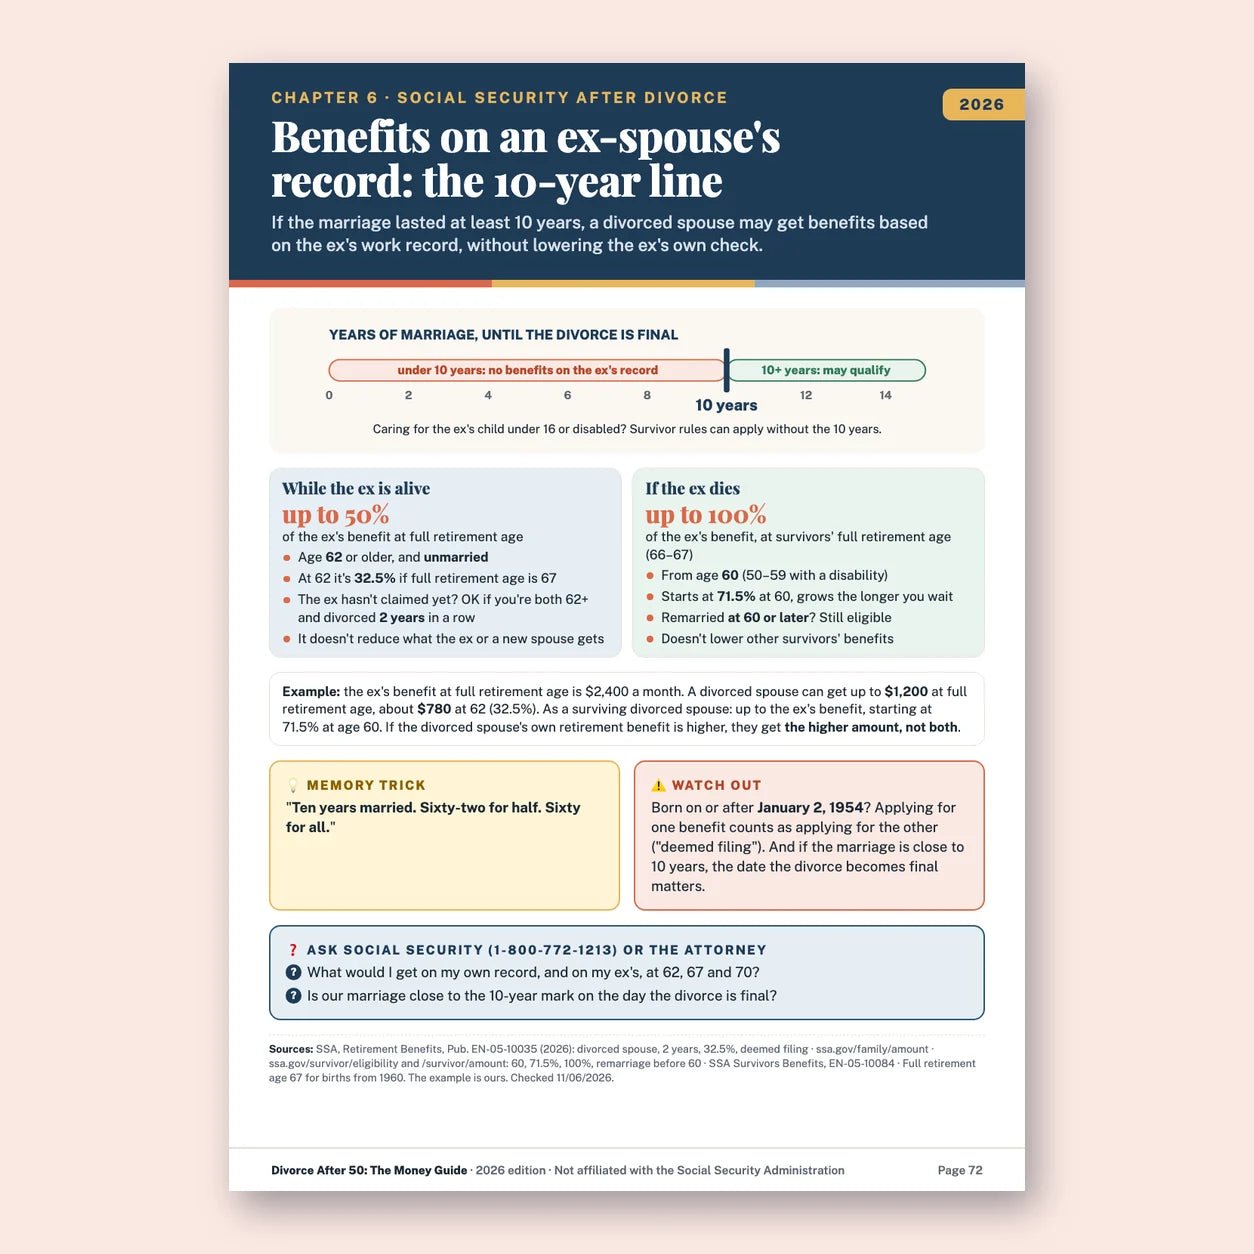
How is it different?
| What it has | This guide | Official websites | Books on Amazon | Attorney or financial professional |
|---|---|---|---|---|
| Property, retirement, the house, Social Security, taxes and health insurance in one place | ✓ | Spread across the IRS, DOL, SSA and more | Varies | ✓ |
| Flowcharts, timelines and side-by-side tables | ✓ | Varies | Mostly text | — |
| 2026 numbers with the source on each page | ✓ | ✓ | Varies; one well-known guide dates from 2019 | ✓ |
| Checklists and questions to bring to meetings | ✓ | — | Varies | — |
| Advice on one's own situation | ✗ General information | ✗ | ✗ | ✓ |
| Price | From $39.99 | Free | About $10 to $30 | Fees vary |
Reading can start tonight.
Pay once
Secure checkout, no account, no subscription. One payment.
Open the eBook
With the eBook, the download link arrives by email. It opens on a phone, tablet or computer.
The book arrives
With the printed book, shipping to US addresses is free.
The money side of divorce after 50, explained clearly.
- 192 illustrated color pages, 15 chapters
- Property, 401(k)s and pensions, IRAs, the house, Social Security, alimony, health insurance, debts
- The QDRO and the IRA transfer, explained with diagrams
- 2026 rules and amounts, each with its official source
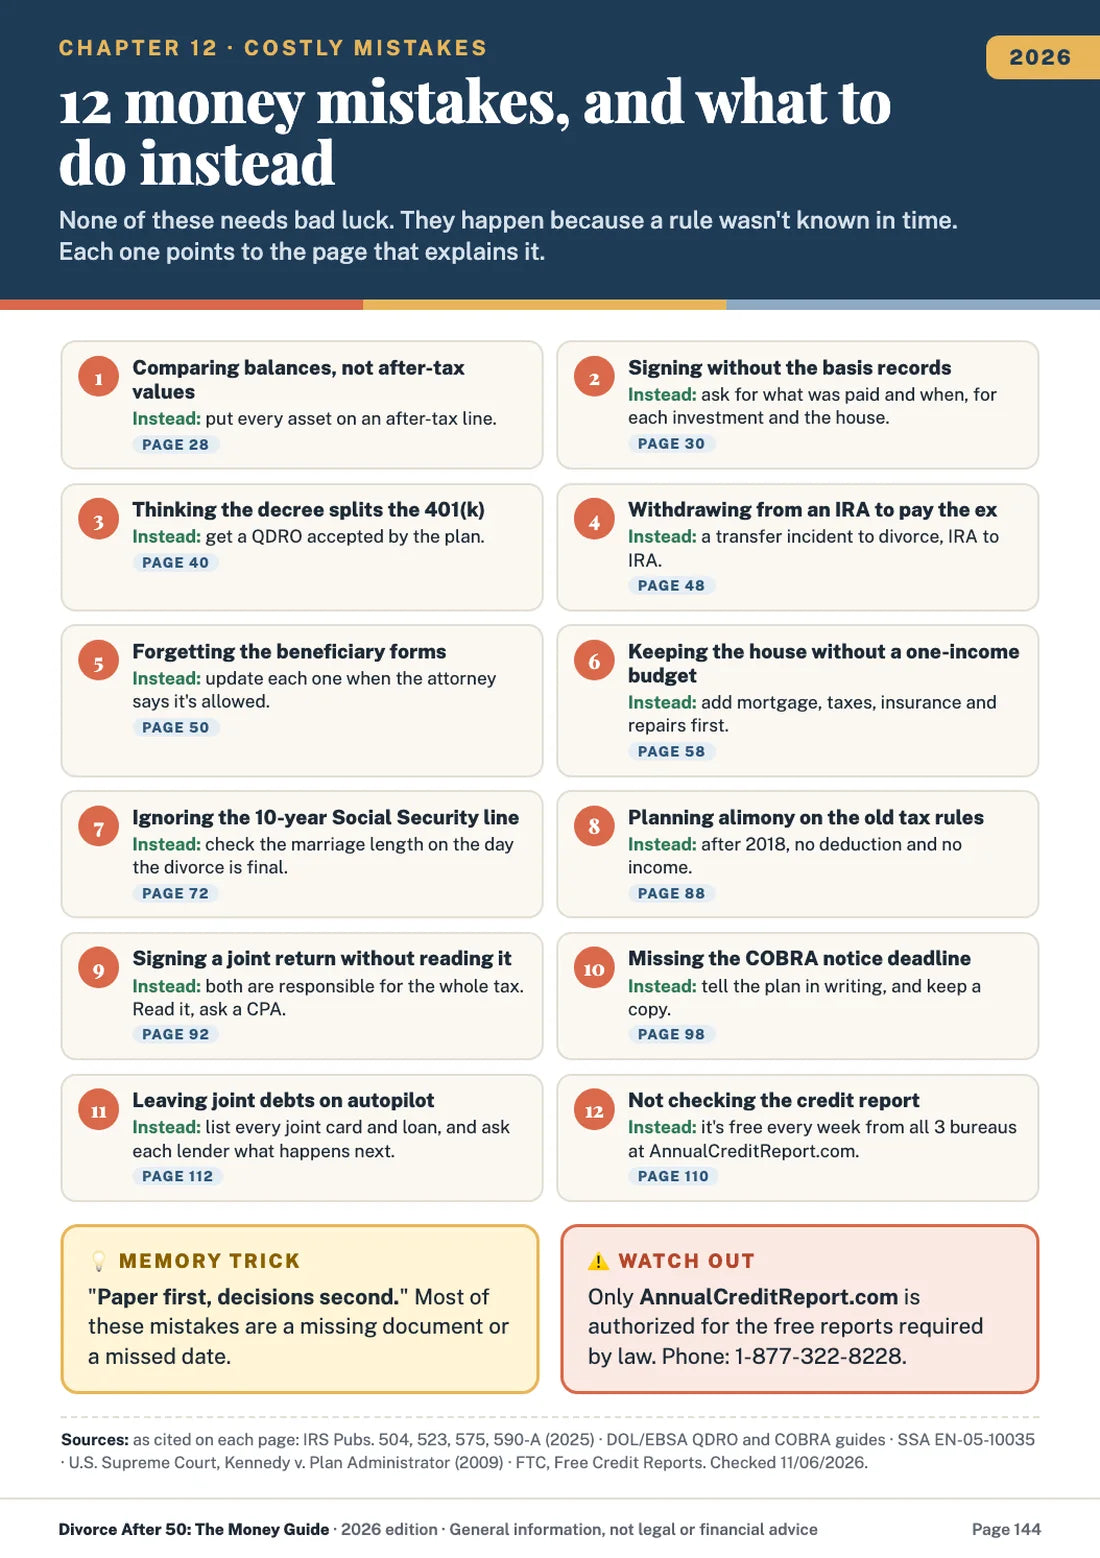
- 12 costly mistakes, with what to do instead
- Document checklist, questions for meetings, one-household budget
- Printed book: spiral-bound, lies flat, free US shipping
Questions people ask before buying
Is this legal, tax or financial advice?
No. This guide provides general information, not legal, tax, or financial advice, and it is not a substitute for an attorney, a CPA or a financial professional. Divorce law is state law and every situation is different. Every topic in the book ends with the questions to bring to a professional in your state.
Which states does it cover?
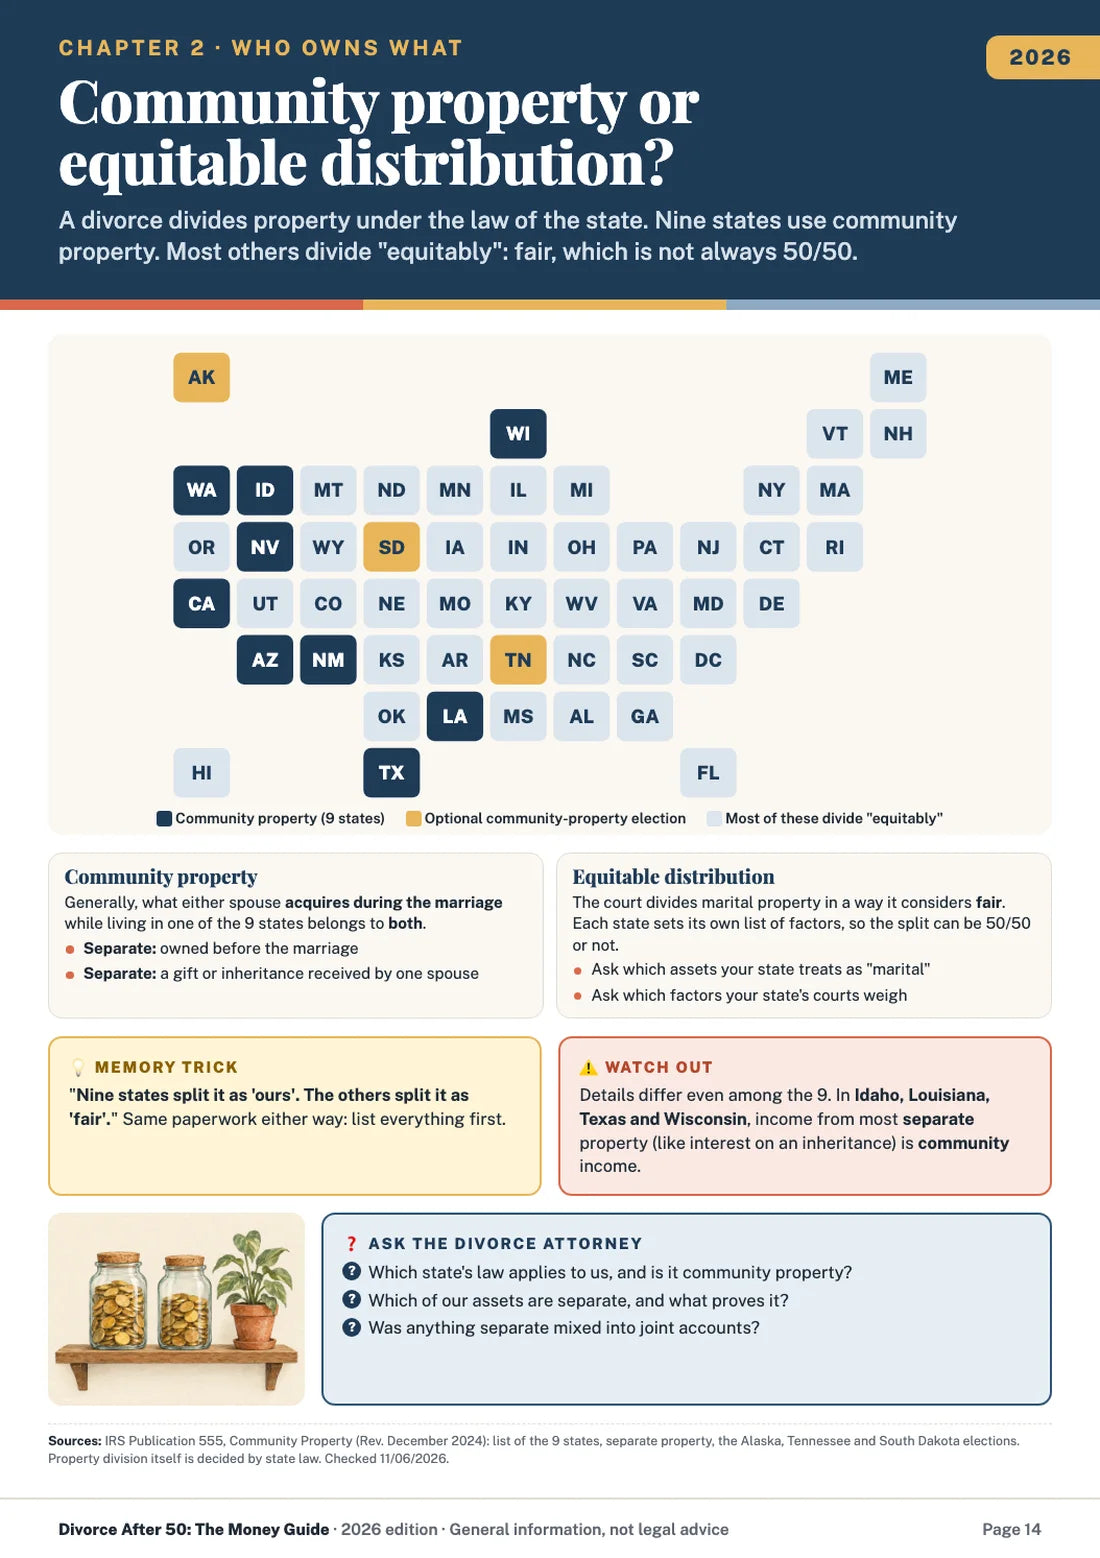
All of them, at the level of the federal rules that apply everywhere: IRS tax rules, QDROs under federal law, Social Security, COBRA and Medicare. For property division, the book explains the difference between the 9 community-property states and the "equitable distribution" approach most other states use, and what to ask about your own state.
Is it only for women?
No. It's written for anyone 50 or older going through the money side of a divorce, and for the adult children, siblings and friends who help. The rules are the same for everyone.
Does it explain how to split a 401(k) or a pension?
Yes. A full chapter on QDROs for employer plans (the steps, the two ways to divide, taxes, the 10% exception and survivor benefits) and on IRA transfers incident to divorce. Government, military and church plans follow their own rules: the book explains this and what to ask the plan.
Does it cover Social Security for a divorced spouse?
Yes: the 10-year marriage rule, the age-62 and remarriage conditions, how much a divorced spouse can get, survivor benefits after an ex-spouse dies, and "deemed filing", with examples.
Are you affiliated with the IRS, Social Security or any agency?
No. We are not affiliated with or endorsed by the IRS, the Social Security Administration, the Department of Labor, Medicare or any government agency.
Are the numbers up to date?
The 2026 figures were checked on November 6, 2026 against official sources such as irs.gov, dol.gov, ssa.gov, healthcare.gov and medicare.gov, and each page shows its source. Amounts change every year, so we review the guide every year.
Can you look at a specific case and say what to do?
No. We can't advise on individual cases. The book is built so the right pages and questions can be brought to an attorney, a mediator, a CPA or a financial professional.
Do you sell financial products or get referral fees?
No. We sell the guide only. We don't sell investments, insurance or legal services, and we don't receive referral fees.
Can I read it on my phone?
Yes. The eBook is a color PDF that opens on a phone, tablet or computer. The checklists and any page can be printed.
When does the printed book arrive?
Shipping to US addresses is free and takes about 5–8 business days. The eBook arrives by email right after payment.
What if it's not right for me?
There's a 30-day guarantee. Write to us within 30 days and we'll refund you. No questions, no forms.
Ready to see the money side clearly, one page at a time?
192 illustrated pages, 2026 rules with sources, checklists to print. 30-day guarantee.
From $39.99 · eBook or printed