62, 67 or 70?
See what each age changes.
An illustrated guide to Social Security claiming rules: full retirement age, spousal and survivor benefits, divorce, working, taxes and Medicare. 176 pages with the 2027 numbers and their official sources, plus worksheets to compare ages as a couple. eBook or printed book.
The book on the table, the PDF on both phones · $79.99

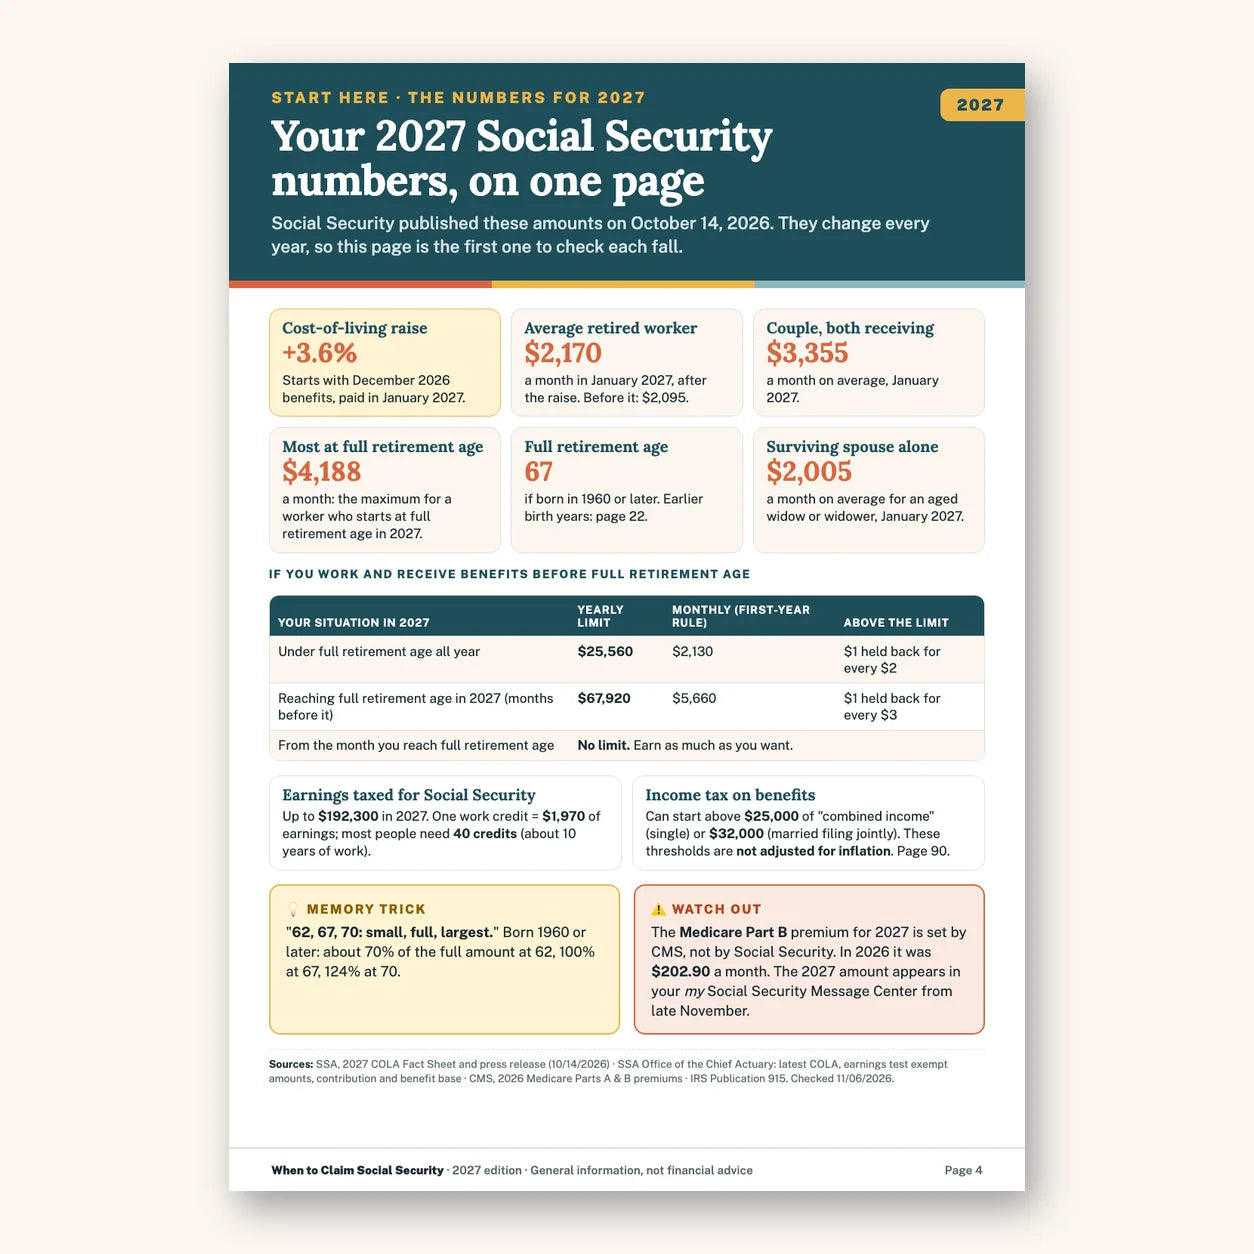
Not a wall of rules. One topic per page.
Every page works the same way, so a couple can sit down with their Statements and find the answer at the kitchen table.
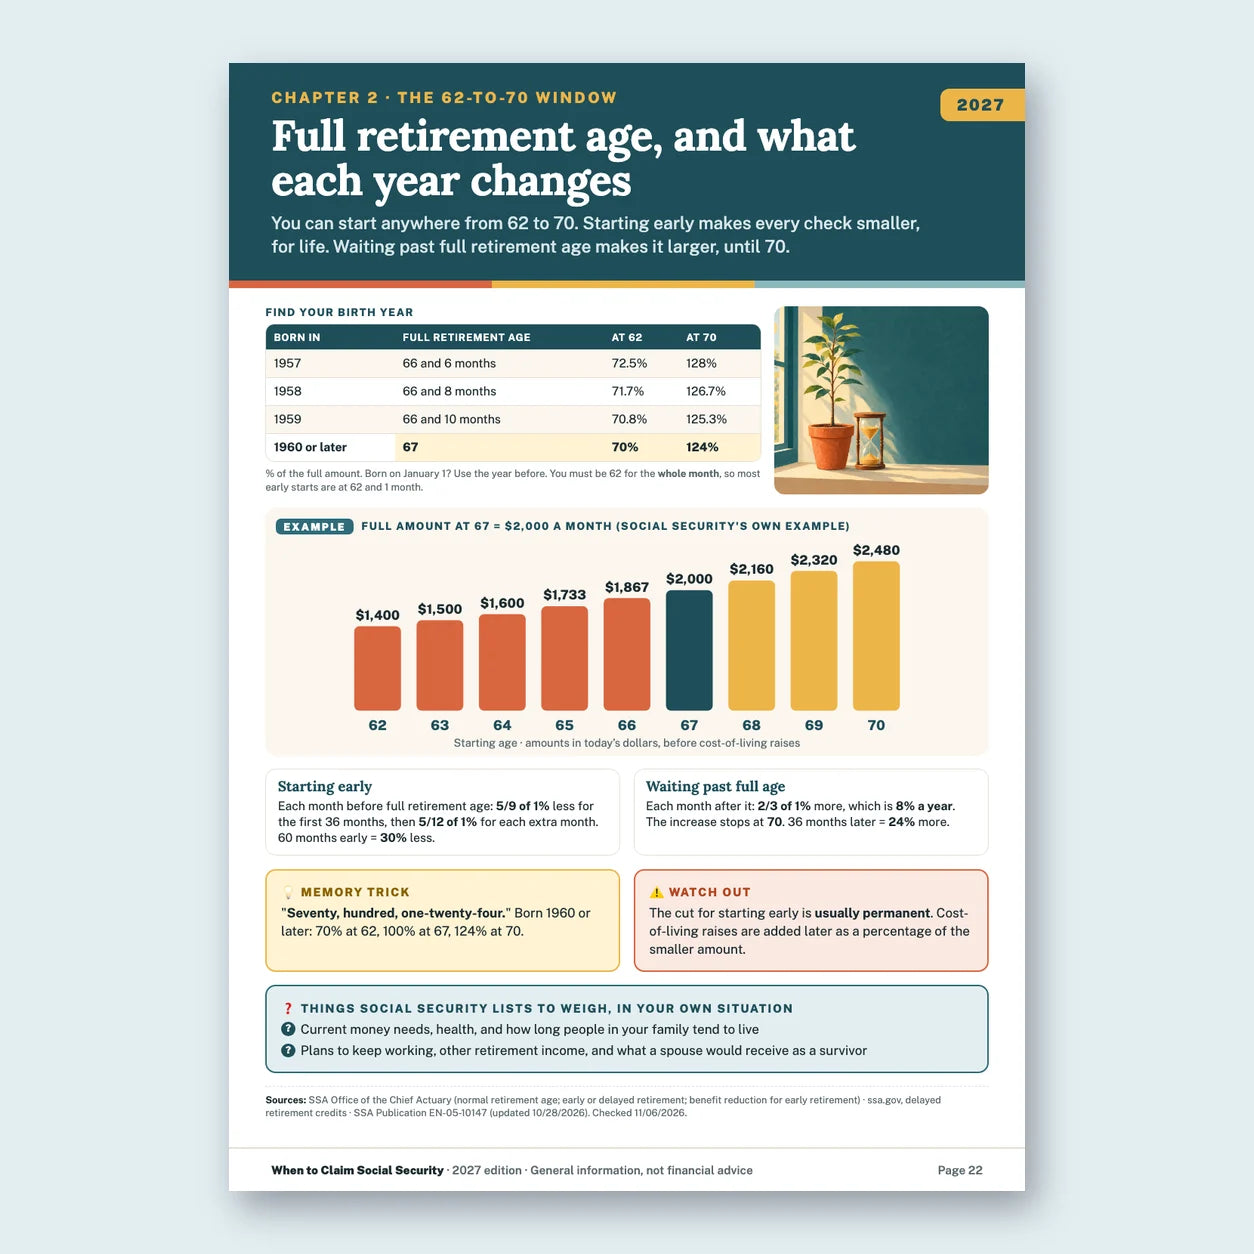
This is what the pages look like.


For couples and singles getting close to the decision.
Before the first application
How the benefit is built, what the Statement shows, and how each year between 62 and 70 changes the monthly amount.
Benefits on another record
Spousal, survivor and divorced-spouse benefits, with the age and marriage rules, and how they combine with your own.
Work, taxes and Medicare
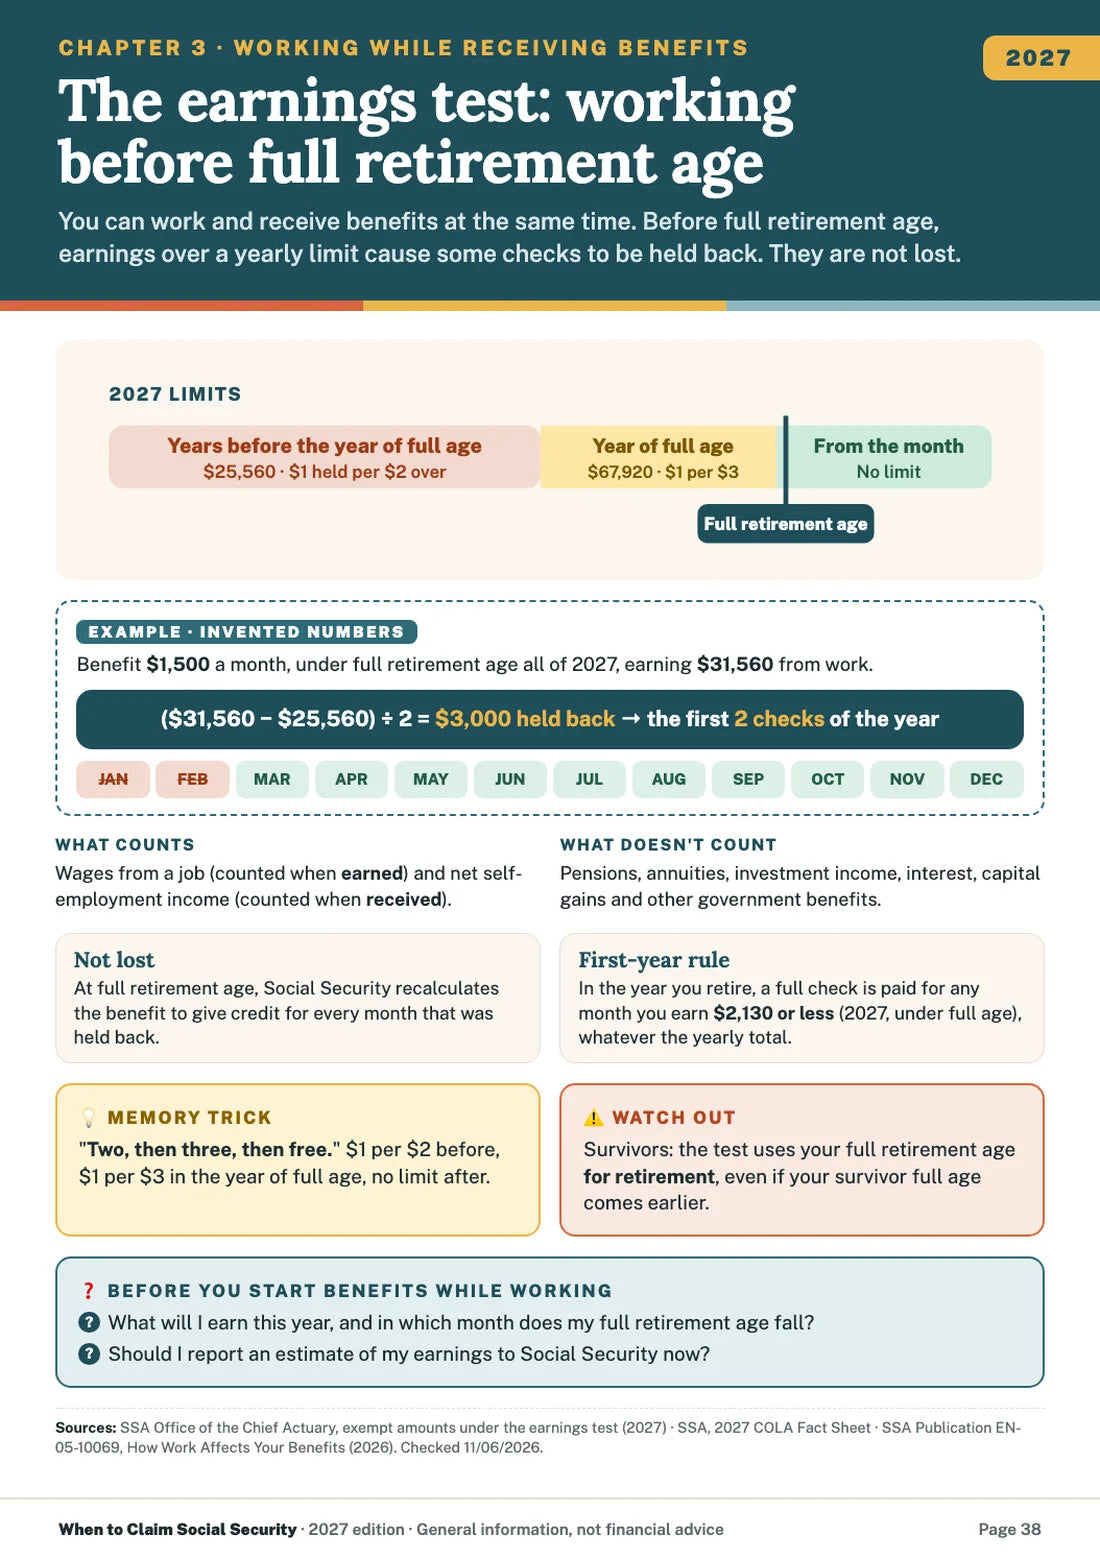
The 2027 earnings limits, how benefits are taxed, and the Medicare dates that don't move when Social Security does.
What's worth knowing before applying.
These rules are written down in Social Security's own manuals. The book explains each one with a diagram, the numbers and the source.
You can't take one and let the other grow
For people born on or after January 2, 1954, applying for a retirement benefit or a spousal benefit counts as applying for both, at any age.
The early start follows the survivor
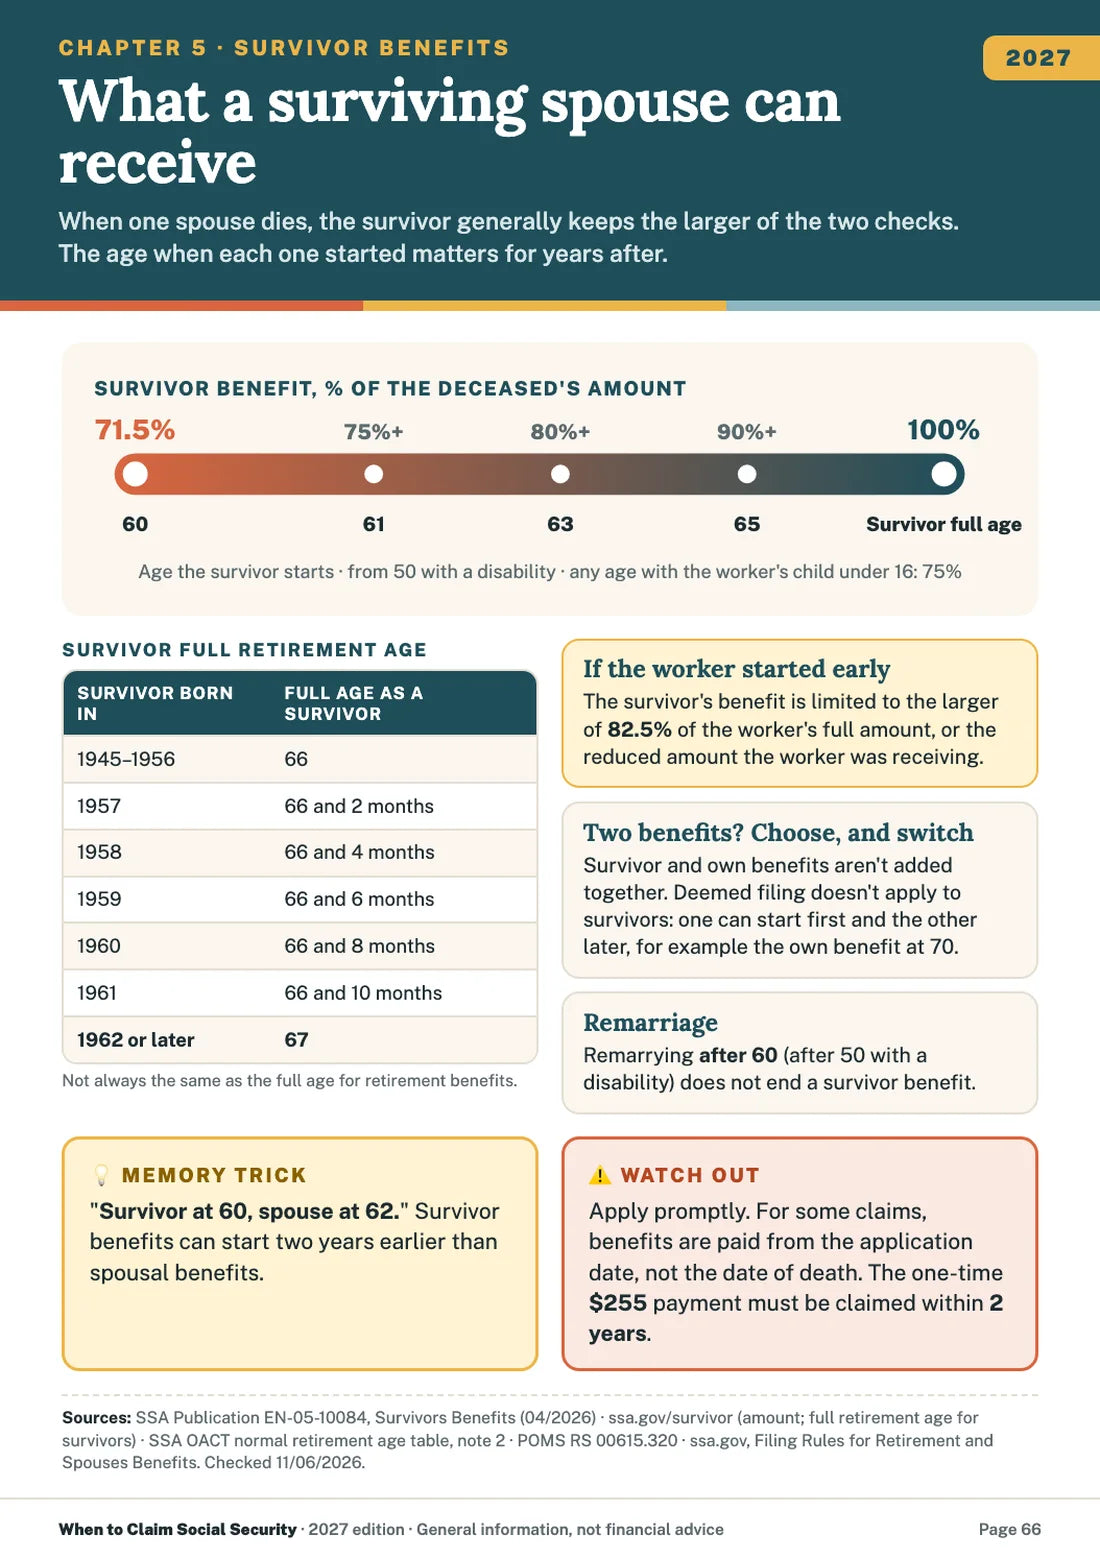
If a worker started early, the surviving spouse's benefit is limited to the larger of 82.5% of the worker's full amount or the reduced amount the worker received.
65 doesn't wait
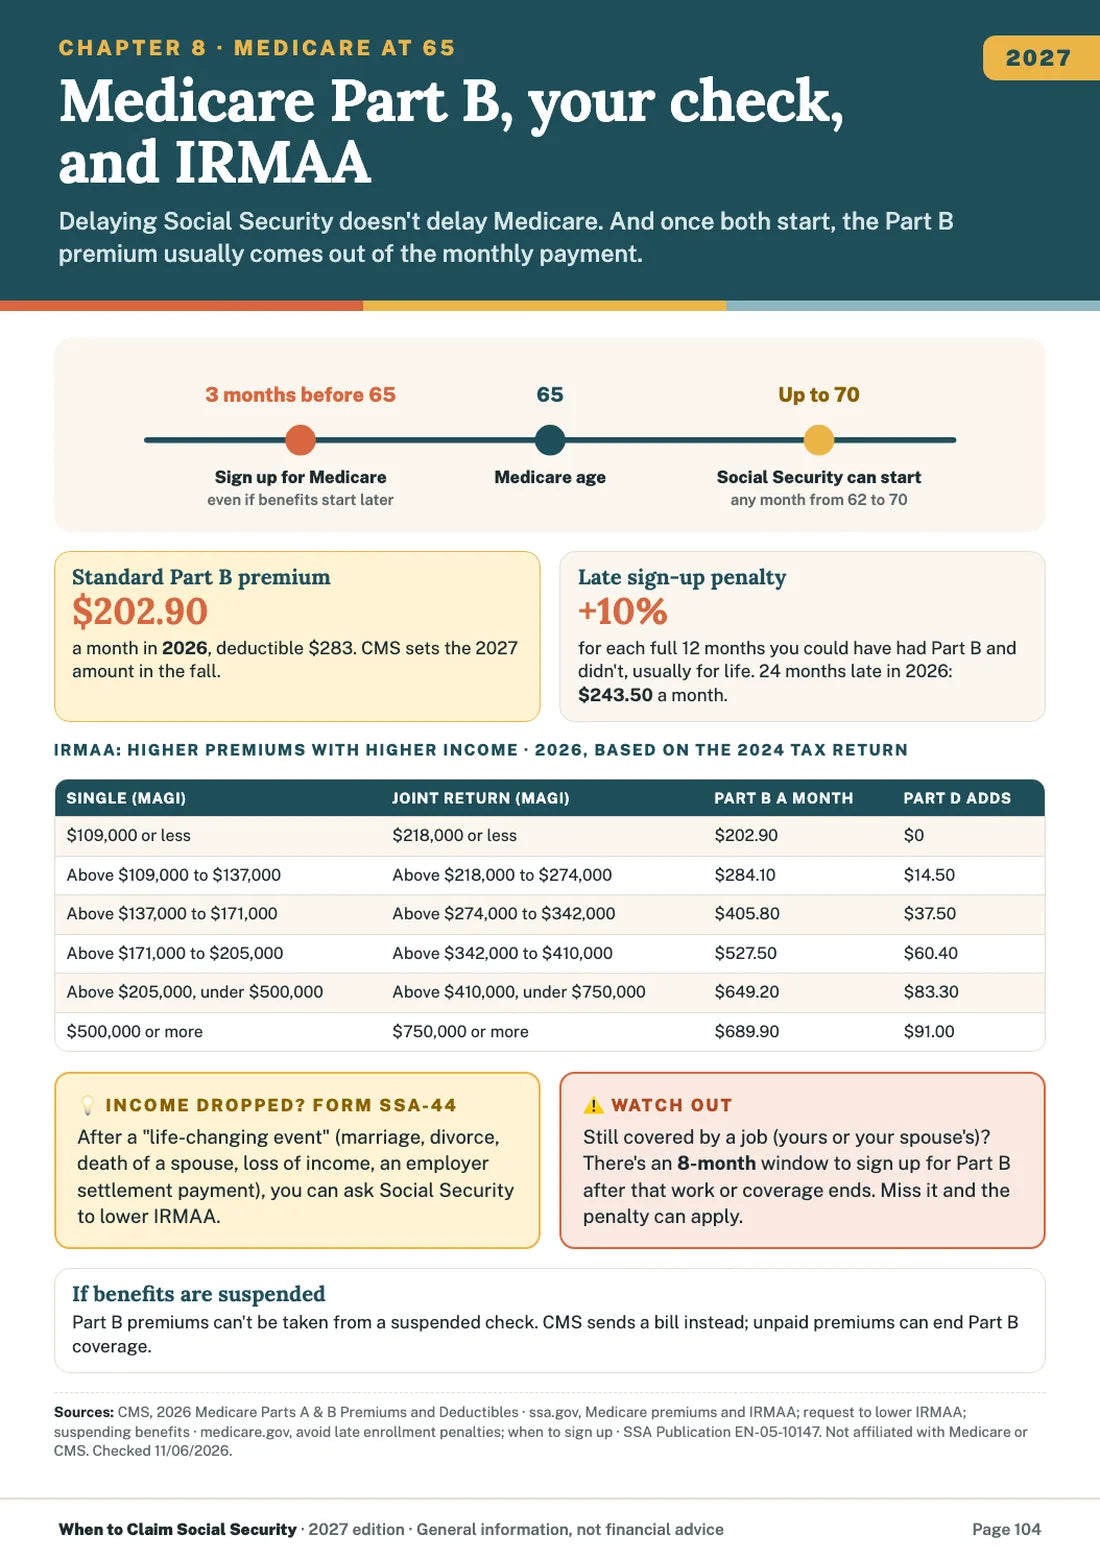
Social Security says to sign up for Medicare 3 months before 65 even if benefits start later. The Part B late penalty is 10% for each full 12 months, usually for life.
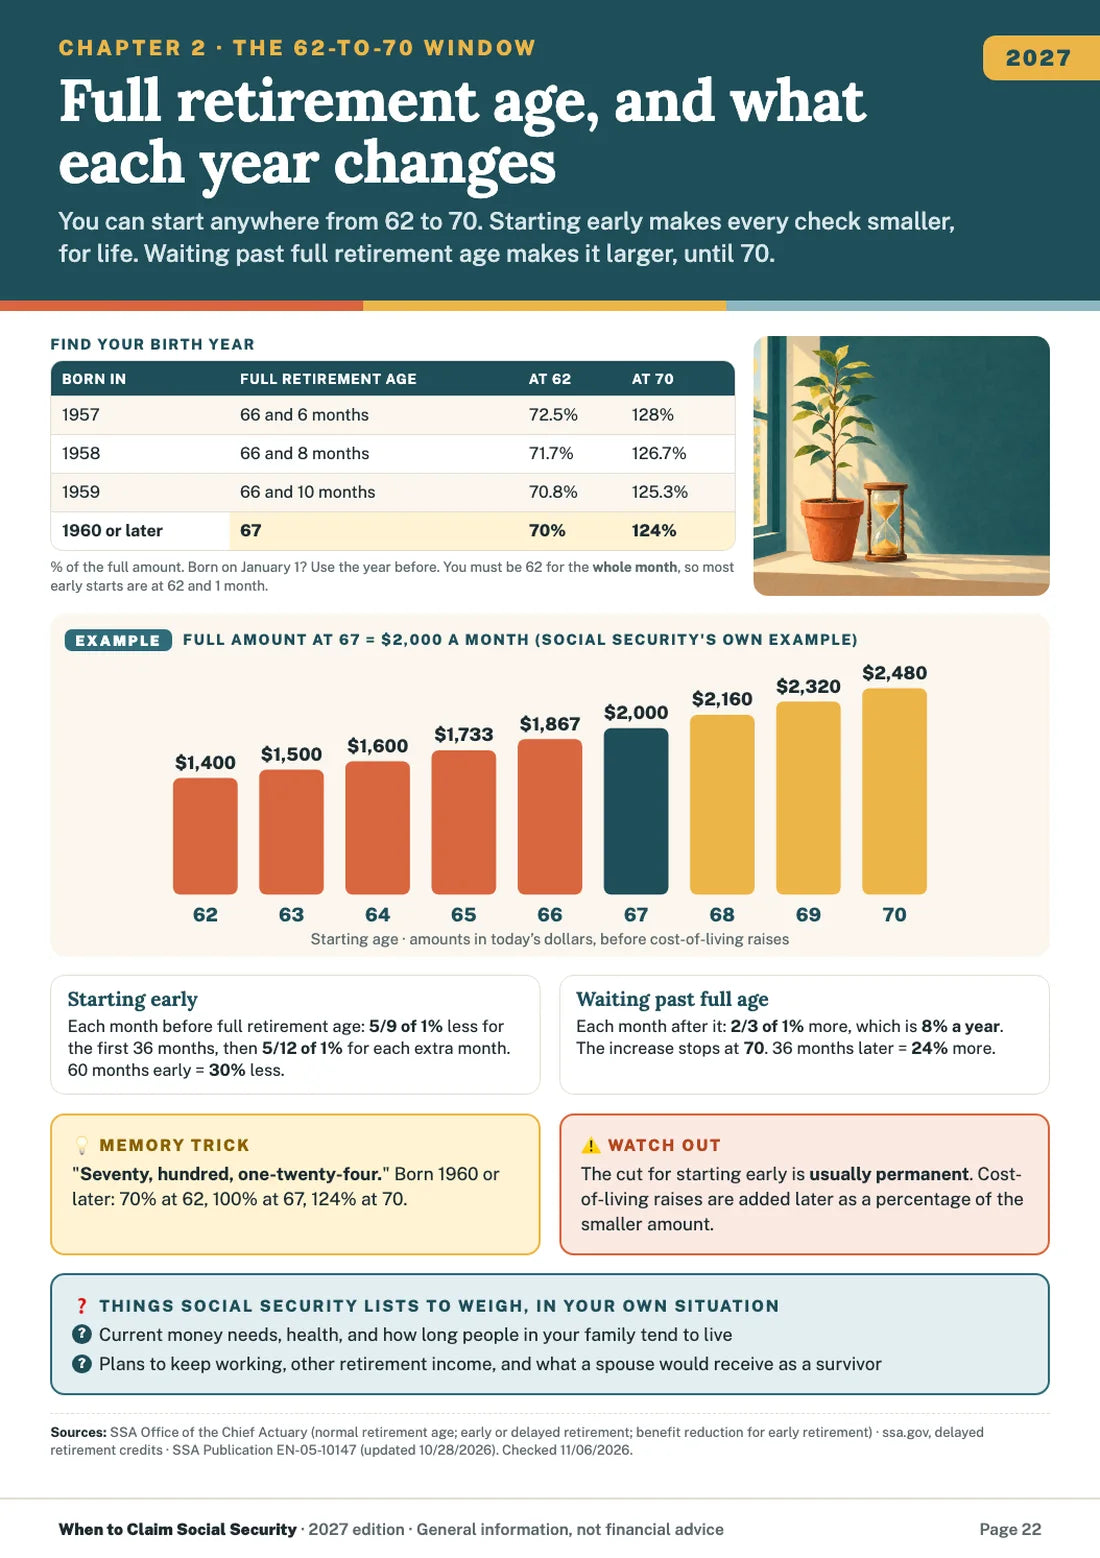
What each year between 62 and 70 changes.
Full retirement age by birth year, and the exact percentages for starting early or waiting, with Social Security's own $2,000 example.
- Born 1960 or later: 70% at 62, 100% at 67, 124% at 70
- The monthly formulas: 5/9 of 1%, 5/12 of 1%, 2/3 of 1%
- Why most early starts are at 62 and 1 month
- Back payments after full retirement age: up to 6 months
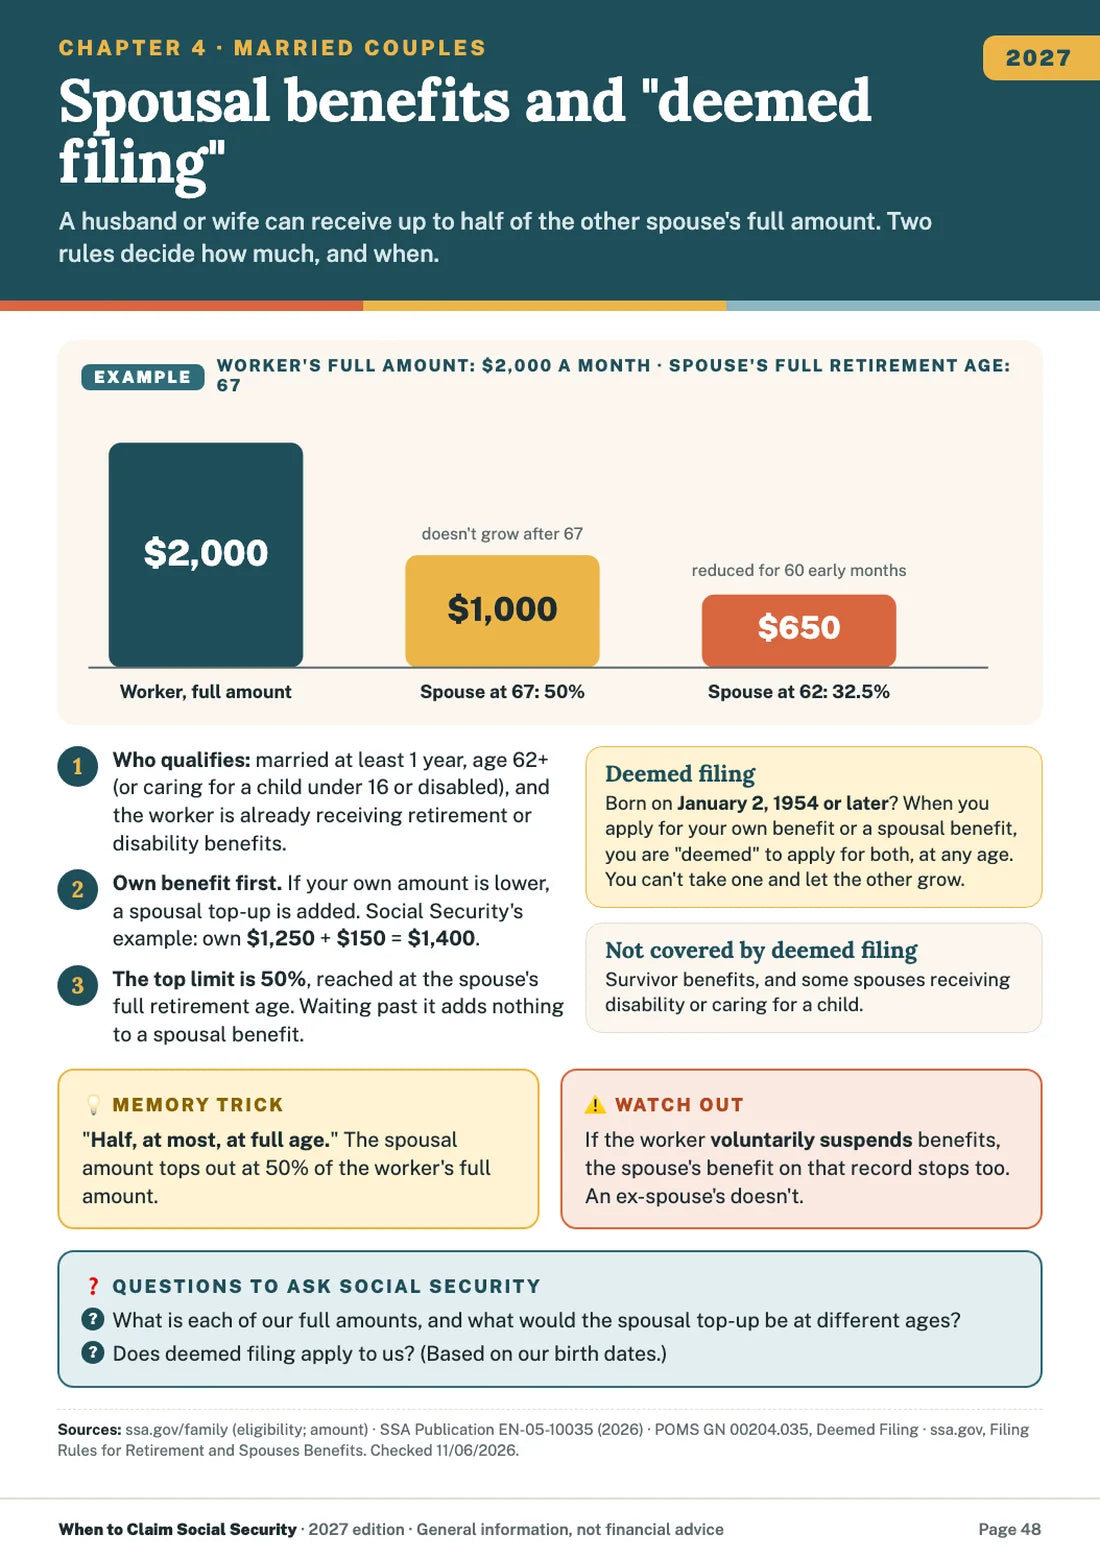
Up to half, and the rule that ties two benefits together.
Who qualifies for a spousal benefit, how the top-up is calculated, and why it stops growing at full retirement age.
- Own benefit first, then the spousal top-up: $1,250 + $150 = $1,400
- 32.5% at 62, 50% at full retirement age (full age 67)
- Deemed filing, for everyone born on or after January 2, 1954
- What a voluntary suspension does to the spouse's check
What the surviving spouse keeps.
From 71.5% at 60 to 100% at survivor full retirement age, and how the age the worker started can limit it.
- Survivor full retirement age by birth year, 1945 to 1962+
- The 82.5% limit when the worker started early
- Taking one benefit first and switching to the other later
- Remarriage after 60, and the one-time $255 payment
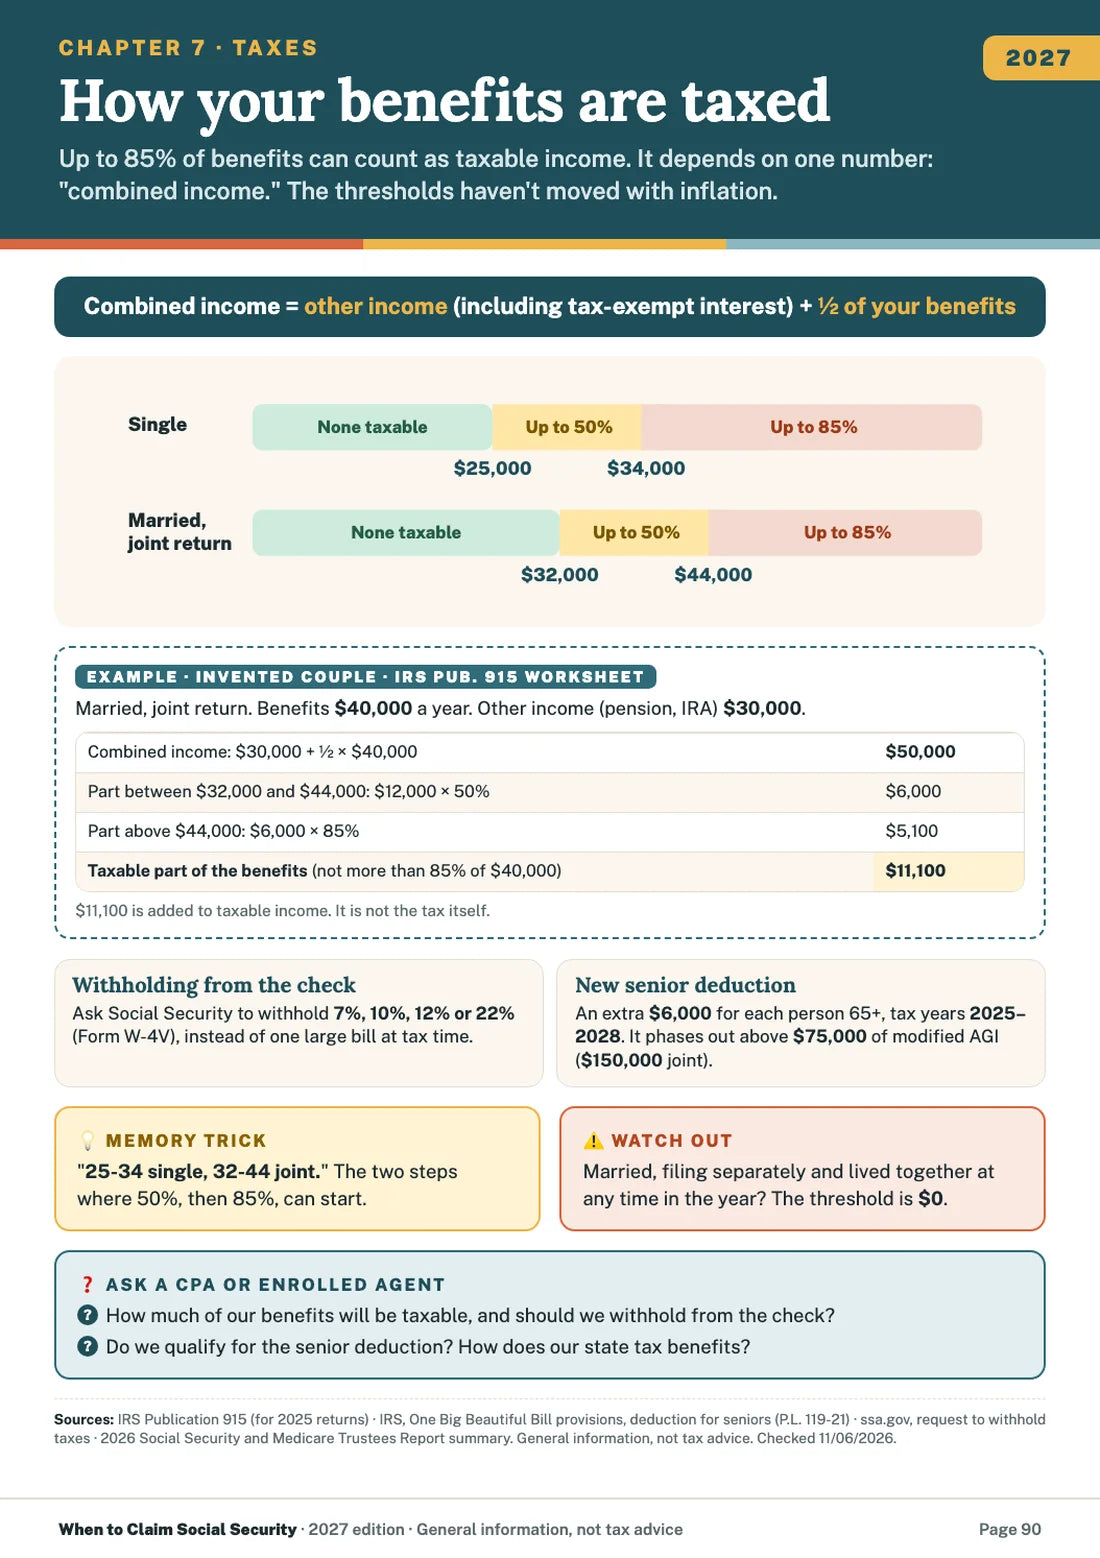
How much of the check counts as taxable income.
Combined income, the $25,000 / $32,000 and $34,000 / $44,000 thresholds, worked through line by line with the IRS worksheet.
- Why the thresholds haven't moved with inflation
- Withholding 7%, 10%, 12% or 22% from the check
- The $6,000 deduction for people 65+, tax years 2025–2028
- Questions to bring to a CPA or enrolled agent
Part B, IRMAA, and the late penalty.
The Medicare dates that don't move when Social Security does, and how the premium comes out of the monthly payment.
- IRMAA income brackets, and the tax return they're based on
- Form SSA-44 after a life-changing event
- The 8-month window after job-based coverage ends
- What happens to Part B if benefits are suspended
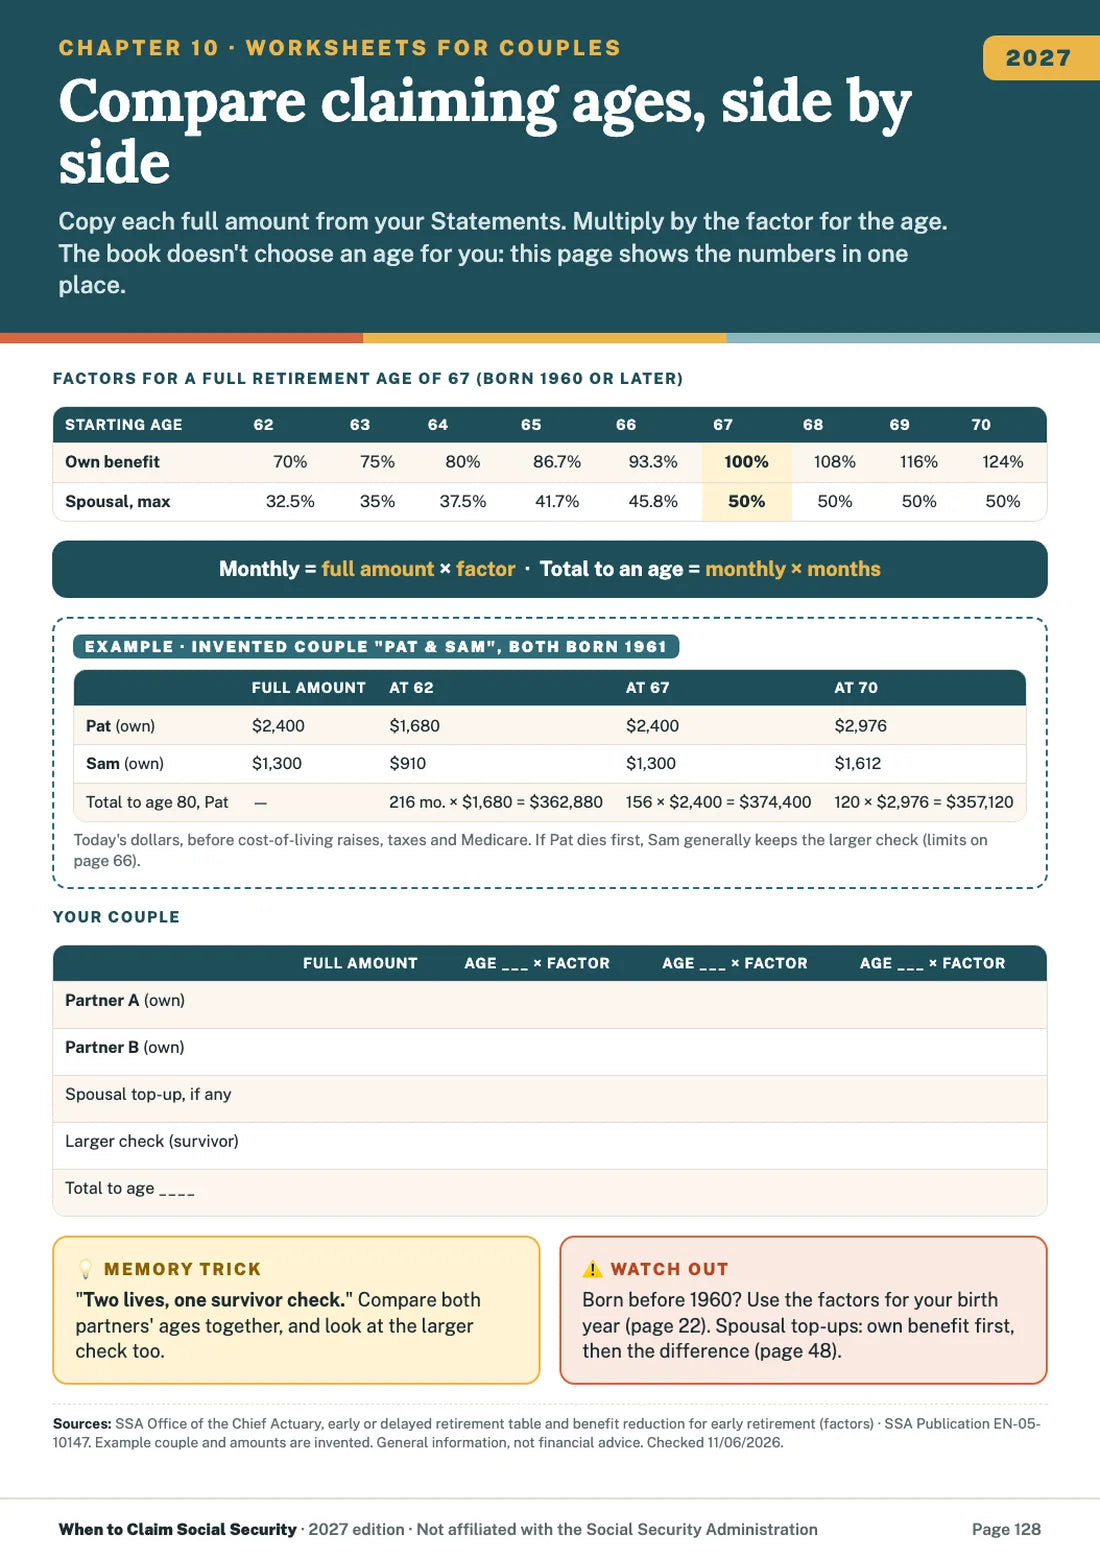
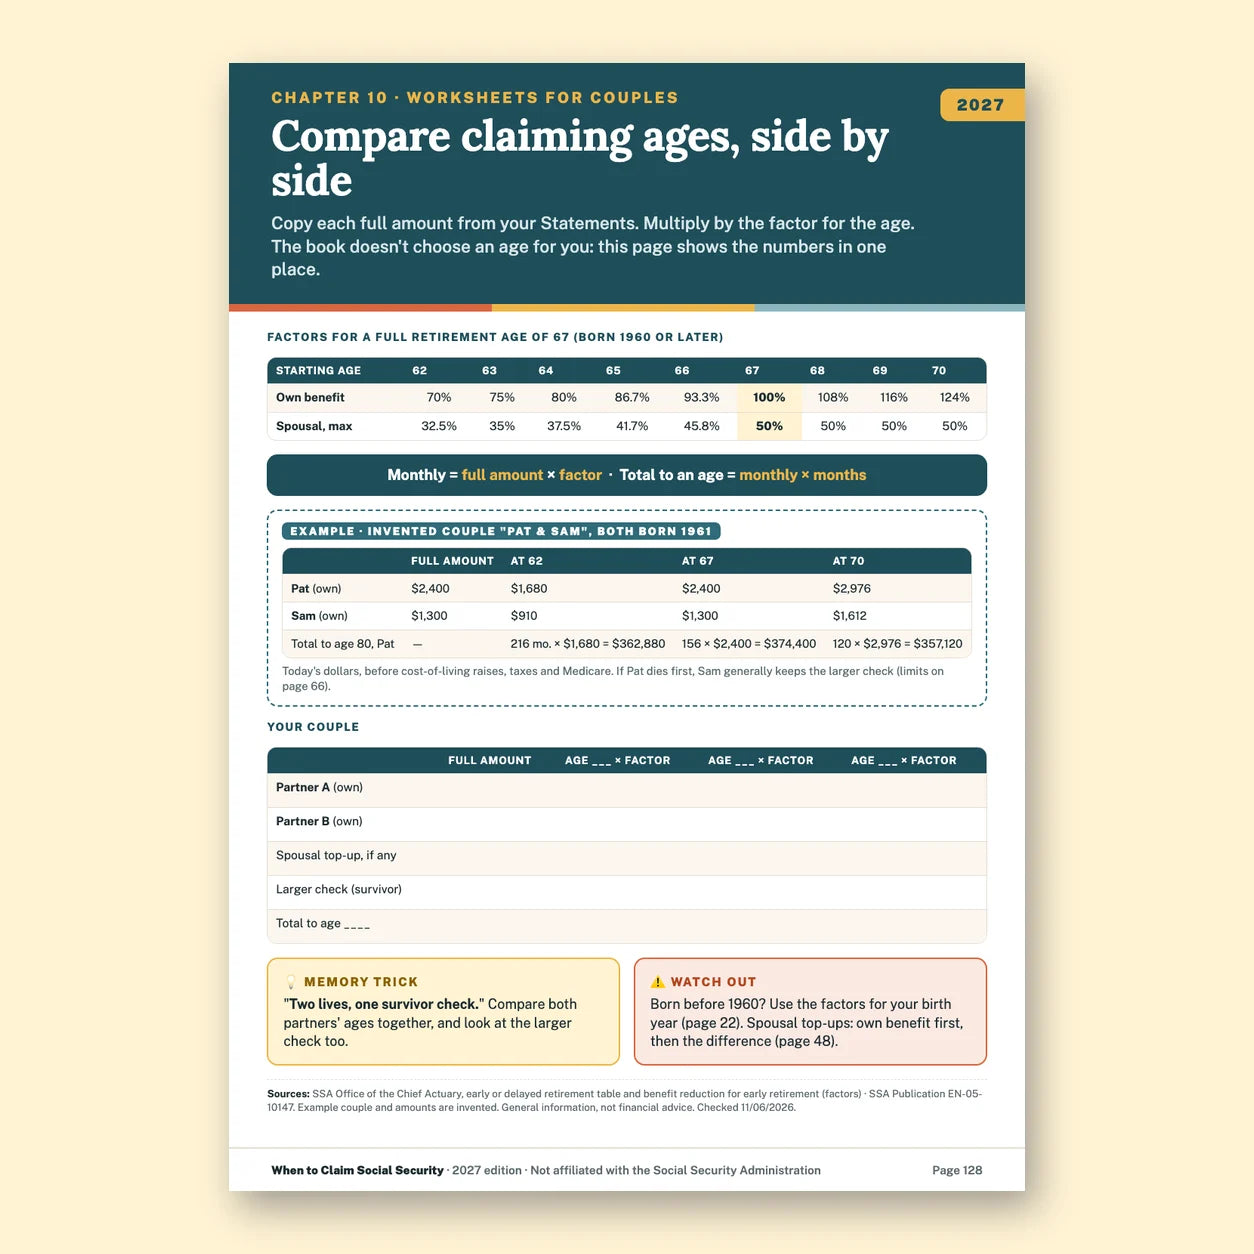
Both partners, side by side, on one page.
Copy the full amounts from your Statements, multiply by the factor for each age, and see the monthly amounts and totals together. The book doesn't pick an age: it lays out the numbers.
- Factor tables for own and spousal benefits
- A filled example with an invented couple
- The "larger check" line for the surviving spouse
- Blank worksheets to print as many times as needed (eBook)
Both of you look at the same page.
The claiming decision is usually a decision for two. Each chapter puts the rule, the number and the example on one page, so a couple can read it together and bring the same questions to Social Security or a planner.
- Built on Social Security's manuals and tables, cited on every page
- Examples clearly marked, with the official formula
- We don't sell insurance, annuities or investments
The claiming rules, in one illustrated guide.
Full table of contents
On screen, on paper, or both.
Color PDF, right after payment
Open it on a phone, tablet or computer. Print the worksheets as many times as you need.
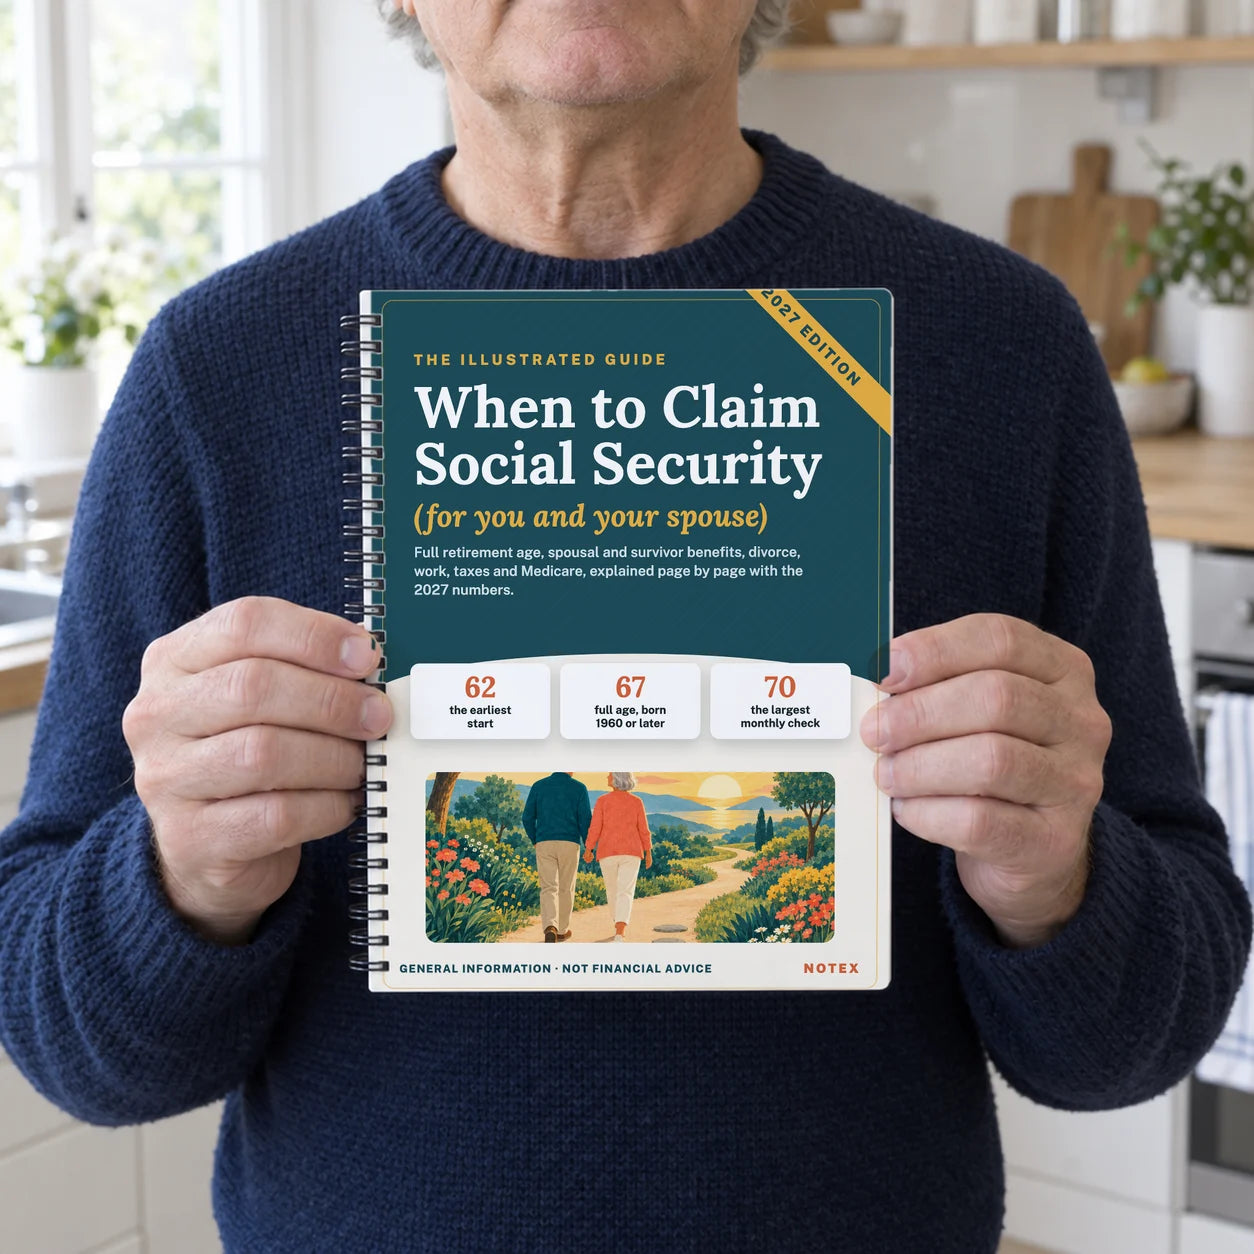
176 color pages, spiral-bound
Lies flat next to the Statements and a calculator. Free shipping to US addresses, about 5–8 business days. Want both? Printed + eBook for $79.99.
The worksheets and the checklist.
Fill-in pages to compare ages as a couple, an application checklist with the documents Social Security asks for, and the official phone numbers and websites in one place.
- Couple comparison sheets with factor tables
- Application checklist: documents, dates, questions to ask
- With the eBook: print them again whenever you need
See 10 real pages, free.
The 2027 numbers, the Statement, full retirement age, the earnings test, spousal benefits, survivors, divorced spouses, taxes, Medicare and the couple worksheet. Read them and decide with the pages in front of you.
See the 10 pages ↓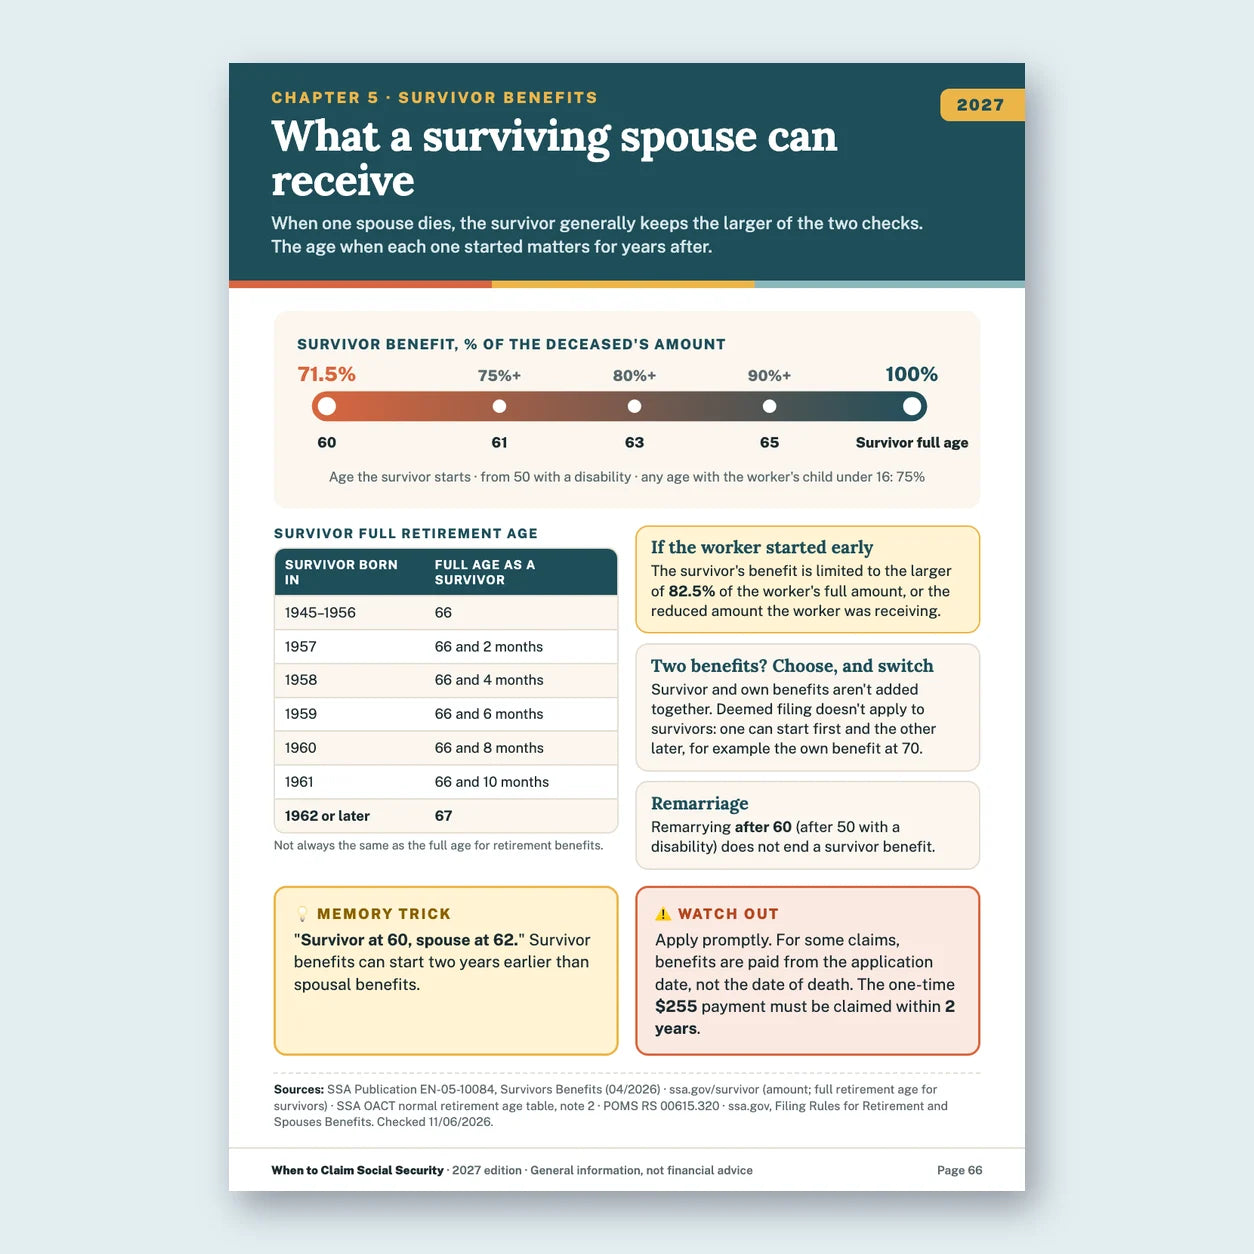
How is it different?
| What it has | This guide | ssa.gov | Books on Amazon | Financial planner |
|---|---|---|---|---|
| Spouses, survivors, divorce, work, taxes and Medicare in one place | ✓ | Spread across many pages | Varies | ✓ |
| Charts, flowcharts and worked examples on every topic | ✓ | Some | Varies | — |
| 2027 numbers with the source on each page | ✓ | ✓ | Varies | — |
| Fill-in worksheets for couples | ✓ | Online calculators | Varies | — |
| Advice on your own situation | ✗ General information | Personal estimates in your account | ✗ | ✓ |
| Price | From $39.99 | Free | About $5 to $24 | Fees vary |
You can start reading tonight.
You pay
Secure checkout, no account, no subscription. One payment.
You open the eBook
If you chose the eBook, the download link arrives by email. Open it on a phone, tablet or computer.
The book arrives
If you chose the printed book, it ships free to your US address.
The claiming rules, explained for both of you.
- 176 illustrated color pages, 14 chapters
- Full retirement age, the 62–70 window, the earnings test
- Spousal, survivor and divorced-spouse benefits, with deemed filing
- Taxes on benefits, Medicare Part B and IRMAA
- 2027 numbers, each with its official source
- Worksheets to compare claiming ages as a couple
- Printed book: spiral-bound, lies flat, free US shipping
What people ask before buying
Will the book tell me when to claim?
No. Social Security itself says there's no single best age for everyone. The book explains the rules, the percentages and the formulas, shows worked examples, and gives you worksheets to lay out your own numbers. The decision, and any personal advice, stays with you and the professionals you choose.
Is this financial, tax or legal advice?
No. This guide provides general information, not financial, tax or legal advice. For your own situation, get your personal estimates from your my Social Security account, and talk with Social Security, a CPA or enrolled agent, or a financial professional.
Are you affiliated with the Social Security Administration?
No. We are not affiliated with or endorsed by the Social Security Administration, Medicare, CMS, the IRS or any government agency. Applying for Social Security is free on ssa.gov or by phone.
Are the numbers up to date?
The 2027 Social Security figures (cost-of-living raise, earnings limits, maximum taxable earnings, averages) were published on October 14, 2026 and checked on November 6, 2026. Medicare's 2027 Part B premium had not been published yet, so the book shows the 2026 amount and says so. Each page shows its source.
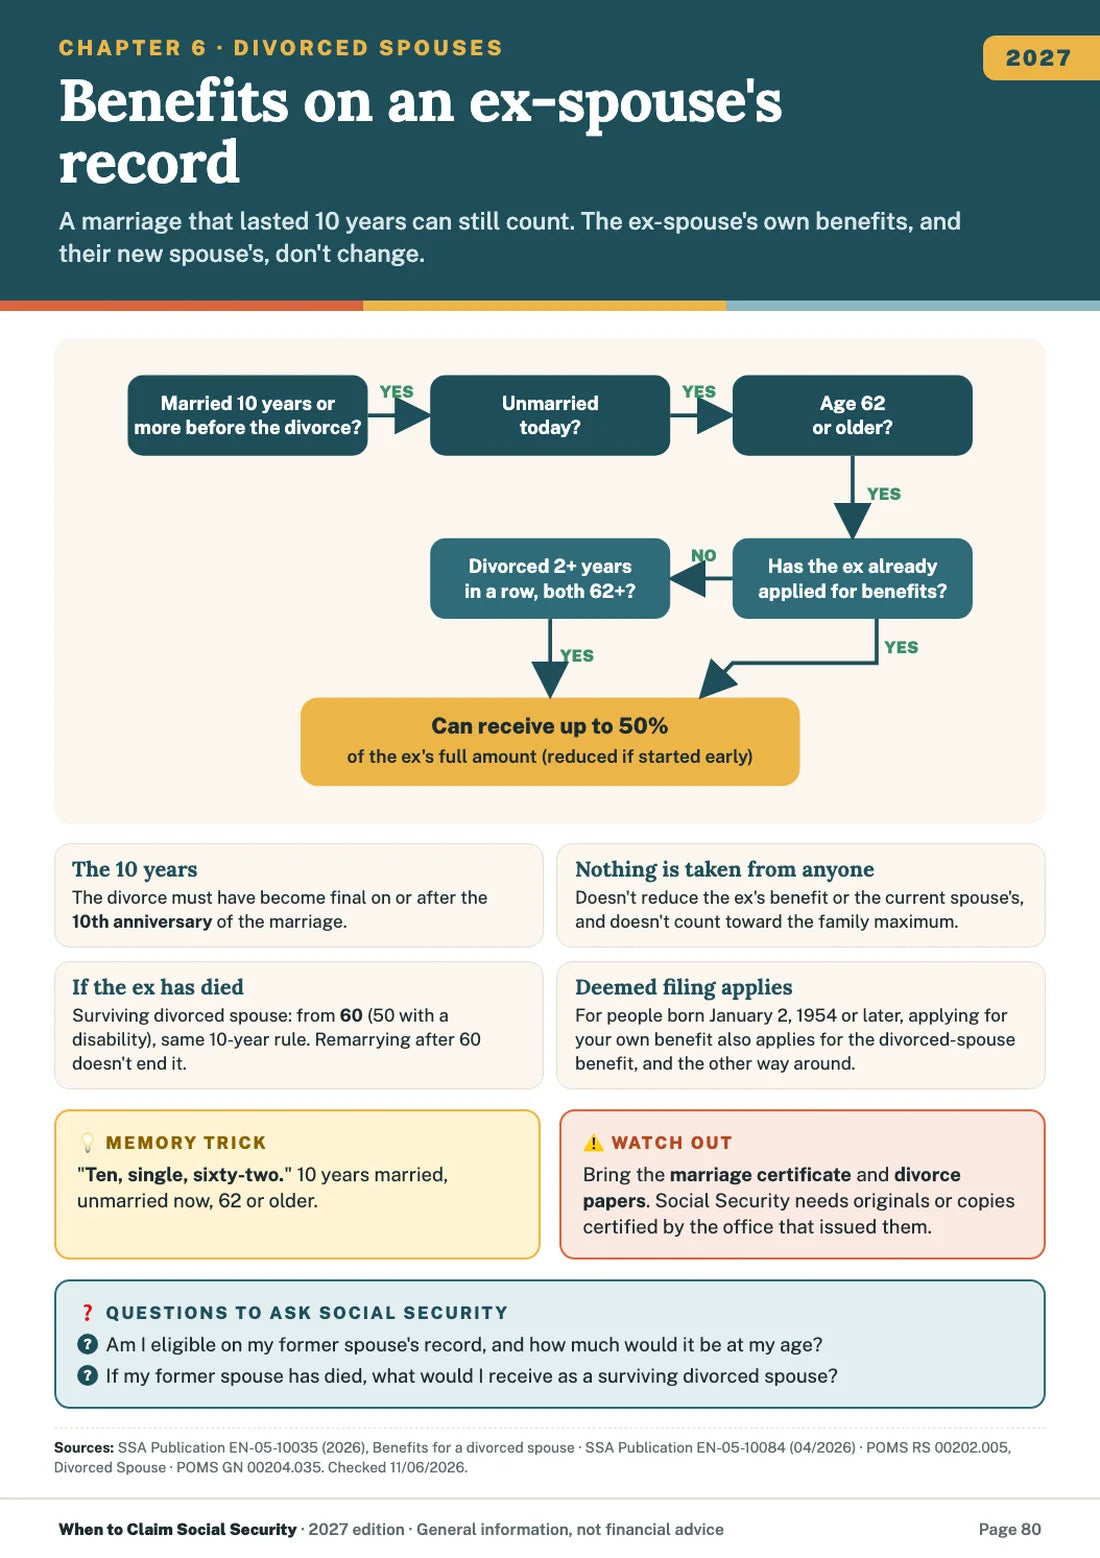
Does it cover divorced and widowed people?
Yes. A full chapter on survivor benefits and one on divorced-spouse benefits: the 10-year marriage rule, age rules, remarriage, and how these benefits combine with your own.
What about government pensions (WEP and GPO)?
The Social Security Fairness Act, signed on January 5, 2025, ended WEP and GPO for benefits payable from January 2024. The book explains what that means for spousal and survivor benefits.
I'm single. Is it still useful?
Yes. Full retirement age, the 62–70 window, the earnings test, taxes and Medicare apply to everyone. The couple chapters are a part of the book, not all of it.
Do you sell annuities or investments?
No. We sell the guide only. We don't sell insurance, annuities or investments, and we don't receive referral fees.
Can I read it on my phone?
Yes. The eBook is a color PDF that opens on a phone, tablet or computer. You can print the worksheets and any page you want.
When does the printed book arrive?
Shipping to US addresses is free and takes about 5–8 business days. The eBook arrives by email right after payment.
What if it's not right for me?
You have a 30-day guarantee. Write to us within 30 days and we'll refund you. No questions, no forms.
Ready to see what each claiming age changes?
176 illustrated pages, 2027 numbers with sources, worksheets for couples. 30-day guarantee.
From $39.99 · eBook or printed